Get a Loan Against Your State Life Policy: Up to 80% of Surrender Value
Get a loan against your State Life policy, up to 80% of its surrender value. Who qualifies, the four papers, the conflicting markup rates and surrender options.
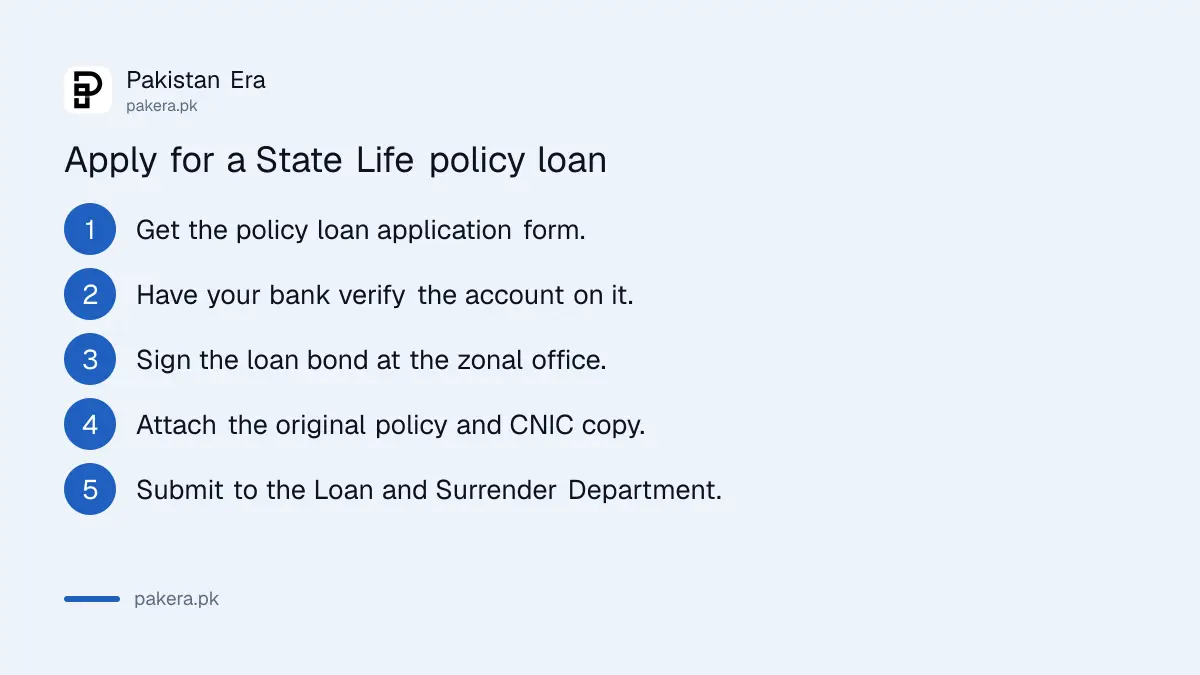
State Life lends up to 80% of your policy's net surrender value. The policy must have run at least two years with no premium in default. Take the loan application form, a loan bond, the original policy and your CNIC copy to your State Life zonal office. The money goes into your bank account, and you can repay it any time.
A family emergency rarely waits for payday. Before a hospital bill or school fee pushes you towards a loan app, check the State Life policy in the cupboard. It may already be worth a lot of cash. We read State Life Insurance Corporation's own procedure page, its loan application form and its FAQs. One warning comes first: State Life's own pages give three different markup rates, so ask for the current rate in writing before you sign.
A State Life policy loan pays up to 80% of surrender value
State Life gives a loan of up to 80% of the policy's net surrender value. Surrender value is what the policy would pay if you ended it today. A policy builds surrender value only after two years in force, with all premiums paid.
State Life's FAQ explains it like this. A policy "will acquire a surrender value after it has been in-force for at least two consecutive years provided no premiums are in default". Bonus is added to the surrender value once the policy has been in force for three years. "Net" means after anything you already owe State Life on that policy, such as an earlier loan.
So a policy bought last year cannot give you a loan yet. A policy you have paid into for ten years may support a large one. Your zonal office can tell you the exact figure.
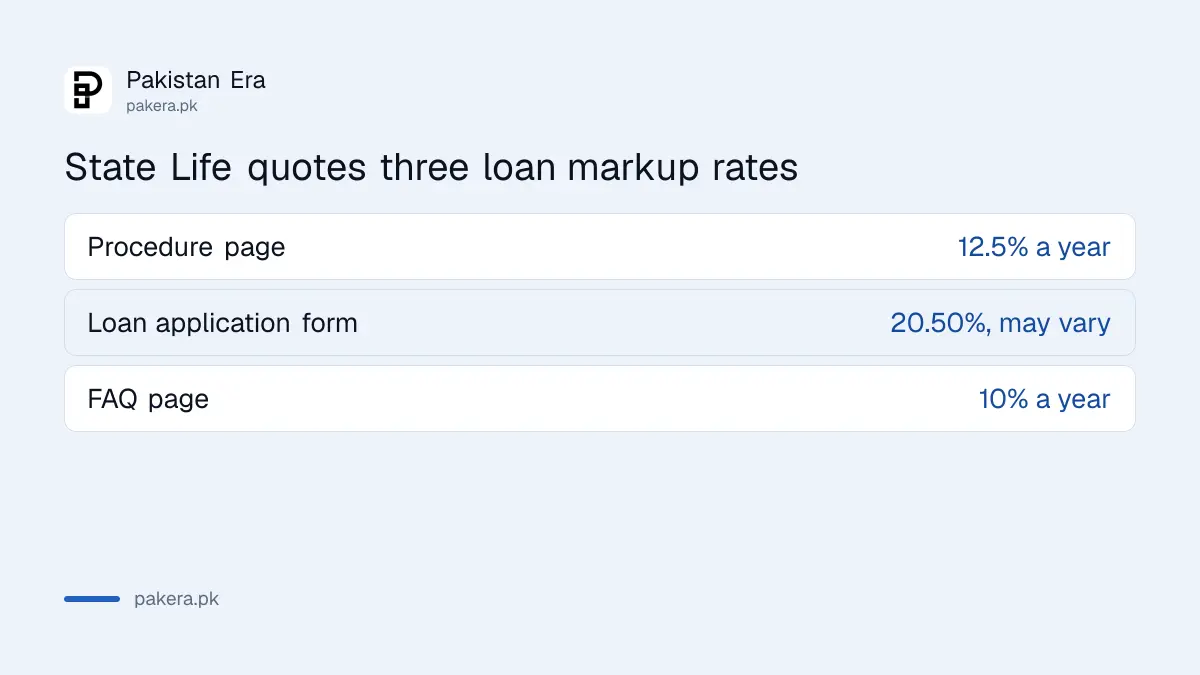
State Life's own pages give three different markup rates
State Life's procedure page says 12.5% a year, compounded every six months. Its loan application form says 20.50%, which "may vary quarterly". Its FAQ says 10%. The rate that binds you is the one in your loan bond.
| Where we read it | Rate stated | Wording |
|---|---|---|
| Manage Your Policy page, loan procedure | 12.5% a year | Compounded semiannually |
| Policy loan application form | 20.50% | May vary quarterly |
| FAQ, questions 27 and 30 | 10% a year | Compounded semiannually, payable half-yearly |
We cannot tell you which one is current, because State Life has not said. Ask the zonal office to write the rate on your copy of the loan papers. A policy loan is secured on your own policy, so the worst case is a smaller final payout, not daily recovery calls from online loan apps.
Four papers get the loan approved
State Life's loan form lists four requirements: the filled loan application form, the original policy documents, a loan bond, and a copy of your valid CNIC. You submit them at the zonal office that services your policy.
- Download the policy loan application from State Life's forms page, or ask for it at the zonal office.
- Fill in the policy number and your bank account. The form asks the bank to verify your account with a signature and stamp.
- Sign the loan bond. The zonal office provides it.
- Attach the original policy and your CNIC copy.
- Submit at the zonal office addressed to the Manager, Loan and Surrender Department. State Life's FAQ says the loan amount is credited to the bank account you give.
Lost the policy? For a loan you need a duplicate first. State Life's FAQ says this needs an affidavit, a newspaper notice, the policy stamp and a Rs 25 alteration fee, and takes about one month.
Repay the loan any time, or it comes out of the payout
You can repay a State Life policy loan in part or in full at any time during the policy term. If you never repay, State Life takes the loan and markup out of the final payment, at maturity or on a death claim.
That second point is the hidden cost. An unpaid loan keeps growing with markup every six months. It then shrinks what your family receives. If you can, repay it. State Life's FAQ says premiums and loan payments can be made on its website, at any Bank Alfalah branch, or through JazzCash.
State Life also offers an Automatic Premium Loan option. If you miss a premium after the 31 day grace period, State Life treats the premium as paid by lending it to you against the surrender value. This keeps the policy alive, but it is still a loan with markup.
Surrender ends the policy and should be the last choice
Surrendering means ending the policy for its cash value. State Life asks you to fill a surrender request form and a discharge voucher verified by your bank at the zonal office. All cover and benefits stop, so State Life itself suggests a loan instead.
State Life's procedure page says it directly: after surrender "the policy loses all the benefits and facilities and your risk coverage ceases". The loan keeps the cover alive. The surrender does not.
There is a third route for some plans. If you hold an Anticipated Endowment Assurance policy that has completed one third or two thirds of its term, you can withdraw 25% of the sum insured as a survival benefit. Send a written request with the original policy, a CNIC copy and the survival benefit discharge voucher verified by your bank.
- Loan: cash now, cover continues, markup charged.
- Survival benefit: part payment on some endowment plans, no markup.
- Surrender: cash now, cover ends for good.
Complain in writing if the zonal office stalls
If a loan or surrender request is delayed or refused, write to State Life's complaint cell at its Principal Office in Karachi and keep a receipt. If that fails, the Federal Insurance Ombudsman hears insurance complaints free of charge.
State Life's helpline is 051-111-777-542. Its complaint cell is at State Life Building No. 9, Dr Ziauddin Ahmed Road, Karachi, on 021-99206868. The next step after that is the Insurance Ombudsman complaint.
Common questions
How much loan can I get against my State Life policy?
Up to 80% of the net surrender value. Your zonal office will calculate the exact amount for your policy.
What is the State Life policy loan interest rate?
State Life's pages disagree: 10%, 12.5% and 20.50% all appear. Get the current rate written on your loan papers.
Can I get a loan on a new policy?
No. A State Life policy gets a surrender value only after two years in force with no premium in default.
Do I have to repay the policy loan?
You can repay any time. If you do not, State Life deducts the loan and markup from the final payment.
Can I take a loan if I lost the policy document?
Not straight away. You need a duplicate policy first, which takes about a month according to State Life's FAQ.
Is it better to surrender or take a loan?
A loan usually. Surrender ends your cover for good, while a loan keeps the policy and its bonuses running.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on 3 October 2026. We read State Life's Manage Your Policy page for the loan, surrender, survival benefit and complaint procedures, the policy loan application form on its forms page, and its FAQs. The three markup rates come from those three State Life pages and conflict with each other; State Life has not published which is current. This covers State Life only. Other life insurers set their own loan terms.
About the author
Tax, Bills and Technology Writer
Ali Akhtar is a young and curious voice here at Pakistan Era. He is currently pursuing his A-Levels and has a growing interest in Pakistan’s changing industrial landscape and educational trends. Ali likes to write in a way that helps him explain and explore the world around him. His writing reflects the perspective of the new generation navigating the evolving trends of Pakistan where technology, youth innovation, and shifting opportunities are reshaping the country’s future.