Check a Bank's Insurance Offer in Pakistan: What SBP Says the Bank Must Do Before You Sign
A bank must say it is only a distributor, give a fact sheet and cannot close an insurance sale on one call. See SBP's rules and how to check an offer.
Short answer: When a bank in Pakistan sells you insurance or takaful, SBP's conduct framework says the bank must tell you it is only a distributor, cannot tie the policy to your account or loan unless you ask, must hand you a separate fact sheet, and must let you cancel in the free look period. It also cannot sell and close the deal on the same call.
You go to a branch to open a savings account. Twenty minutes later you have also signed a yearly premium you did not plan for. The plan sounded like a savings product. This is the sale the State Bank of Pakistan (SBP) rules are written for.
We read SBP's Business Conduct and Fair Treatment of Consumers Regulatory Framework, issued with BPRD Circular No. 04 of 2025, on 12 October 2026. The rules for the sale of insurance and takaful through a bank sit in its section 3.2.5. Bancassurance is the word for insurance sold through a bank. Bancatakaful is the same for takaful, the Islamic form of insurance.
A bank cannot bundle insurance with your account or loan unless you ask
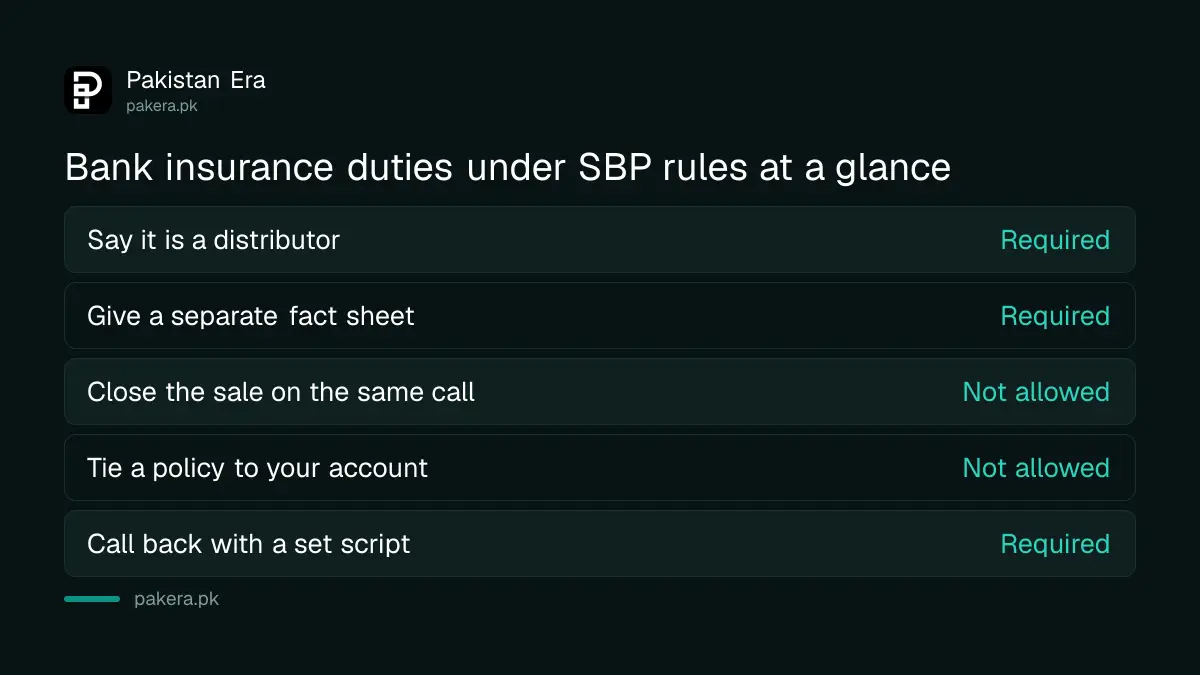
The framework says banks shall not bundle products or services unless the customer makes a request or gives explicit, verifiable consent. It goes further for third party products. Banks are prohibited from bundling their products with those issued by a third party, and it names bancassurance as the example.
In plain words, an account, a card or a loan cannot be offered on the condition that you also take a policy. A loan may need insurance on the asset, but the bank must say so in its terms. The terms must state whether the cover is a condition or an option, and whether you can use an insurer other than the bank's panel.
Insurance on a car or house loan has its own rule. The bank must keep that cover adjusted when the value of the asset goes up, so you stay protected. For digital products, the bank may offer transactional insurance only at reasonable charges, and it must start only after your explicit request or consent.
The bank must say it is a distributor and cannot close the sale on the first call
The framework bans a bank from marketing a third party product under its own name without saying it sells as an agent or distributor. It also bars the bank from marketing and closing the sale of a third party product on a single call.
The fact sheet repeats this. It must carry a disclaimer that the bank works only as a distributor. The insurer is the company that carries the risk and pays the claim. That is the name to check, and you can confirm the insurer is licensed by SECP before you pay.
You must get a separate fact sheet in Urdu or English
Before you sign, the bank must give you a basic fact sheet. It must be a distinct looking document, and it must include your undertaking that you understood the terms. You choose Urdu or English.
| What the fact sheet must show | Why it matters to you |
|---|---|
| A two line definition of the product | You can tell insurance from a savings plan |
| A disclaimer that the bank is only a distributor | You know who pays the claim |
| Expected return and the premium schedule | You see what you pay and when |
| How to encash early, with penalties and deductions | You know the cost of leaving |
| How to lodge a claim | You know where to go if something happens |
| How to complain, including the Federal Insurance Ombudsman | You know where to escalate |
| A checklist of every other document signed | Nothing is signed without your knowing |
For a plan with no investment part and a yearly premium of up to Rs 50,000 sold through a digital channel, the fact sheet may come by email or SMS, and your consent can be electronic. Either way, you should have it before you pay.
Senior citizens, widows and pensioners get a second approval
The framework asks for extra care. A request from a senior citizen, a widow, an illiterate person, a person with a disability or a pensioner to buy a third party investment product must be approved at least at Regional Head level. The branch manager must sign an undertaking that the terms were explained properly.
If you are helping a parent, ask the manager whether that undertaking has been signed. You can also ask for the suitability assessment. The bank must keep the record until one year after the product matures.
A call back from another staff member must confirm you understood
The bank must call you back using a set script to confirm what you told it and that you understood the product. The framework says this call cannot be on the same day as the sale and must be made by staff who earn nothing from selling the product.
The call must happen at least three days before the free look period starts, as the framework words it. If you say no on that call, or ask to cancel, the bank must mark it so you can exit without charges. The bank keeps the recording for at least seven years or until the product matures, whichever is later.
You can cancel in the free look period, and the bank must help
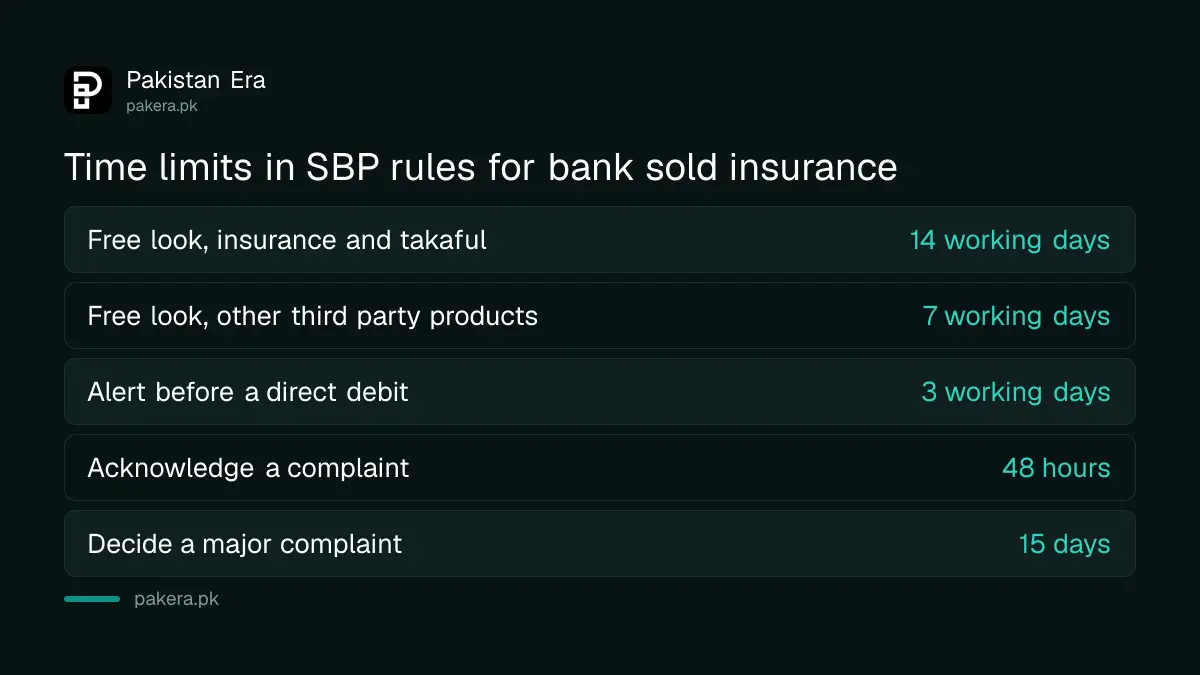
The framework sets the free look period for bancassurance and bancatakaful at 14 working days, in line with SECP regulations. For other third party products it is at least 7 working days. The bank must help you cancel through all its channels, without waiting for the policy papers to arrive.
Counting is where people lose money. The SBP text says working days. The SECP rules for cancelling a life insurance policy within 14 days count 14 days from receipt of the policy documents. Do not wait for the last day. Write to the insurer in the first week.
Premiums by direct debit need your consent and a three day warning
A bank or insurer may take the premium straight from your account only with your verifiable consent. It must send a free SMS or email at least three working days before each deduction. That alert is your chance to stop a payment you no longer want.
If you did not agree to a deduction, you can ask the bank to stop the standing instruction or auto debit. The framework also says banks may not make direct debits without explicit consent.
How to check a bank's insurance offer before you sign
Use this list at the branch, or on the phone before you agree to anything.
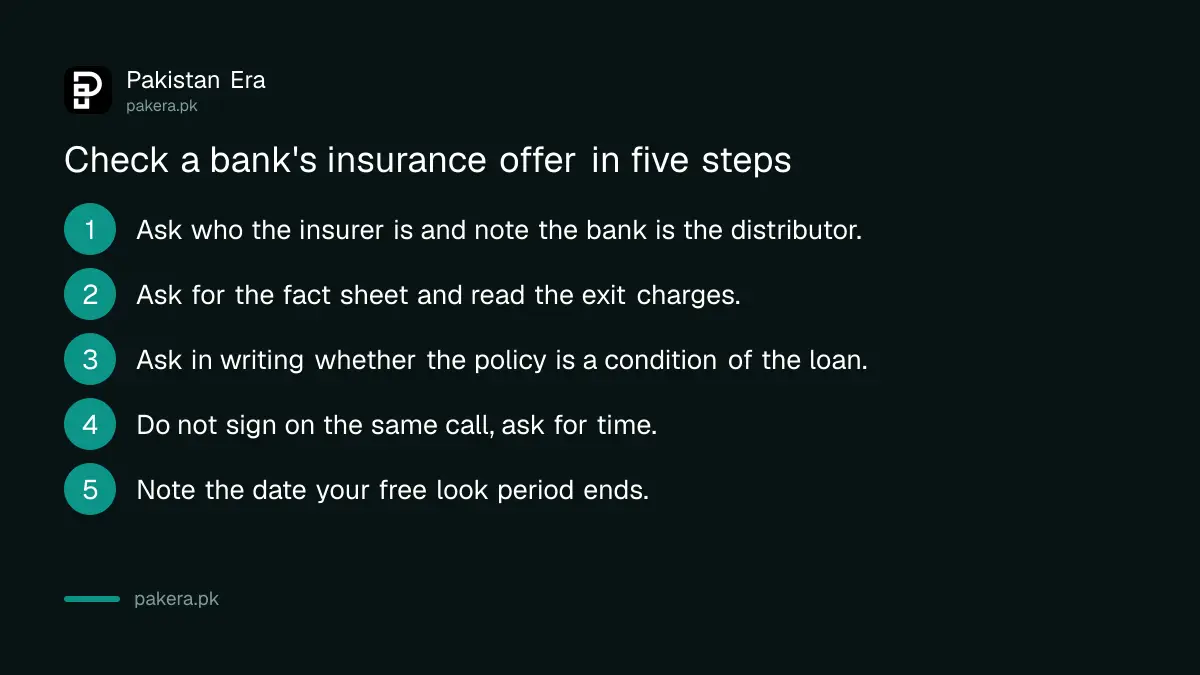
- Ask who the insurer is, and note that the bank is the distributor.
- Ask for the fact sheet and read the premium schedule and the early exit charges.
- Ask whether the policy is a condition of the account or loan. If it is, ask for that in writing.
- Do not sign on the same call. Ask for time and for the insurer's own documents.
- Keep the date of the call back and the date the free look period ends.
If a plan was already sold in a way that broke these rules, start with a written complaint to the bank. The bank must acknowledge it within 48 hours. A complaint that needs more than 7 working days is a major complaint, and it must be disposed of within 15 days, with 30 days for fraud cases. If the bank does not fix it, you can complain on the SBP Sunwai portal. If an insurer refuses a claim, you can complain to the insurance ombudsman.
Common questions
Can a bank force me to buy insurance with my loan?
The bank must state in the terms whether insurance is a condition or an option, and whether you can choose an insurer outside its panel. It cannot bundle a third party policy with an account or loan unless you ask for it.
How long do I have to cancel an insurance policy sold by a bank?
SBP's framework says 14 working days for bancassurance and bancatakaful, in line with SECP regulations. Other third party products get at least 7 working days. Act in the first week.
Can a bank sell me a policy on a phone call?
Not on one call alone. The framework bars a bank from marketing and closing the sale of a third party product on the same call. A separate call back must confirm your understanding.
Does a bank have to tell me it is not the insurer?
Yes. The bank must say it is selling as an agent or distributor of a third party. The fact sheet must carry a disclaimer to that effect.
Who can I complain to if the bank mis-sold me a policy?
Start with the bank, in writing. Then you can escalate to SBP through its Sunwai portal. The fact sheet must also name the Federal Insurance Ombudsman for grievances about the product.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on 12 October 2026. We read sections 2.3, 3.1.1, 3.1.2, 3.2.3, 3.2.4, 3.2.5 and 5.1.1 of the SBP Business Conduct and Fair Treatment of Consumers Regulatory Framework. We did not test any bank's actual practice, so a branch may not follow these rules. The 14 working day free look figure is the SBP text. The SECP regulation itself is cited through our earlier page and not read again here. Check your bank's current terms before you sign.
About the author
Global Affairs & Political Economy Writer
Muhammad Hatim is a book lover who started writing because he enjoys it. At Pakistan Era he writes about international relations, geopolitics and the global economy, with a particular interest in South Asia and the forces behind current events.