Check If Your Bank Deposit Is Protected in Pakistan: Rs 1 Million per Bank
If your bank fails, DPC repays up to Rs 1 million per depositor per bank within 30 days. Check if your bank and accounts are covered, and what is left out.
If a bank in Pakistan fails, the Deposit Protection Corporation (DPC) pays each eligible depositor up to Rs 1,000,000 per bank. You do not apply for it. Every scheduled bank is a member, and payment is due within 30 days at the latest. Anything above Rs 1 million in one bank is not covered by DPC.
Is my money safe if my bank fails? For most savers, yes. DPC says its October 2024 increase fully protects around 96 per cent of eligible depositors.
We read DPC's question and answer page, its member list dated 30 March 2026 and its 2024-25 annual report on 3 October 2026. Here is how to check your own deposit protection in Pakistan.
DPC protects up to Rs 1 million per depositor in each bank
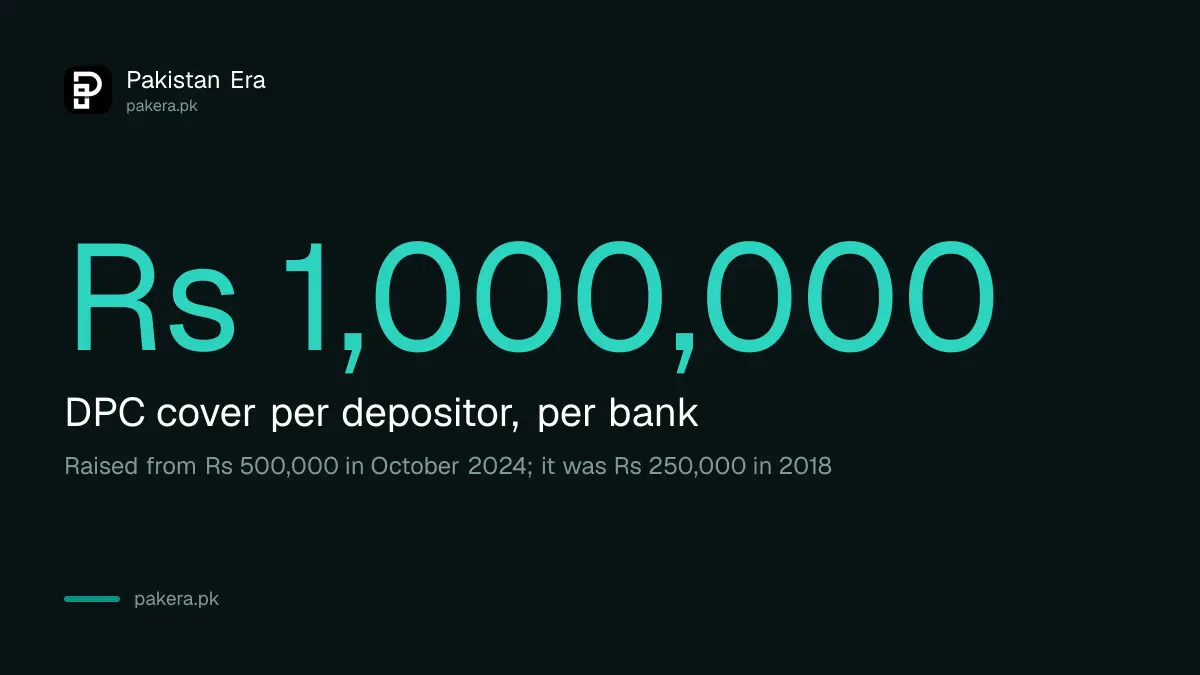
The protected amount is Rs 1,000,000 per depositor, per bank. It covers all your accounts in that bank added together, including profit earned up to the failure date. It is paid in Pakistani rupees, and banks cannot charge you for this protection.
DPC is a subsidiary of the State Bank of Pakistan (SBP), set up under the Deposit Protection Corporation Act, 2016. The limit started at Rs 250,000 in June 2018, rose to Rs 500,000 in September 2021 and reached Rs 1,000,000 in October 2024.
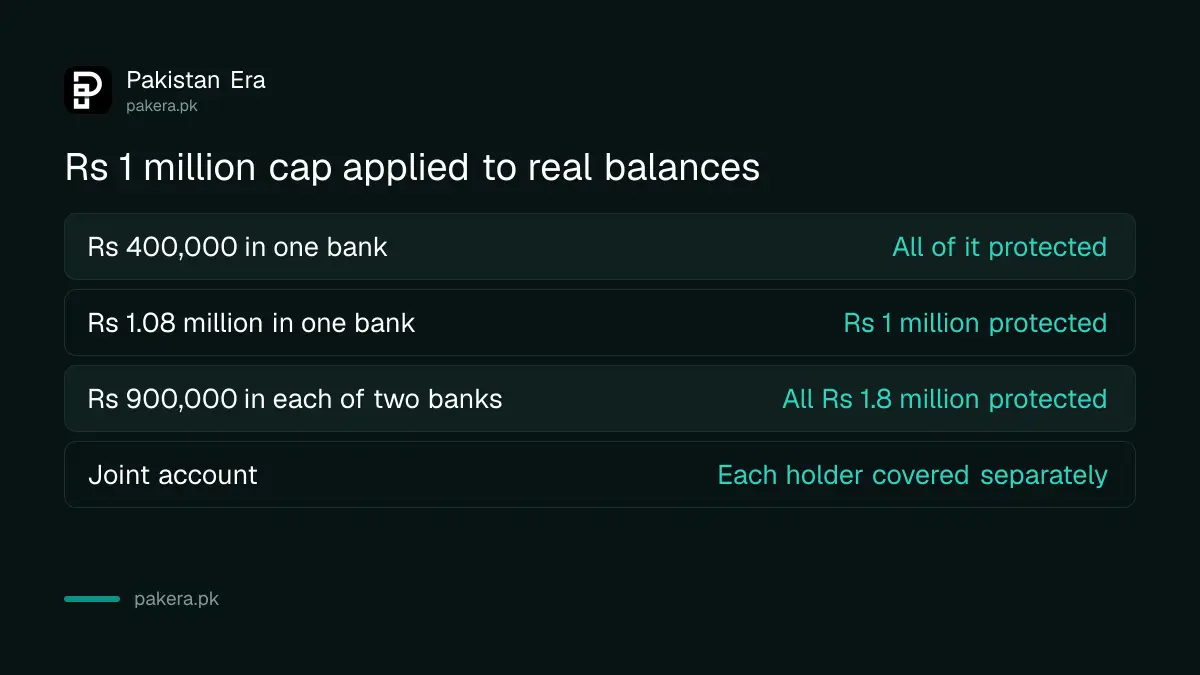
The key phrase is "per bank". If you hold Rs 1.5 million in one bank, Rs 500,000 of it sits outside DPC's cover. If you split it between two member banks, each one is covered up to Rs 1 million on its own.
DPC pays no profit after the failure date. You can still claim the part above Rs 1 million from the official liquidator, who sells the failed bank's assets, but that can take years and may not come back in full.
Every scheduled bank in Pakistan is a DPC member
You do not need to apply. All eligible depositors of member banks qualify automatically. DPC's list dated 30 March 2026 names 33 member banks: two specialised banks, 28 commercial banks and three digital banks. Check your bank's name on that list.
The list is attached to DPC Circular Letter No. 02 of 2026. It includes National Bank of Pakistan, HBL, UBL, MCB, Allied Bank, Bank Alfalah, Meezan Bank, The Bank of Punjab, Sindh Bank and The Bank of Khyber.
The three digital banks on the list are Easypaisa Bank, Mashreq Bank Pakistan and Raqami Islamic Digital Bank. Raqami joined on 30 March 2026, when SBP licensed it.
Microfinance banks are a different story. DPC's annual report says the amended Act allows them to be brought in, but no microfinance bank appears on the March 2026 list. If your wallet or savings account is with a microfinance bank, assume DPC does not cover it today.
| Type of bank | On DPC list, 30 March 2026 | Examples |
|---|---|---|
| Commercial banks | 28 | NBP, HBL, UBL, MCB, Meezan, Bank Alfalah |
| Specialised banks | 2 | Zarai Taraqiati Bank, Punjab Provincial Cooperative Bank |
| Digital banks | 3 | Easypaisa Bank, Mashreq Bank Pakistan, Raqami |
| Microfinance banks | 0 | Not on the list yet |
Which accounts are covered and which are left out
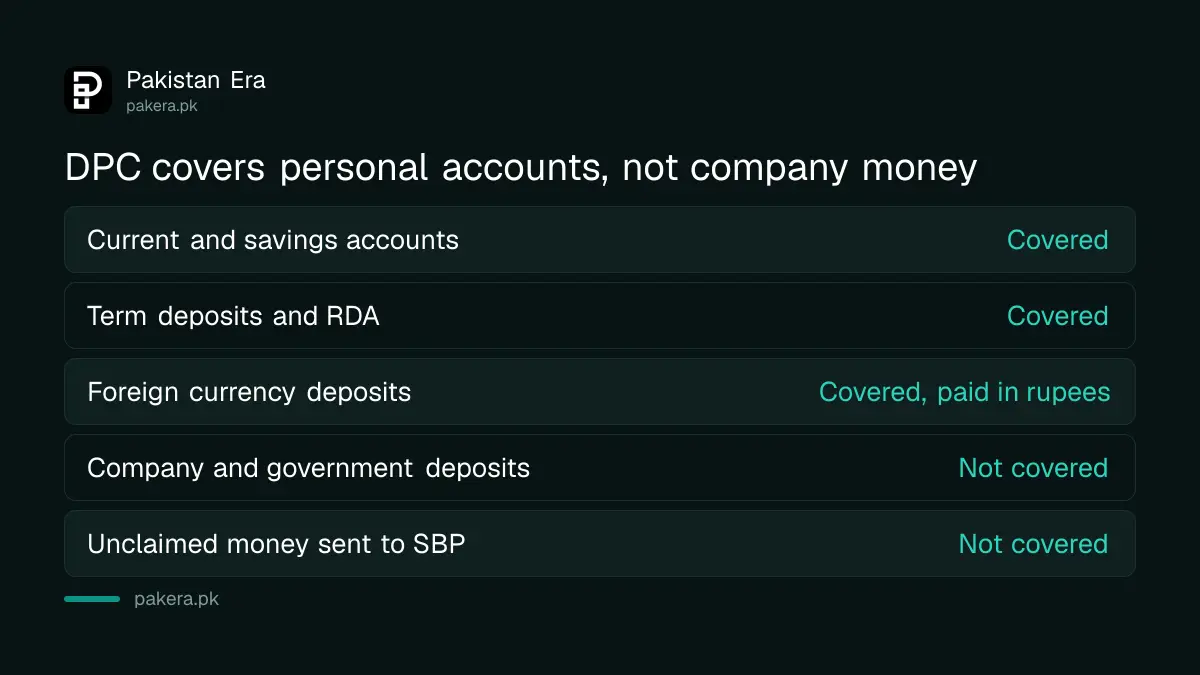
Current accounts, savings accounts, fixed deposits, Roshan Digital Accounts and branchless banking accounts are all covered. Foreign currency deposits are covered too, but paid back in rupees. Deposits of companies, government bodies and bank insiders are excluded.
DPC's FAQ lists the covered account types as:
- All current and savings accounts, including Roshan Digital Accounts.
- All types of branchless banking accounts held with a member bank.
- Fixed term deposits, call deposit receipts and security deposit receipts.
- Cash margins or money held under lien, after your dues to the bank are settled.
- Foreign currency deposits, converted to rupees at the rate SBP declares for the purpose.
- Profit on all of the above, up to the cut-off date.
Companies, corporations, modarabas, mutual funds, government and autonomous bodies, diplomatic missions and international organisations are excluded. So are a member bank's directors, senior managers and auditors, their close dependants, and deposits that earned a preferential rate.
Watch two quieter exclusions. Money a bank has already handed to SBP as unclaimed deposits is not covered by DPC. Neither are accounts at overseas branches of Pakistani banks, or at branches in Export Processing Zones.
Check your own deposit protection in five steps
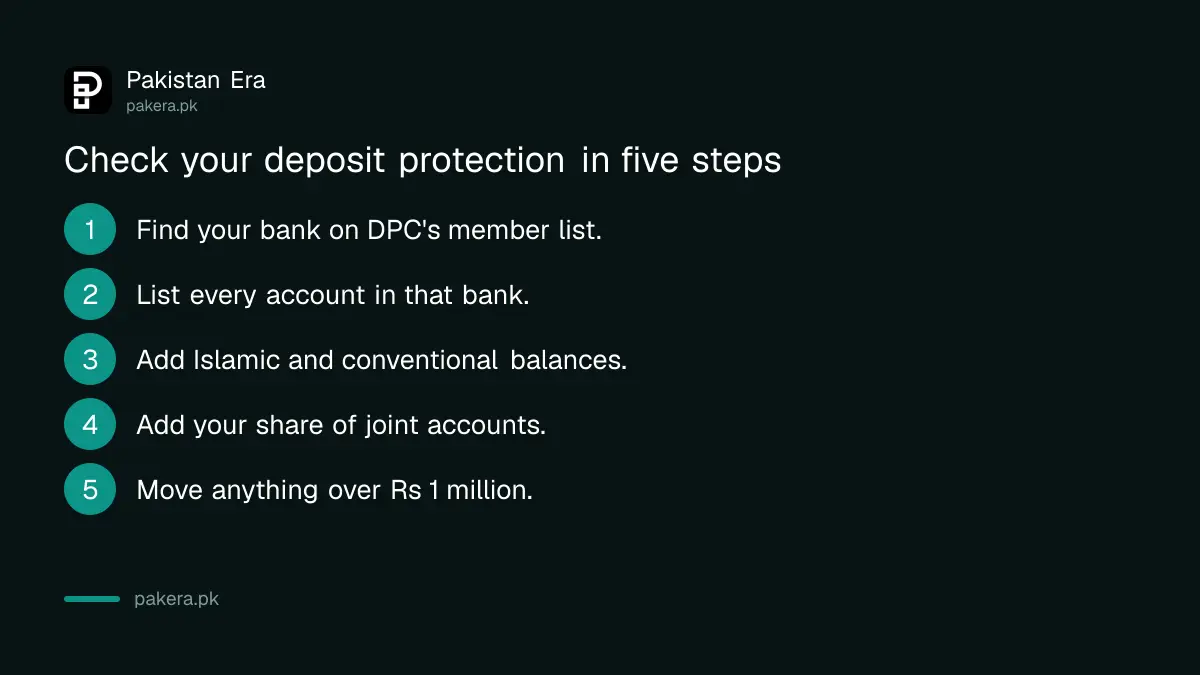
Confirm your bank is on DPC's list, then add up every balance you hold in that bank. Count conventional and Islamic accounts together, and include your share of joint accounts. If the total is above Rs 1 million, the extra is not protected.
- Open DPC's latest member list and find your bank's exact name.
- List every account you hold in that bank: current, savings, term deposits and any wallet the bank runs.
- Add the balances. Conventional and Islamic accounts in the same bank count as one pot, with one Rs 1 million limit.
- Add your share of any joint account. Each joint holder is protected separately, but your share joins your other balances in that bank.
- If the total is above Rs 1 million, decide whether to move the extra to a second member bank.
One trap catches small business owners. An account you hold as a sole proprietor counts with your personal accounts in the same bank. DPC's own example adds Rs 400,000 in a personal account and Rs 680,000 in a sole proprietor account, a total of Rs 1,080,000, and protects only Rs 1,000,000.
If you are opening a fresh account to spread your savings, any of the steps to open a bank account at a second member bank will do.
What happens if your bank fails
SBP first declares the bank failed. DPC then announces the payment date and method in national newspapers. It aims to pay most protected depositors within seven working days, and all of them within 30 days, unless a legal dispute affects an account.
DPC works from the failed bank's depositor records, so your balance on the failure date is what counts. A cheque still in transit that day is settled later, in the liquidation.
This has already happened once. SBP notified SME Bank Limited as a failed institution on 10 May 2023, effective from 27 March 2023. DPC's annual report records Rs 310.6 million owed to its eligible depositors, of which Rs 290.5 million had been paid by 31 March 2025.
If the depositor has died, the legal heirs can claim. DPC says they must prove their right with the documents the law requires, which usually means a succession certificate from NADRA or a court. If two member banks merge, each deposit stays separately protected for one year, or until full withdrawal or maturity, whichever comes first.
Common questions
How much of my bank deposit is protected in Pakistan?
Up to Rs 1,000,000 per depositor, per bank, including profit up to the failure date. DPC set this limit in October 2024, up from Rs 500,000.
Do I need to register with DPC?
No. Every eligible depositor of a member bank is covered automatically. There is no form, fee or certificate.
Are Islamic bank accounts covered by DPC?
Yes. Meezan Bank, BankIslami, Dubai Islamic Bank Pakistan, Albaraka and MCB Islamic are all members. Your Islamic and conventional deposits in the same bank share one Rs 1 million limit.
Is my JazzCash or Easypaisa wallet protected?
It depends on who runs it. Easypaisa Bank is on DPC's list as a digital bank. No microfinance bank is on the March 2026 list, so check which bank holds your wallet before you rely on DPC.
Are National Savings certificates covered by DPC?
No. They are not bank deposits. They are government savings schemes run by the Central Directorate of National Savings, so DPC's cover does not apply to them.
Can I get more than Rs 1 million if I have accounts in different banks?
Yes. The limit applies separately in each member bank. Rs 900,000 in each of two member banks is fully protected.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on 3 October 2026. The Rs 1,000,000 limit per depositor per bank, the covered account types, the exclusions, the joint account and sole proprietor rules, the seven working day and 30 day payment targets, the merger rule and the heirs' right to claim are read on DPC's FAQs for depositors. The list of 33 member banks and Raqami's membership from 30 March 2026 are read in DPC Circular Letter No. 02 of 2026, and digital bank membership in DPC Circular No. 01 of 2025. The history of the limit, the 96 per cent figure, the SME Bank failure figures and the note on microfinance banks are read in DPC's Annual Report 2024-25. We did not contact DPC.
About the author
Tax, Bills and Technology Writer
Ali Akhtar is a young and curious voice here at Pakistan Era. He is currently pursuing his A-Levels and has a growing interest in Pakistan’s changing industrial landscape and educational trends. Ali likes to write in a way that helps him explain and explore the world around him. His writing reflects the perspective of the new generation navigating the evolving trends of Pakistan where technology, youth innovation, and shifting opportunities are reshaping the country’s future.