FBR Faceless Audit and Assessment Rules Now in Force for Every Case From 15 October 2026
SRO 1828 and SRO 1825 of 15 October 2026 bring FBR faceless audit and assessment rules into force for every income tax and sales tax case. See what changes now.
Short answer: FBR's faceless audit and assessment rules are in force. S.R.O. 1828(I)/2026, dated 15 October 2026, brings Chapter XX of the Income Tax Rules, 2002 into effect "for every person or case" from 15 October 2026. A second notification of the same date, S.R.O. 1825(I)/2026, starts the matching sales tax chapter, Chapter VIAC of the Sales Tax Rules, 2006, for all persons or cases from the same day.
This closes the gap we reported last week. The rules themselves were notified on 29 September, but they said they would start only on a date FBR would announce. That date is now fixed, and it has already passed. We read both notifications on the FBR website on 19 October 2026.
Two notifications of 15 October start the faceless regime
S.R.O. 1828(I)/2026 uses the power in sub-rule (2) of rule 233 of the Income Tax Rules. It says Chapter XX "shall come into force, for every person or case, with effect from the 15th day of October, 2026". S.R.O. 1825(I)/2026 does the same for Chapter VIAC of the Sales Tax Rules, from the same date.
Both are one-page notifications. Neither names a class of cases or a list of taxpayers. The income tax one is signed by the IR-Policy Wing; the sales tax one cites section 50 of the Sales Tax Act, 1990 and section 40 of the Federal Excise Act, 2005, so it covers federal excise proceedings too.
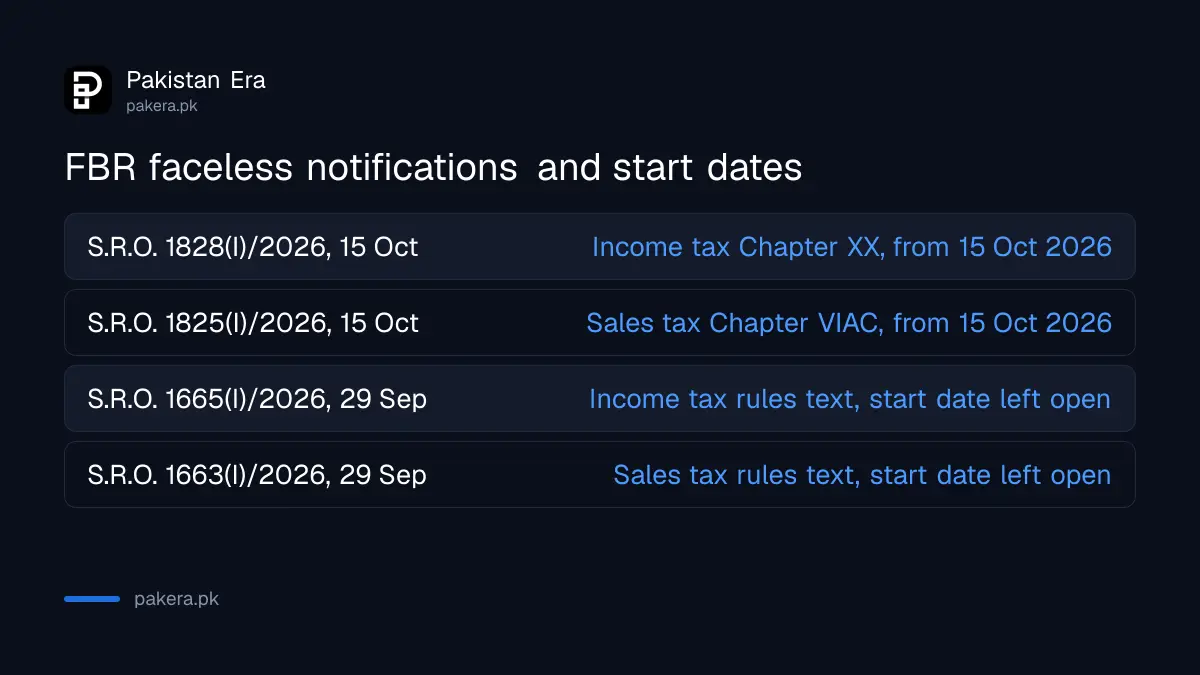
| Notification | Date | What it starts | From |
|---|---|---|---|
| S.R.O. 1828(I)/2026 | 15 October 2026 | Chapter XX, Income Tax Rules, 2002 (rules 233 to 245) | 15 October 2026, every person or case |
| S.R.O. 1825(I)/2026 | 15 October 2026 | Chapter VIAC, Sales Tax Rules, 2006 (rule 441 onwards) | 15 October 2026, all persons or cases |
| S.R.O. 1665(I)/2026 | 29 September 2026 | The income tax rules themselves | Start date left to a later notification |
| S.R.O. 1663(I)/2026 | 29 September 2026 | The sales tax rules themselves | Start date left to a later notification |
Audits, section 111 cases and assessments now run through the National Faceless Centre
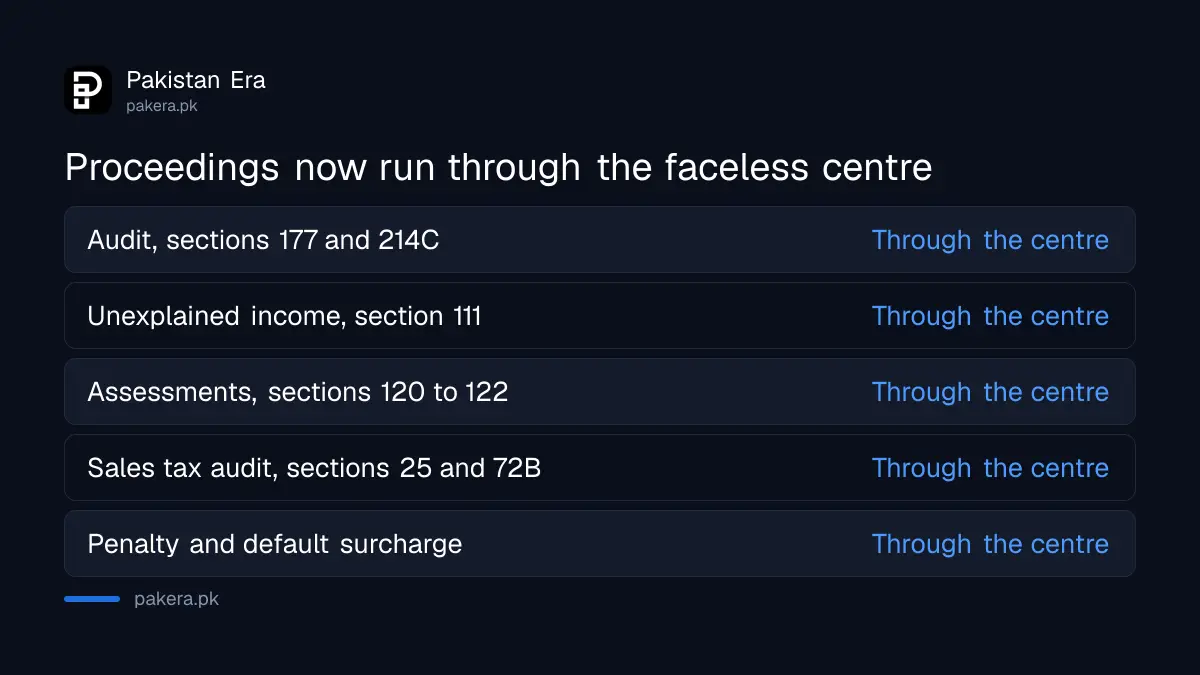
Rule 236 of Chapter XX lists what the centre handles: audits under section 177 or 214C, proceedings and orders under section 111 on unexplained income, and assessments, amended assessments, best judgment and provisional assessments under sections 120, 121 and 122. Any notice under sections 176 or 177, and any penalty or default surcharge arising from those proceedings, goes through the centre as well.
On the sales tax side, the new Chapter VIAC covers audit under section 25 or section 72B of the Sales Tax Act, proceedings under section 11E, and the notices, penalties and default surcharge that come with them.
The practical change is who you deal with. Under rule 237 an allocation algorithm assigns the audit, the assessment and the quality check of one case to different officers, and no officer may perform more than one of those jobs for the same case and tax year. You are not told who they are.
Every notice must carry a DIN and every reply goes through IRIS
Rule 238 says every notice, order or communication from the centre must be generated on FBR's computerised system and bear a Digital Identification Number, a DIN. Rule 239 says every reply, submission, document or evidence from the taxpayer or a representative must be sent through the "designated account", which rule 234 defines as the taxpayer's account on IRIS.
Hearings are electronic hearings under section 227E. A statement on oath under section 176 can be recorded through an e-hearing. The audit unit can still ask the Chief Commissioner for a physical verification of a business, its assets or its stock under rule 241, and the quality control wing reviews audit reports and assessment orders under rule 242.
A paper notice without a DIN, or a request to meet an officer in person, does not fit these rules. The steps to check whether an FBR notice is real start with that number.
What is still open after the start notification
Rule 233(1) says the chapter applies to proceedings in respect of persons, classes or cases "specified by the Board" under section 122E(2). The start notification covers "every person or case", but we found no separate order on the FBR website naming which cases are assigned to the centre or how a case already open with a local office is treated. Rule 244 lets the Chief Commissioner move a case back to the local Commissioner where the record is large or a search or seizure is involved.
Business reporting on 17 October described the system as implemented from 15 October with the help of artificial intelligence. FBR's notifications do not mention artificial intelligence; the rules speak of an allocation algorithm. We have not seen FBR say how many cases have been assigned so far.
What a taxpayer should do now
A notice under these rules can arrive in your IRIS inbox and by email, and the reply deadline runs from service. If you have an open audit, a section 111 query or an amended assessment, assume the next step comes through the centre.
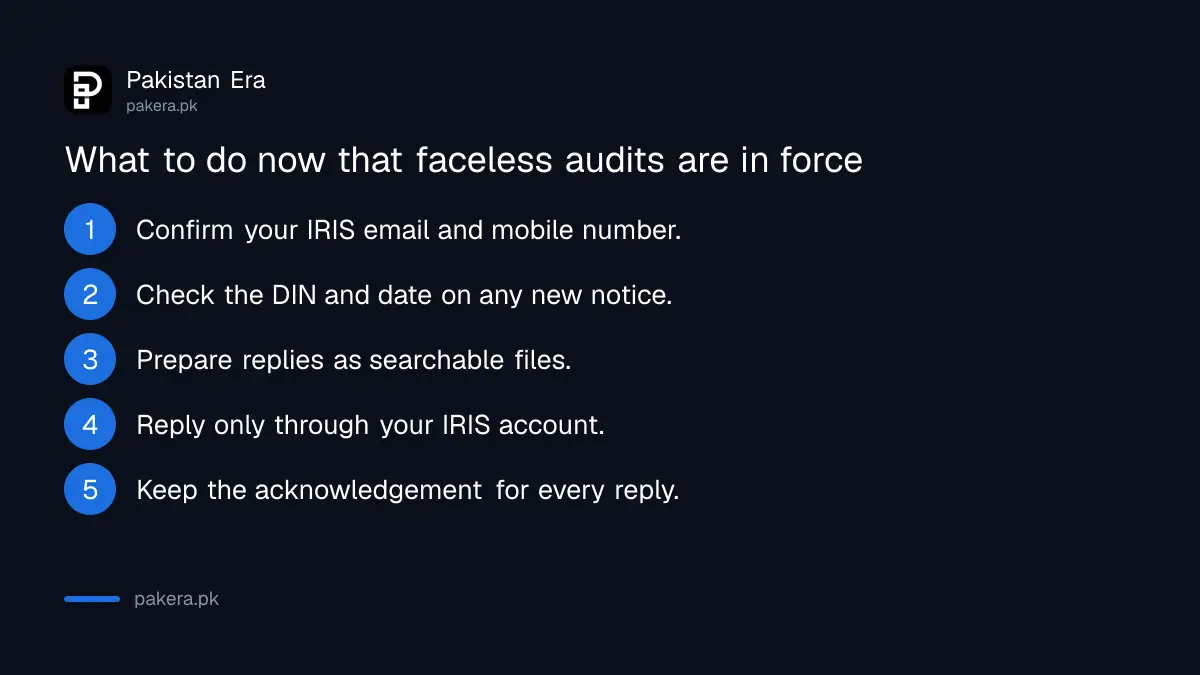
- Log in to IRIS and confirm the email address and mobile number on your profile are current, using Form 181 to change your IRIS contact details if they are not.
- Open any new notice and check the DIN, the date and the section it cites before you read the demand.
- Note the deadline and prepare your reply as searchable files, not photographs of pages.
- Reply only through your IRIS account and download the acknowledgement.
- If the notice is an audit, gather the records listed in our guide to replying to a section 177 audit notice.
The same 15 October batch included S.R.O. 1827(I)/2026, which rewrites rule 231C on alternative dispute resolution, and S.R.O. 1829(I)/2026 on a minimum value for re-meltable scrap supplied to steel melters. Those are separate from the faceless rules.
Common questions
Are FBR faceless audits in force now?
Yes. S.R.O. 1828(I)/2026 brings Chapter XX of the Income Tax Rules into force for every person or case from 15 October 2026. The sales tax chapter starts the same day under S.R.O. 1825(I)/2026.
Does this apply to sales tax audits too?
Yes. Chapter VIAC of the Sales Tax Rules covers audit under sections 25 and 72B of the Sales Tax Act and proceedings under section 11E. The notification also cites the Federal Excise Act.
Can I still visit my tax office to reply?
Not for a case assigned to the centre. Rule 239 requires replies through your IRIS account, and hearings are electronic under section 227E.
Will I know which officer is handling my case?
No. The allocation algorithm assigns separate officers for audit, assessment and quality review, and their identity is kept confidential.
What if my audit started before 15 October?
The notifications do not say. Rule 233(1) ties the chapter to cases specified by the Board, and we found no transition order on the FBR website on 19 October 2026.
Does a notice need a DIN?
Yes. Rule 238 requires every notice, order and communication from the centre to carry a Digital Identification Number.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 19 October 2026. We read S.R.O. 1828(I)/2026 and S.R.O. 1825(I)/2026, both dated 15 October 2026, as PDFs linked from the FBR home page, and S.R.O. 1665(I)/2026 and S.R.O. 1663(I)/2026 of 29 September 2026 for the text of the rules, all on the FBR SRO pages. We could not find any order listing the cases assigned to the centre or any transition rule for audits already open, and we could not verify the reported use of artificial intelligence, which the notifications do not mention.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.