FBR S.R.O. 2062: Faceless Unit Can Now Pass Income Tax Assessments, Replies Only Through IRIS
FBR's SRO 2062 of 5 November 2026 makes faceless income tax assessment final. What the unit can do, how to reply on IRIS, and the e-hearing rule explained.
FBR's S.R.O. 2062(I)/2026, dated 5 November 2026, makes final the rules for faceless income tax assessment. A Faceless Assessment Unit, not your local tax office, can now pass assessment orders after an audit or on definite information, fix mistakes in its own orders and impose penalties. You must send every reply, document and piece of evidence through your IRIS account, and any hearing is an online e-hearing.
The change matters if you get an income tax notice that was raised by a computer, not by an officer you know. We read the final notification on FBR's SRO list on 11 November 2026, together with the draft it confirms, S.R.O. 1905(I)/2026 of 26 October 2026. Below is what the rules now say, what to do when a faceless notice arrives, and what we could not confirm.
What S.R.O. 2062 changes in the Income Tax Rules
S.R.O. 2062 amends Chapter XX of the Income Tax Rules 2002, the chapter on faceless audit and assessment. It was issued under section 122E and section 237 of the Income Tax Ordinance 2001. It makes six changes.
| Rule | What S.R.O. 2062 does |
|---|---|
| Rule 233(1) | Extends the faceless rules to every other function given to the faceless centre by law or by the Board |
| Rule 237(3) | Replaces "FBR" with "the Board" (a wording fix) |
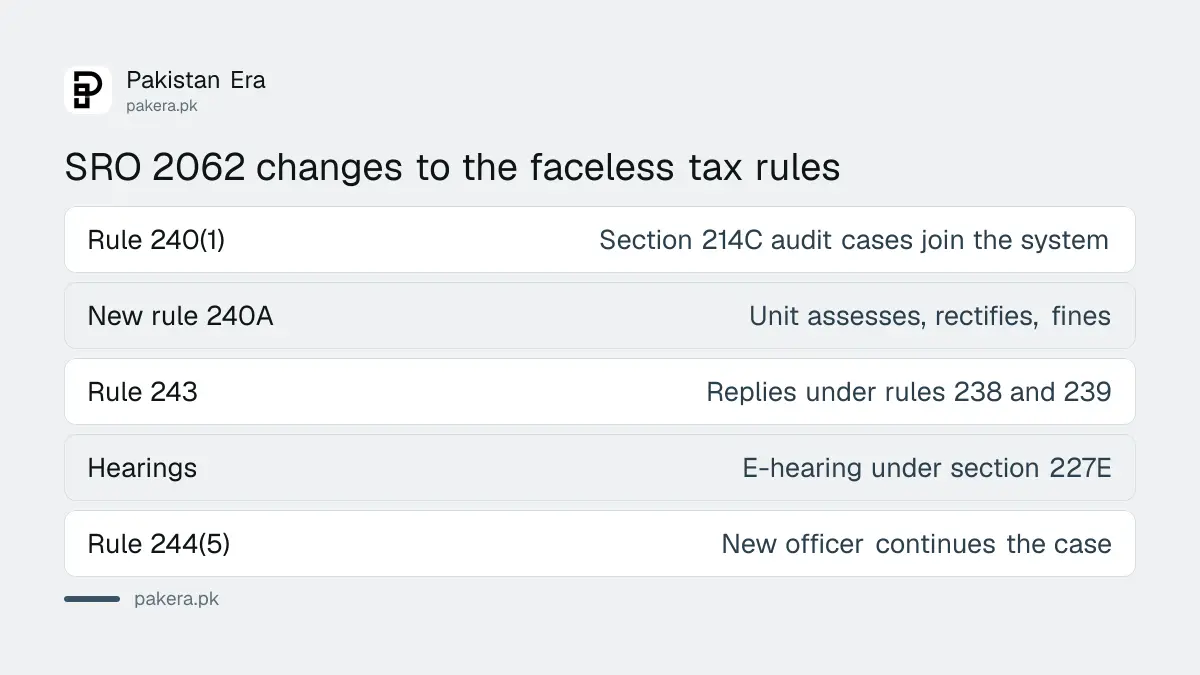
| Rule 240(1) | Adds cases selected for audit under section 214C to the faceless system, and omits clause (b) |
| New rule 240A | Lists what the Faceless Assessment Unit does and how it works |
| Rule 243 | Applies rules 238 and 239 to notices and replies, with hearings by e-hearing under section 227E |
| Rule 244 | Lets a new officer continue a case from where the previous officer left it |
Section 214C is the provision under which the Board selects returns for audit. So a return picked for audit can now go through the faceless system from audit to assessment.
What the Faceless Assessment Unit can do
New rule 240A sets out the unit's work. It can pass assessments based on an audit or on definite information. It can rectify a mistake that is apparent from the record in an order it passed. It can issue notices under section 176 to obtain information and evidence. It can impose a penalty or default surcharge that arises from the case.
When a case reaches a unit through automated allocation, the unit officer must:
- Examine the record, any order under section 111 and the audit report, under the law and facts of the case.
- Issue a notice to the taxpayer under the relevant section, giving a chance to be heard.
- Receive the taxpayer's replies, documents and evidence only through the designated IRIS account, under rule 239.
During the case, the officer may ask a specialist unit or panel for technical help, such as valuation, forensic or sector expertise. The officer may also ask for physical verification under rule 241 and hold an e-hearing under section 227E.
How to reply to a faceless income tax notice
Reply on IRIS, before the date in the notice, and keep proof of what you sent. The rules do not provide for a reply by hand at a tax office. Follow these steps.
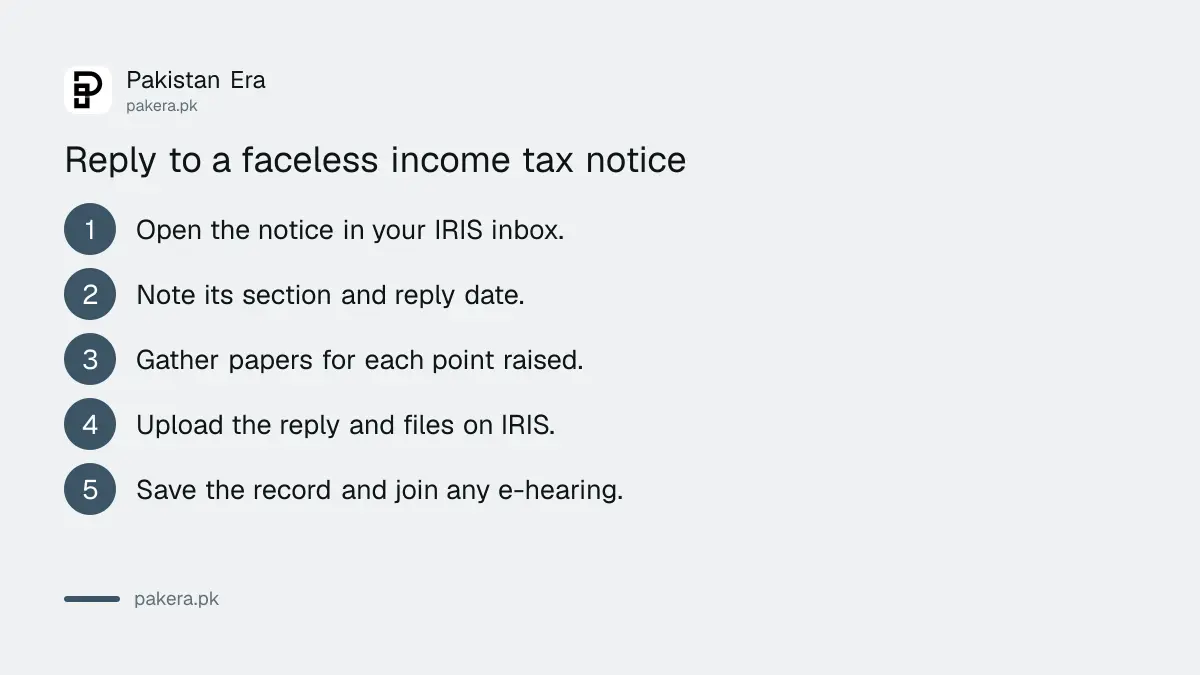
- Log in to IRIS and open the notice in your inbox. Note its section, its date and the reply date.
- Read what the notice asks for. A section 176 notice asks for information or documents. A notice before an assessment asks you to explain a point.
- Gather bank statements, sale deeds, invoices or other papers that answer each point.
- Upload the reply and every document against that notice on IRIS. Do not email them.
- Save or print the submission record IRIS shows once the reply is filed.
- If you are offered an e-hearing, join it at the given time. Take your papers and your tax adviser if you have one.
If you cannot meet the date, contact the unit through IRIS before it passes rather than after. Our guide on replying to a faceless sales tax assessment covers the same steps for sales tax.
How S.R.O. 2062 fits with the earlier faceless rules
FBR built the faceless system in stages during 2026. The audit rules came first, then assessment for sales tax and income tax.
| Notification | Date | What it did |
|---|---|---|
| S.R.O. 1665(I)/2026 | 29 September 2026 | Final rules for faceless audit and assessment |
| S.R.O. 1828(I)/2026 | 15 October 2026 | Brought the faceless system into force under rule 233(2) |
| S.R.O. 1905(I)/2026 | 26 October 2026 | Draft amendments to Chapter XX, for comments |
| S.R.O. 2062(I)/2026 | 5 November 2026 | Final income tax amendments, this notification |
| S.R.O. 2085(I)/2026 | 5 November 2026 | Matching sales tax amendments |
For the earlier steps, see faceless audit and assessment in force from 15 October 2026 and how FBR set up its national faceless centre.
What a change of officer means for your case
New sub-rule (5) of rule 244 says that when one income tax authority is succeeded by another, the new one may continue the case from the stage it was left. So a case does not start again just because the officer changed. Keep your replies complete, because the next officer reads the same file.
What we could not confirm
S.R.O. 2062 refers to rules 238, 239 and 241, which we did not re-read today, so we do not quote their time limits. It omits clause (b) of rule 240(1) without saying what that clause covered, and we have not checked the earlier text. The notification has no separate start date. FBR's own SRO list gives it the date 5 November 2026.
Common questions
What is S.R.O. 2062 of 2026?
It is FBR's final notification of 5 November 2026 amending the faceless assessment chapter of the Income Tax Rules 2002.
Can I reply to a faceless notice at my tax office?
The rules say replies, documents and evidence go through your designated IRIS account under rule 239. Use IRIS.
Will I meet the officer in person?
The rules provide for an e-hearing under section 227E. The officer can also ask for physical verification of a place or record under rule 241.
Can the faceless unit fine me?
Yes. Rule 240A lets it impose a penalty or default surcharge that arises from the assessment case.
Does a new officer restart my case?
No. Under the new rule 244(5), the new officer may continue from the stage the previous officer left it.
Is S.R.O. 2062 a draft?
No. It is final. It says the draft was published as S.R.O. 1905 of 26 October 2026, as section 237(3) requires.
Last checked: 11 November 2026, from S.R.O. 2062(I)/2026 on FBR's Income Tax SRO list at fbr.gov.pk.
About the author
Tax, Bills and Technology Writer
Ali Akhtar is a young and curious voice here at Pakistan Era. He is currently pursuing his A-Levels and has a growing interest in Pakistan’s changing industrial landscape and educational trends. Ali likes to write in a way that helps him explain and explore the world around him. His writing reflects the perspective of the new generation navigating the evolving trends of Pakistan where technology, youth innovation, and shifting opportunities are reshaping the country’s future.