HBFC Home Loan Charges in Pakistan, July to December 2026: Rs 5,000 Approval, Rs 10,000 Processing
HBFC's July to December 2026 charges: Rs 5,000 prior approval, Rs 10,000 processing up to Rs 30 million, 5% early settlement. See the documents and products.
An HBFC home loan in Pakistan costs Rs 5,000 for prior approval if you live in Pakistan, then a one-time processing fee of Rs 10,000 for loans up to Rs 30 million, plus legal, income and property checks, on HBFC's schedule of charges for 1 July to 31 December 2026. Salaried applicants need four salary slips, a salary certificate and a bank statement.
House Building Finance Company (HBFC) is the state-owned lender that only does housing loans. We read its schedule of charges page, the July to December 2026 PDF linked from it, and its loan application requirements on 20 October 2026. All amounts below are from those pages unless we say they are our own sums.
HBFC's fees before the loan come to Rs 22,500 to Rs 24,500 for a salaried buyer of a house
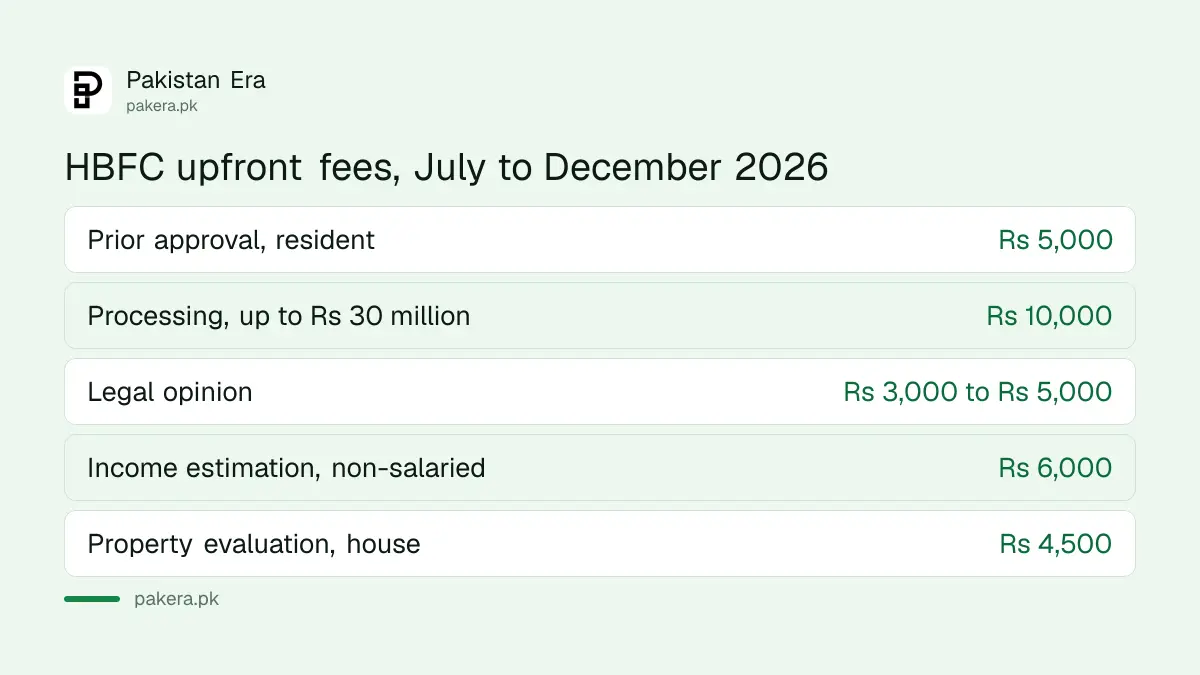
The upfront fees are prior approval, one-time processing, legal opinion and property evaluation. For a resident, salaried buyer of a house with a loan under Rs 30 million, that is Rs 5,000, Rs 10,000, Rs 3,000 or Rs 5,000, and Rs 4,500. Our total is Rs 22,500 to Rs 24,500, before mortgage documentation.
| Charge, July to December 2026 | Amount |
|---|---|
| Prior approval fee, resident Pakistani | Rs 5,000 |
| Prior approval fee, non-resident Pakistani | Rs 10,000 |
| One-time processing fee, loan up to Rs 30 million | Rs 10,000 |
| One-time processing fee, loan above Rs 30 million | Rs 25,000 |
| Legal opinion | South Rs 5,000; Central and North Rs 3,000 |
| Income estimation, non-salaried only | Rs 6,000 |
| Property evaluation | Flat Rs 4,000; house Rs 4,500; tranche Rs 2,000 |
| Out-station charge, each of the two checks | Rs 1,000 up to 25 km, rising to Rs 5,000 above 100 km |
| Mortgage documentation | As per actual |
The legal opinion fee is Rs 5,000 in HBFC's South region and Rs 3,000 in Central and North. HBFC's sheet does not say which cities fall in each region, so ask your branch. A self-employed buyer adds Rs 6,000 for income estimation, which takes the top of the range to Rs 30,500. A property far from the branch adds out-station charges on both the income and the property check.
Charges after you borrow: missed payments, early settlement and balloon payments
HBFC charges Rs 2,500 for each missed instalment. Settling early costs 5 per cent of the principal outstanding, at any point in the loan. A balloon payment, which must be at least 10 per cent of the principal outstanding, costs 5 per cent of the amount paid.
So paying off Rs 2 million of a loan early would cost Rs 100,000 by our arithmetic. That changes the sums if you plan to sell the house in a few years. HBFC's sheet adds that processing fees, balloon and early settlement charges may not apply on certain products, so ask in writing whether your product is one of them.
Two charges come at the very end. A redemption deed, which releases your property from the mortgage, costs Rs 3,000. And if you do not collect your documents within 90 days of closing the account, HBFC charges Rs 500 a month for storage, capped at Rs 20,000.
Documents for a salaried applicant depend on whether the loan is above Rs 10 million
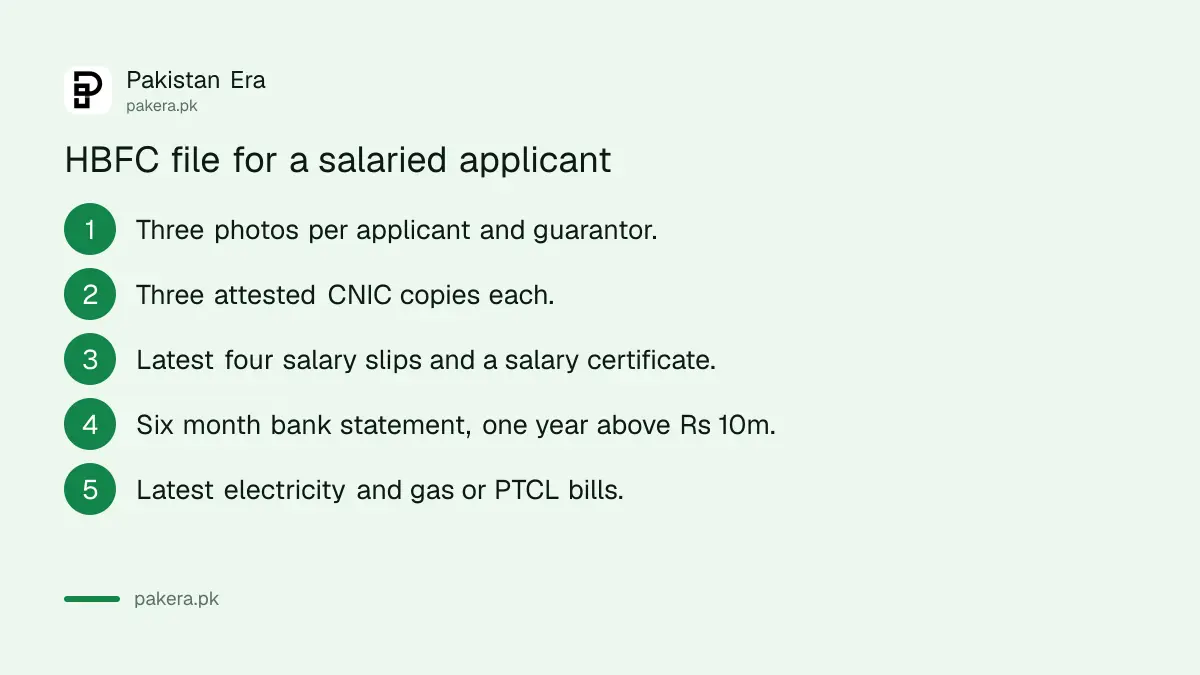
Up to Rs 10 million, a salaried applicant gives four original salary slips, an original salary certificate, a six month bank statement and copies of utility bills. Above Rs 10 million, the bank statement must cover one year. Everyone gives photos and attested CNIC copies.
- Three coloured passport photos each of the applicant, any co-applicant and any guarantor.
- Three attested copies, both sides, of each person's CNIC or NADRA token receipt.
- In a purchase, an attested copy of the seller's CNIC.
- Latest four month salary slips, original.
- Salary certificate with name, CNIC, joining date, gross and net income and terms of employment.
- Bank statement for six months, or one year above Rs 10 million.
- Copies of the latest electricity and gas or PTCL bills.
Self-employed people give a one year bank statement, two years above Rs 10 million, plus an affidavit declaring income on Rs 50 stamp paper attested by a notary. Rental and farm income have their own lists. A farm owner, for example, needs a Tehsildar or Mukhtiarkar ownership certificate and an ushr receipt.
HBFC's four home loan products differ on rate and size
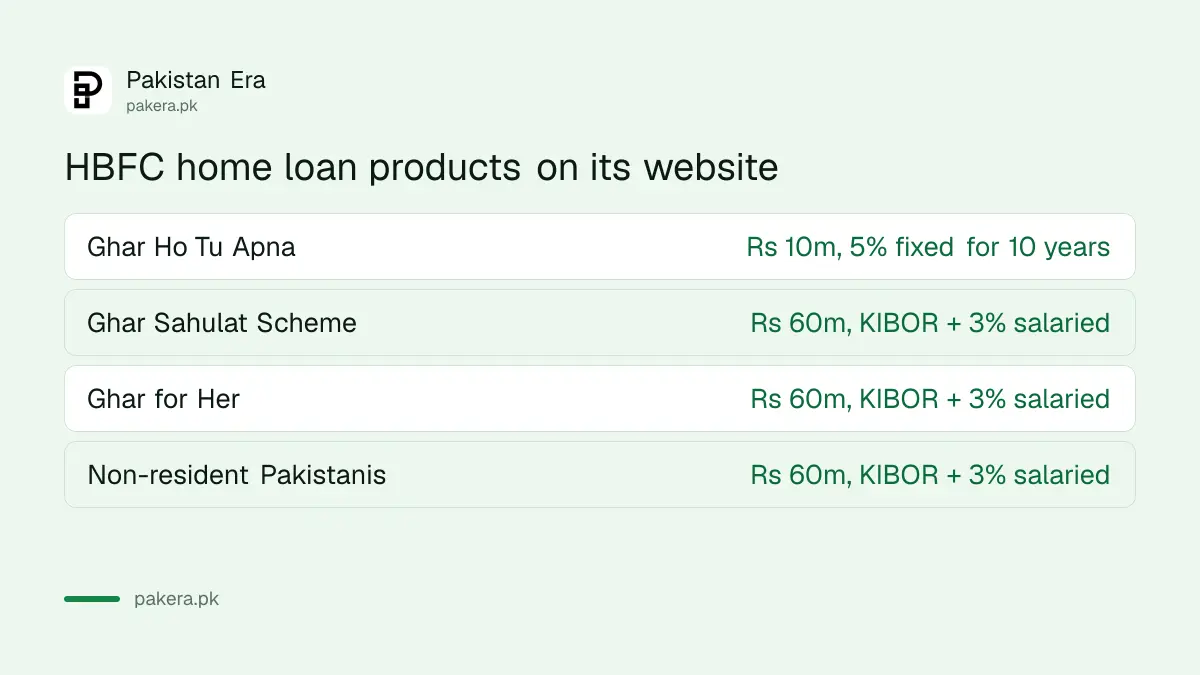
HBFC's product pages list Ghar Ho Tu Apna at 5 per cent fixed for 10 years on loans up to Rs 10 million, and its Ghar Sahulat Scheme, Ghar for Her and loans for overseas Pakistanis at 1 year KIBOR plus 3 per cent for salaried borrowers, up to Rs 60 million.
| Product | Up to | Rate on HBFC's page | HBFC's share |
|---|---|---|---|
| Ghar Ho Tu Apna | Rs 10 million | 5% fixed for 10 years, then KIBOR + 3% | Up to 90% |
| Ghar Sahulat Scheme | Rs 60 million | KIBOR + 3% salaried, + 3.5% self-employed | Up to 85% |
| Ghar for Her | Rs 60 million | KIBOR + 3% salaried, + 3.5% self-employed | Up to 85% |
| Non-resident Pakistanis | Rs 60 million, selected cities | KIBOR + 3% salaried | Up to 85% |
Ghar Ho Tu Apna needs a net disposable income of at least Rs 50,000 a month. Its 5 per cent rate matches the government-backed scheme described in what the 2026 SBP Apna Ghar circulars changed. KIBOR is the interbank rate that banks use as a base. HBFC takes the rate from the last working day of the previous month and resets it each year on the loan's anniversary, so the instalment on the other products will move.
Before you sign, ask for the full cost in writing. The SBP rules on what a lender must tell you about a loan offer apply to HBFC too.
HBFC promises a complaint reply in 7 to 15 working days
HBFC says it acknowledges a complaint within 48 hours, except call centre complaints, and resolves it within 7 to 15 working days. If more work is needed, it sends an interim reply after 10 working days. Fraud complaints get a final reply within 30 working days.
Call 0800-42325, email complaint@hbfc.com.pk, or write to the Head Service Quality Management Unit at the Finance and Trade Centre, Shahrah-e-Faisal, Karachi. Give your CNIC, account number and branch. If the reply does not satisfy you, HBFC names the State Bank's consumer protection department and the Banking Mohtasib as the next steps.
Common questions
What is the HBFC processing fee in 2026?
For July to December 2026 the one-time processing fee is Rs 10,000 for loans up to Rs 30 million and Rs 25,000 above that. Prior approval costs Rs 5,000 for residents and Rs 10,000 for non-residents.
Are HBFC fees refundable?
No. HBFC's schedule marks the prior approval fee and the one-time processing fee as non-refundable.
What does HBFC charge for paying off a loan early?
Five per cent of the principal outstanding, throughout the loan term. HBFC says this may not apply on some products.
What is the penalty for a missed HBFC instalment?
Rs 2,500 for each missed payment, on the July to December 2026 schedule.
How many salary slips does HBFC need?
The latest four months, in original, with a salary certificate and a bank statement of six months, or one year for loans above Rs 10 million.
What is HBFC's helpline?
HBFC's call centre number is 0800-42325. Complaints can also go to complaint@hbfc.com.pk.
How we verified this
What we checked, where we read it, and what we could not confirm.
We read HBFC's schedule of charges for 1 July to 31 December 2026, its loan application requirements, the Ghar Ho Tu Apna, Ghar Sahulat Scheme, Ghar for Her and non-resident product pages, and its complaint process page on 20 October 2026. Totals and the early settlement example are our arithmetic. HBFC does not say which cities count as South, Central or North for legal opinion fees, or what mortgage documentation costs in practice, so we could not verify those.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.