Check Your Bank Loan Offer in Pakistan: 8 Things SBP Says the Bank Must Tell You
SBP guidelines say a bank must disclose eight things with a loan offer, from the mark-up basis to set-off. Use our checklist and the 30 day notice rule first.
When you apply for a bank loan or overdraft in Pakistan, the State Bank's conduct guidelines say the bank must give you eight things: the mark-up rate, how it is set, all fees, how long the offer stays open, repayment terms, any right to demand repayment at once, key features such as late and early repayment charges, and its right to set off your other balances.
Most borrowers look at one number, the monthly instalment. The offer letter holds seven more, and any of them can cost you money later. We read the State Bank of Pakistan's (SBP) Guidelines of Business Conduct for Banks on 15 October 2026. The version on SBP's site cites circulars up to 2015, and we found no newer replacement.
Section 4.9.2 lists eight items the bank must give you with a loan offer
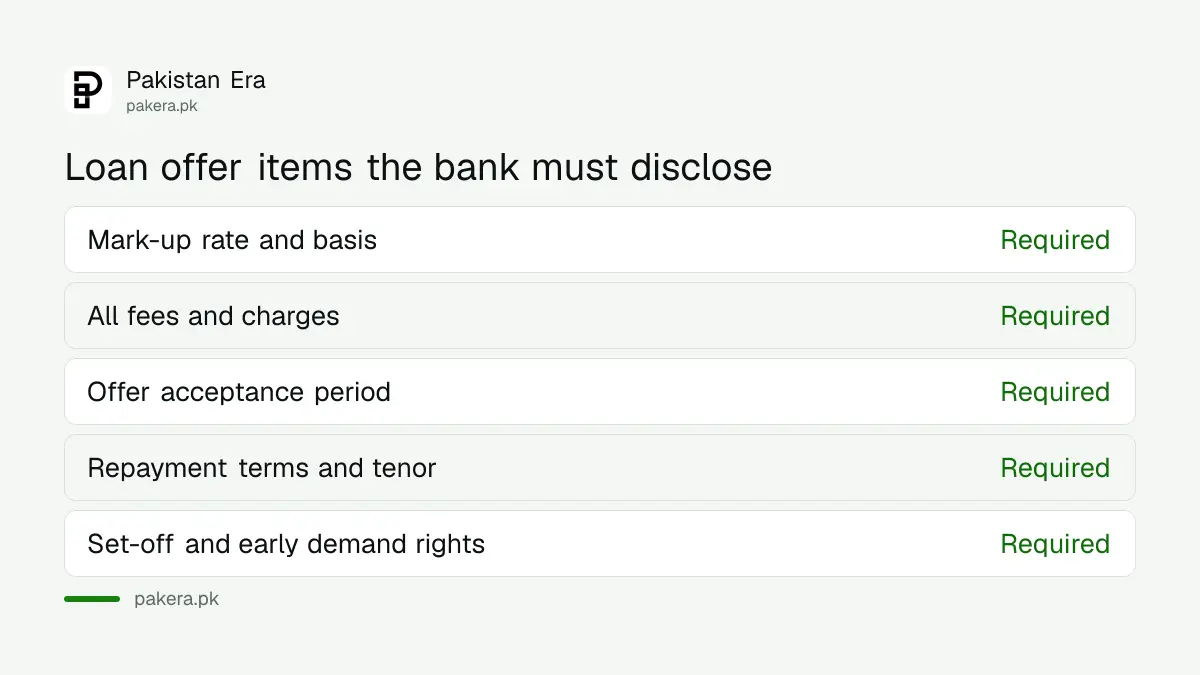
SBP says a bank must give you this information when you apply, or in a later offer: the rate of mark-up and whether it can change, how it is calculated, fees, the offer's acceptance period, repayment terms, the right to demand early repayment, key features, and the right of set-off.
| Item in section 4.9.2 | What to look for in your offer letter |
|---|---|
| (a) Rate of mark-up | Is it fixed or can it vary during the loan? |
| (b) Basis of mark-up | What it is linked to, when it is payable, and the number of days in the year used |
| (c) Fees and charges | Processing, insurance, documentation, valuation |
| (d) Offer period | The last date you can accept |
| (e) Repayment terms | Tenor and the instalment amount |
| (f) Demand for immediate repayment | Any overriding right of the bank |
| (g) Other features | Security, late payment penalties, early repayment fees |
| (h) Set-off | The bank's right to take other balances, including a joint account |
The day count in the mark-up formula changes what you pay
Item (b) asks the bank to state the number of days in the year it uses, for both ordinary and leap years. A bank that divides by 360 instead of 365 charges slightly more each day for the same annual rate. The difference is small per month and real over years.
Compare offers on the same basis. The rate on KIBOR today is the usual benchmark for variable loans, and how the SBP policy rate changes a loan instalment shows how a rate move reaches you. Ask the bank which benchmark it uses and when it resets.
Ask about application fees before you pay them
Section 4.2 says the bank must tell you the fees for applying for a product, and whether the fee is refundable if the application is rejected or not pursued. It must tell you before you become liable to pay the fee.
So ask one question at the counter: "If you reject this application, do I get this fee back?" Get the answer on the receipt or in writing. The guidelines also say a bank may not charge twice for one service or one breach of contract.
The bank must test your ability to repay and give you a signed offer before it lends
Section 4.8.2 says that before extending credit, a bank considers your income, expenses and assets and liabilities, reviews your earlier accounts, and gets information from the Electronic Credit Information Bureau, known as eCIB. It also looks at your repayment capacity.
The bank must also obtain the signed legal documents or offer letter, with its terms, from you before it pays out. Do not sign blank pages. Read the page that lists your rate and fees, and keep your own copy.
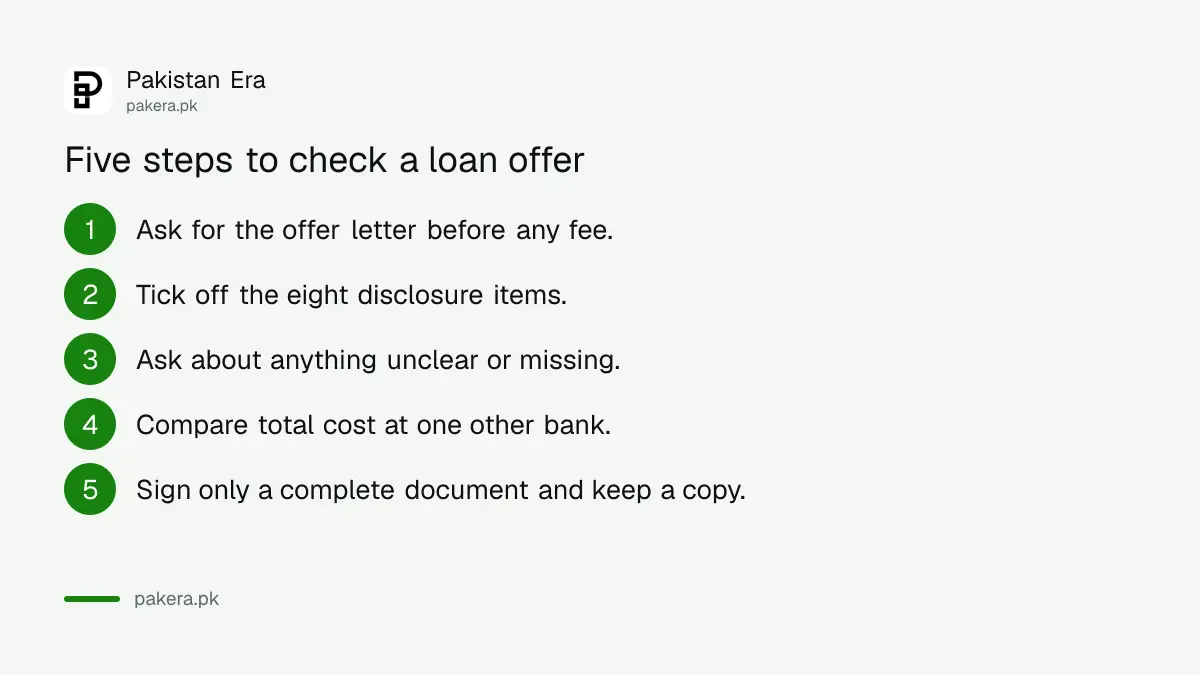
- Ask for the offer letter in writing before you pay any fee.
- Tick off the eight items above against the letter.
- Ask the officer to explain any item that is missing or unclear.
- Compare the total cost, not only the instalment, with one other bank.
- Sign only a complete document and take a signed copy home.
The bank must give notice before it changes your terms
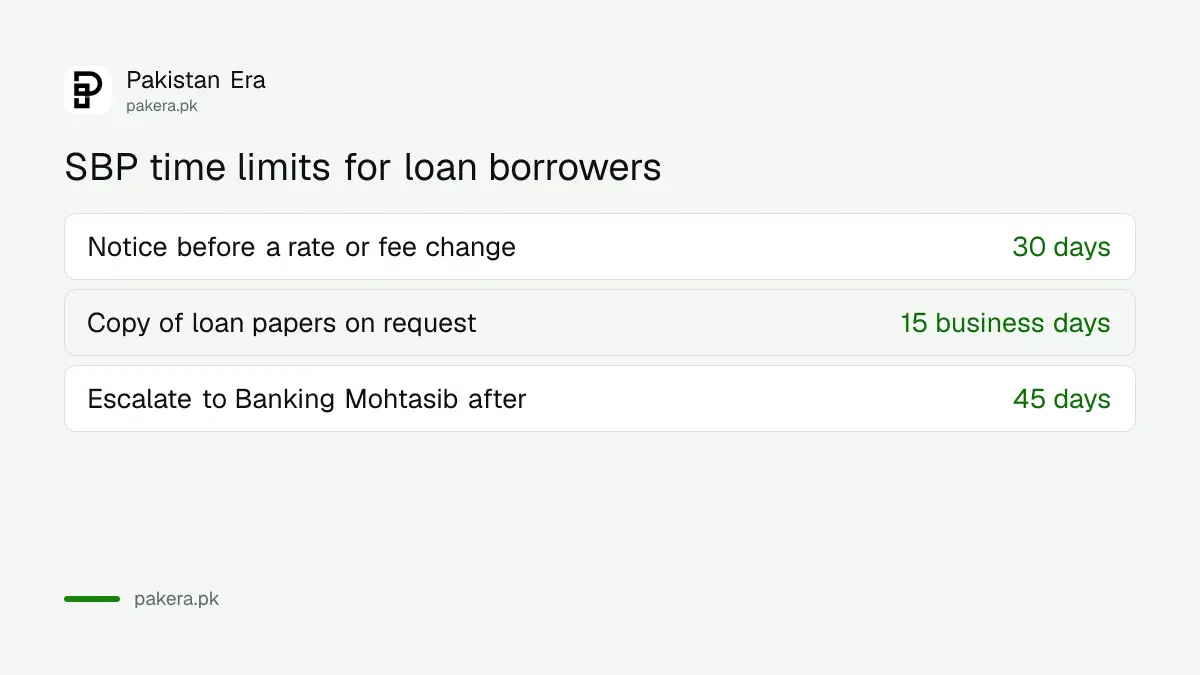
Section 3.5.1 says the bank must serve written notice at least 30 days before it introduces fees or charges, changes how mark-up is calculated, varies the mark-up rate or how often it is charged, or changes the terms and conditions.
The notice may come by letter, email, SMS or phone, by display in branches, by public notice or on the bank's website. A variable loan whose rate follows the market is a separate matter, so check how the agreement defines a reset. You can also ask for copies of your loan papers: the bank must supply them within 15 business days if the originals are under a year old, and may charge a fee that it has disclosed.
Complain in writing if an item is missing
SBP's complaints portal sets the order: complain to the bank's own complaint management unit first. If it does not reply within 45 days, or you are unhappy with the outcome, you can go to the Banking Mohtasib Pakistan.
The routes are explained in the guide to the Banking Mohtasib complaint. Before you borrow, the table of personal loans from Pakistani banks and the guide to bank charges to avoid help you compare the cost.
Common questions about bank loan offers in Pakistan
What must a bank tell me before I take a loan?
Eight things under section 4.9.2: the mark-up rate and its basis, all fees, the offer period, repayment terms, any right to demand repayment, key features and the right of set-off.
Can my bank change the mark-up rate after I sign?
Only as your agreement allows. SBP says the bank must give at least 30 days' written notice before varying the mark-up rate or how it is calculated.
Do I get my application fee back if the bank rejects me?
The bank must tell you whether it is refundable before you pay it. Ask for the answer in writing at the time.
Can I get a copy of my loan agreement?
Yes. On request the bank must give a copy within 15 business days if the original is less than a year old. It may charge a reasonable fee that it has disclosed.
Does the bank check my credit history?
Yes. Section 4.8.2 says the bank obtains information from the eCIB and considers your repayment capacity before it lends.
Are these guidelines still current?
The version on SBP's site cites circulars up to January 2015. We found no newer replacement, but SBP may have issued narrower rules since, so check the bank's own schedule of charges too.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 15 October 2026. Sections 3.3, 3.5, 4.2, 4.3, 4.8 and 4.9 come from SBP's Guidelines of Business Conduct for Banks. The complaint order comes from the FAQ of SBP's Sunwai portal. We did not apply for a loan to test a bank's offer letter. The 360 and 365 day point is our own illustration of why item (b) matters. This page explains the guidelines and is not financial advice.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.