Personal Loan in Pakistan: 8 Banks Compared on Rate, Limit and Fees
Personal loan rates in Pakistan run from KIBOR + 14% to 38%. We compare 8 banks on rate, amount, salary rule and fees, with a Rs 500,000 worked example to use.
A bank personal loan in Pakistan costs between about 26.7% and 38% a year on the rate cards we read on 6 October 2026. On Rs 500,000 over 3 years, that is roughly Rs 20,300 to Rs 23,500 a month. MCB's KIBOR plus 14% is the lowest published rate. Standard Chartered's "up to 38%" is the highest ceiling.
Personal loans are unsecured. You pledge nothing, so banks charge much more than on a car or home loan. We opened the personal loan pages, FAQs and schedules of charges of eight banks to compare rates, limits, salary rules and fees. KIBOR, the interbank rate many banks price on, was 12.68% for 1 year on the State Bank of Pakistan (SBP) home page on 5 October.
Two SBP rules apply at every bank. A personal loan can run for at most 4 years. And all your loan instalments together cannot pass 40% of your net income.
Eight banks' personal loans side by side
Published rates run from 1-year KIBOR plus 14% at MCB to a fixed rate of up to 38% at Standard Chartered. Maximum amounts run from Rs 750,000 on Bank Alfalah's app loan to Rs 4 million at Dubai Islamic Bank. Every bank caps the term at 4 years.
| Bank and product | Rate on the bank's page | Amount | Minimum income |
|---|---|---|---|
| MCB Personal Loan | 1Y KIBOR + 14% (good credit history) or + 16% | Rs 50,000 to Rs 2 million | Salaried only; MCB salary customers and others with a credit record |
| Allied Personal Finance | Up to 1Y KIBOR + 17% (salaried) or + 18% (self-employed) | Rs 30,000 to Rs 3 million | Rs 25,000 net with ABL salary account, Rs 35,000 otherwise |
| Bank Alfalah Digital Personal Loan | 1Y KIBOR + 18% | Rs 50,000 to Rs 750,000 | 1 year account history with Alfalah |
| Askari Personal Finance | 31% fixed (salaried, branch customer) to 37% fixed (self-employed, non-branch) | From Rs 50,000, up to the 40% limit | Rs 35,000 to Rs 70,000 by employer type |
| HBL PersonalLoan | Fixed, up to 35.99% | Rs 25,000 to Rs 3 million | Rs 35,000, salary paid into HBL |
| Standard Chartered Personal Loan | Fixed, up to 38% | Not read | Not read |
| JS Instant Personal Loan | Not published on the page | Rs 60,000 to Rs 2 million | Not stated |
| Dubai Islamic Personal Finance | Profit rate not published | Rs 50,000 to Rs 4 million | Rs 37,000 net (salaried) |
UBL's and Faysal Bank's websites refused our requests on 6 October, so they are missing here. Ask at a branch for their Key Fact Statement, the one-page summary every bank must give.
The cheapest rates come with conditions
MCB's KIBOR plus 14% is listed for salaried government and armed forces staff with a qualifying credit history. Askari's 31% is for a salaried customer who already banks with Askari. Allied and HBL say "up to", so your actual rate may be lower. Your employer, your salary account and your credit record move the price more than anything else.
Rs 500,000 over 3 years costs Rs 20,327 to Rs 23,475 a month
We worked out the monthly instalment on Rs 500,000 over 36 months at each bank's published rate, using today's KIBOR. The gap between the cheapest and dearest is about Rs 113,000 over the loan.
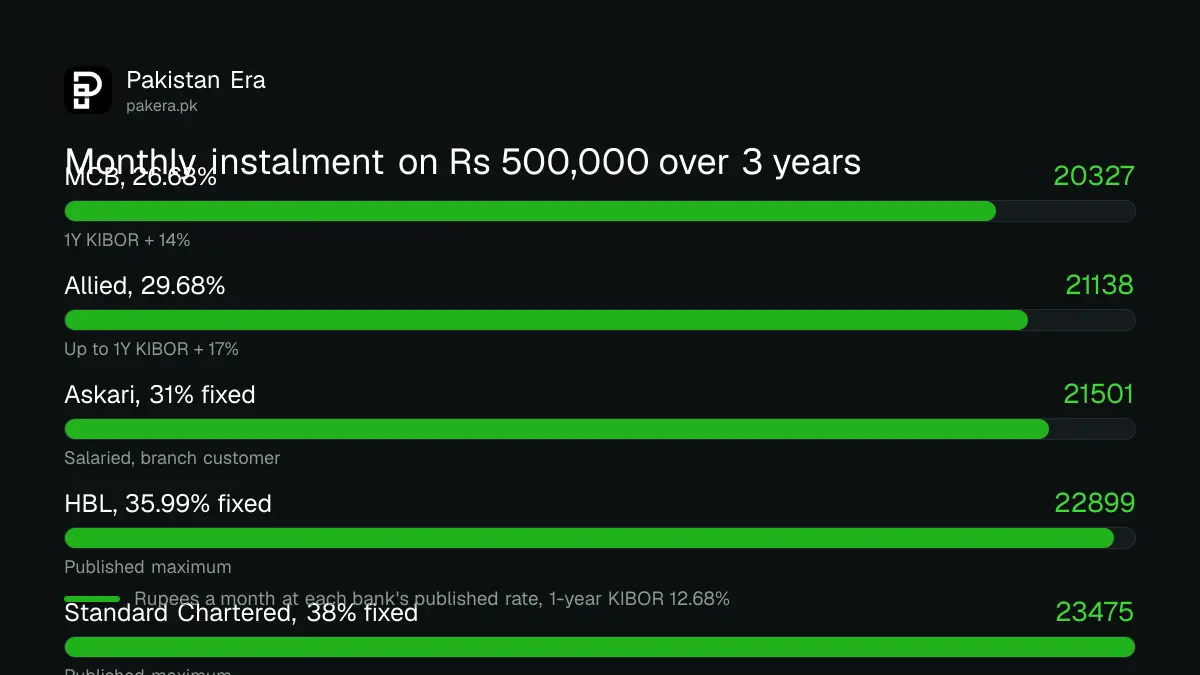
| Bank (rate used) | Monthly instalment | Total markup over 3 years |
|---|---|---|
| MCB, 26.68% | Rs 20,327 | Rs 231,767 |
| Allied, 29.68% (maximum) | Rs 21,138 | Rs 260,977 |
| Bank Alfalah, 30.68% | Rs 21,412 | Rs 270,848 |
| Askari, 31% | Rs 21,501 | Rs 274,021 |
| HBL, 35.99% (maximum) | Rs 22,899 | Rs 324,366 |
| Standard Chartered, 38% (maximum) | Rs 23,475 | Rs 345,099 |
At these rates you repay about Rs 1.46 to Rs 1.69 for every rupee borrowed. KIBOR-linked loans at MCB, Allied and Alfalah also reset when KIBOR moves. How a policy rate change reaches your EMI works the same way here.
Fees and early settlement add to the cost
Processing fees are small next to the markup, but early settlement charges are not. HBL charges 7% of the outstanding amount to close early. Standard Chartered charges 10% within the first 12 months.
- HBL: processing fee Rs 6,000 or 1.25% of the loan, whichever is higher, plus FED. Women account holders get 50% off. Early settlement 7% of outstanding. One partial payment allowed, at 5%, up to 6 instalments. Late payment Rs 1,250 each time.
- Standard Chartered: processing fee 1% or Rs 2,500, whichever is higher. Prepayment 10% of outstanding within 12 months, 5% after (schedule of charges, July to December 2026).
- Dubai Islamic Bank: processing fee up to Rs 5,000, charged only after approval.
- MCB: no processing fee if the loan is not approved.
- Allied, Askari, Alfalah and JS: as per their schedules of charges; Allied deducts the fee from the loan at disbursement.
On a Rs 500,000 HBL loan, the processing fee is Rs 6,250 plus FED. Closing it with Rs 300,000 outstanding would cost Rs 21,000 more.
The 40% rule decides how much you can borrow
SBP's consumer finance rules say all your monthly loan instalments together cannot pass 40% of your net income. Car loan, credit card and personal loan all count. Askari states the same 40% limit on its own page.
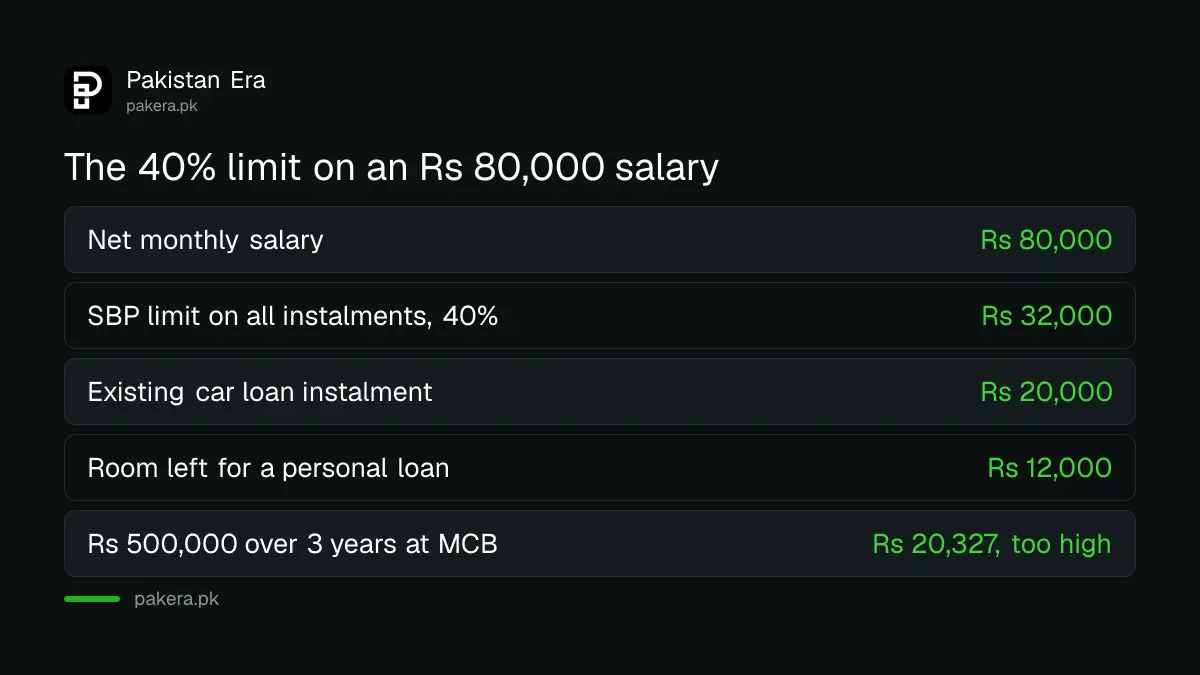
Take a net salary of Rs 80,000. The limit is Rs 32,000 a month for all loans. If you already pay Rs 20,000 on a car, only Rs 12,000 is left. That is not enough for the Rs 20,327 instalment above, so the bank would offer a smaller amount or say no.
Your record matters too. Every bank checks your eCIB credit report before approving. MCB's lower rate needs a qualifying credit history, and Alfalah refuses anyone with an overdue or default on record.
How to apply
- Check your eCIB report and clear any small overdue first.
- Add up your current instalments and check the 40% limit.
- Ask two or three banks, starting with your salary bank, for a Key Fact Statement.
- Compare the rate, the total markup and the early settlement charge.
- Apply with your CNIC, salary slip and bank statement, and keep a copy of the signed terms.
Unlicensed loan apps are not a cheaper shortcut
Lending apps are licensed by the Securities and Exchange Commission of Pakistan (SECP), not SBP. An unlicensed app has no regulator to answer to. Before you install one, check whether the lending app is SECP licensed.
Never give an app access to your contacts or photos. If an app threatens you or messages your family, report the loan app harassment to SECP and the cybercrime authority. If a bank treats you unfairly, the Banking Mohtasib hears complaints for free.
Common questions
Which bank has the lowest personal loan rate in Pakistan?
On the pages we read, MCB's 1-year KIBOR plus 14%, about 26.68% today. It applies to salaried staff with a qualifying credit history.
What is the maximum personal loan tenure in Pakistan?
4 years. SBP cut it from 5 to 4 years in 2021, and every bank we checked offers 1 to 4 years.
How much personal loan can I get on a Rs 50,000 salary?
Your total instalments can be up to Rs 20,000 a month under the 40% rule. With no other loans, that is a little under Rs 500,000 over 3 years at MCB's rate.
Is there an Islamic personal loan in Pakistan?
Yes. Dubai Islamic Bank offers Personal Finance from Rs 50,000 to Rs 4 million, based on a commodity sale called Musawamah.
Can I repay a personal loan early?
Yes, but it costs extra. HBL charges 7% of the outstanding amount, and Standard Chartered 10% within 12 months or 5% after.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 6 October 2026, on each bank's own personal loan page, FAQ or schedule of charges: MCB, Allied Bank, Bank Alfalah, Askari Bank, HBL, Standard Chartered (schedule of charges, July to December 2026), JS Bank and Dubai Islamic Bank. KIBOR is from the State Bank of Pakistan home page (as on 5 October 2026). The 40% limit and 4-year cap come from SBP BPRD Circular Letter 29 of 2021. Instalments are our own arithmetic, before fees and FED. Rates change, so confirm in the Key Fact Statement before signing. This is not financial advice.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.