Credit Card Instalment Plans in Pakistan: 9 Banks' Rates and Fees Compared
We read nine banks' 2026 charge sheets. HBL lists 24% on card instalments, Alfalah up to 40.74%, with fees from 1% to 25%. Compare plans, caps and conversion.
HBL has the lowest published markup on credit card instalment plans in Pakistan, 24% a year. Bank Alfalah's Step by Step plans go up to 40.74%. Processing fees run from 1% at JS Bank and Zindigi to "up to 25%" at Bank Alfalah, so the fee often matters more than the rate.
Every big card issuer lets you split a purchase into monthly payments, under names like EPP (extended payment plan), Step by Step or i-plan. The bank pays the shop and you repay it over 3 to 36 months.
We read each bank's July to December 2026 charge sheet or instalment page on 6 October 2026. Annual fees are in our credit card fee comparison for eight banks.
Instalment plan rates at nine banks, side by side
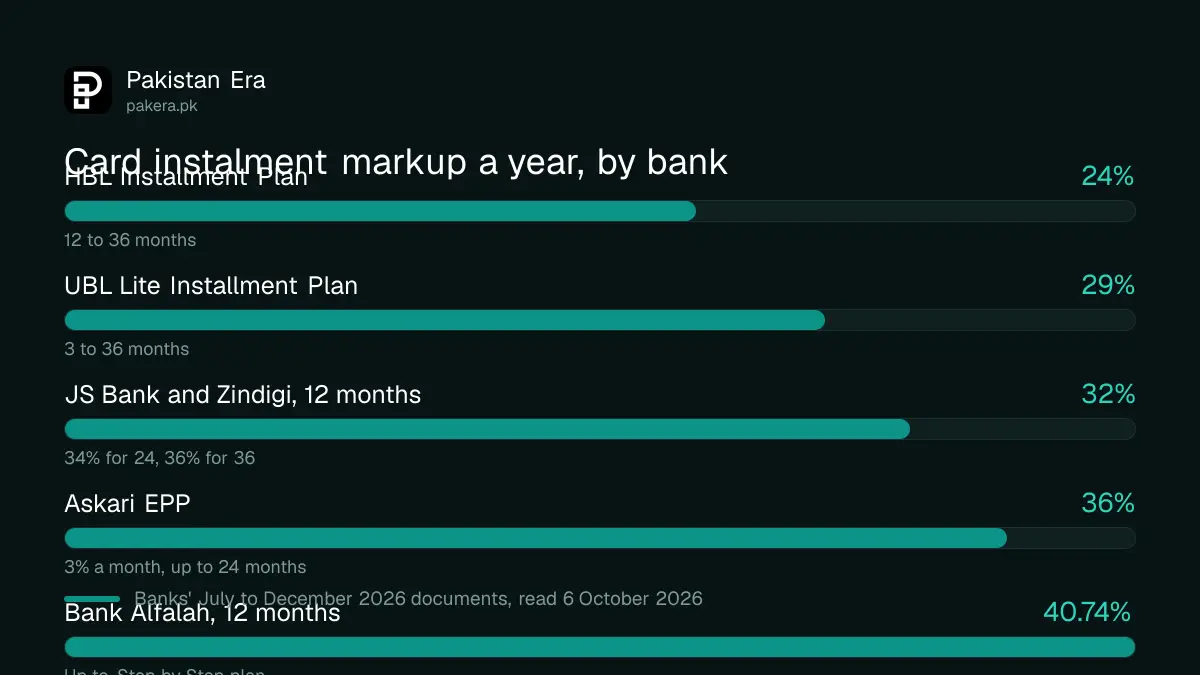
Published instalment markups run from 24% a year at HBL to about 41% at Bank Alfalah. UBL charges 29%, JS Bank 32% to 36% and Askari 36%. Standard Chartered charges up to its card rate of 46%.
| Bank and plan | Markup a year | Processing fee | Minimum purchase | Early settlement |
|---|---|---|---|---|
| HBL Installment Plan, 3 to 36 months | 24% | 2.5% or 5% on its September 0% offer | Rs 10,000 on offers | 6% of remaining principal |
| UBL Lite Installment Plan, 3 to 36 months | 29% | Booking fee as per UBL schedule | Rs 5,000 | Not published |
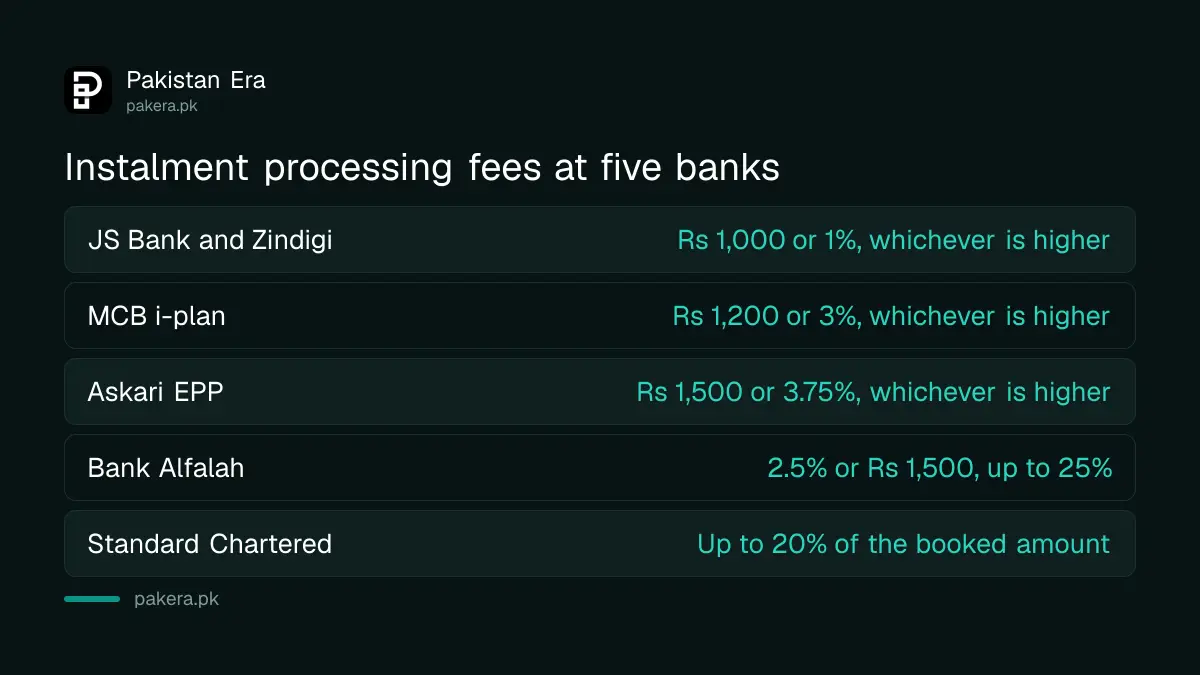
| JS Bank and Zindigi, 12 to 36 months | 32%, 34%, 36% | Rs 1,000 or 1% | Not published | Rs 1,000 or 5% of principal left |
| Askari EPP, up to 24 months | 36% (3% a month) | Rs 1,500 or 3.75% | Rs 10,000 | Not published |
| MCB i-plan | 3.25% a month, about 39% | Rs 1,200 or 3% | Not published | Rs 1,200 or 6% of balance left |
| Bank Alfalah Step by Step, 3 to 36 months | Up to 35.23% to 40.74% | 2.5% or Rs 1,500, up to 25% | Not published | 5% of balance or Rs 1,000 |
| Standard Chartered Asaan Instalment Plan | Up to the card APR | Up to 20% of the booked amount | Rs 10,000 on Daraz | Rs 1,000 or 5% of balance left |
| Allied Easy Installment | Not published (card rate 34%) | Charged, amount not published | Not published | Not published |
| Faysal Islami Noor, on DigiMall | Not published in readable form | Not published | Not published | None, says the bank |
Two banks are missing. Bank Al Habib's card summary box lists no instalment plan. Meezan Bank's website lists only debit cards, and its Islamic card products are reported for full launch in 2027. Federal excise duty, a tax on bank services, is added to every processing fee.
0% partner plans still charge a processing fee
A 0% plan at a partner shop drops the markup but keeps a one-time processing fee of 2.5% to 19% on the offers we read. Short plans are cheap. Long ones can cost as much as a loan.
| Offer | 3 months | 6 months | 12 months |
|---|---|---|---|
| MCB card on Daraz | 2.5% | 2.5% | 2.5% |
| Standard Chartered card on Daraz | No fee | 2.5% | 7% |
| HBL card, international purchases, until 30 September 2026 | 2.5% | 5% | 24% markup applies |
| Bank Alfalah card on Samsung's store | 6% | 10% | 19% |
Standard Chartered's Daraz page contradicts itself: its terms say 2.5% and 7%, its questions section says 5.5% and 11.5%. Ask the bank before you check out.
Bank Alfalah's 19% fee over 12 months works out to roughly 40% a year, Rs 19,000 on a Rs 100,000 phone. The cost of apps and wallets is in our guide to whether buy now pay later is worth it.
Your credit limit is the cap on every instalment
No bank sets a separate instalment cap. The cap is your available credit limit: the full price is blocked when you book the plan, and each payment frees that much again. Askari allows several plans at once up to that limit. Limits vary widely:
- Allied Bank: up to Rs 500,000 on a Gold card and Rs 3 million on Platinum, or Rs 7 million against security.
- MCB: from Rs 25,000 on the entry card up to Rs 7 million for Prime customers.
- Zindigi: its terms let it issue the card against a cash deposit at least as large as the limit.
- Bank Alfalah: new cardholders cannot use Step by Step plans for the first 3 months after activation.
Income sets the limit. Bank Alfalah's Classic card needs Rs 50,000 a month if salaried and Rs 75,000 if self employed. Faysal Islami Noor starts at Rs 40,000 for employees of approved companies. Other banks did not publish a floor on the pages we read.
How to convert a card purchase into instalments
Book the plan at checkout, or call your bank after the purchase and ask to convert it, well before your statement date. Most banks need 3 to 7 working days.
- Check the purchase meets the minimum: Rs 5,000 at UBL and Rs 10,000 at Askari and most marketplace offers.
- At checkout, pick the instalment option and the tenure, or pay normally with your card.
- To convert later, call the bank: UBL on 111-825-888, Bank Alfalah on 021-111-225-111, or Askari's contact centre.
- Ask for the processing fee, the markup, and the total payable, and keep the SMS or email confirmation.
- Check your next statement shows one instalment, not the full amount. If it shows the full amount, call before the due date.
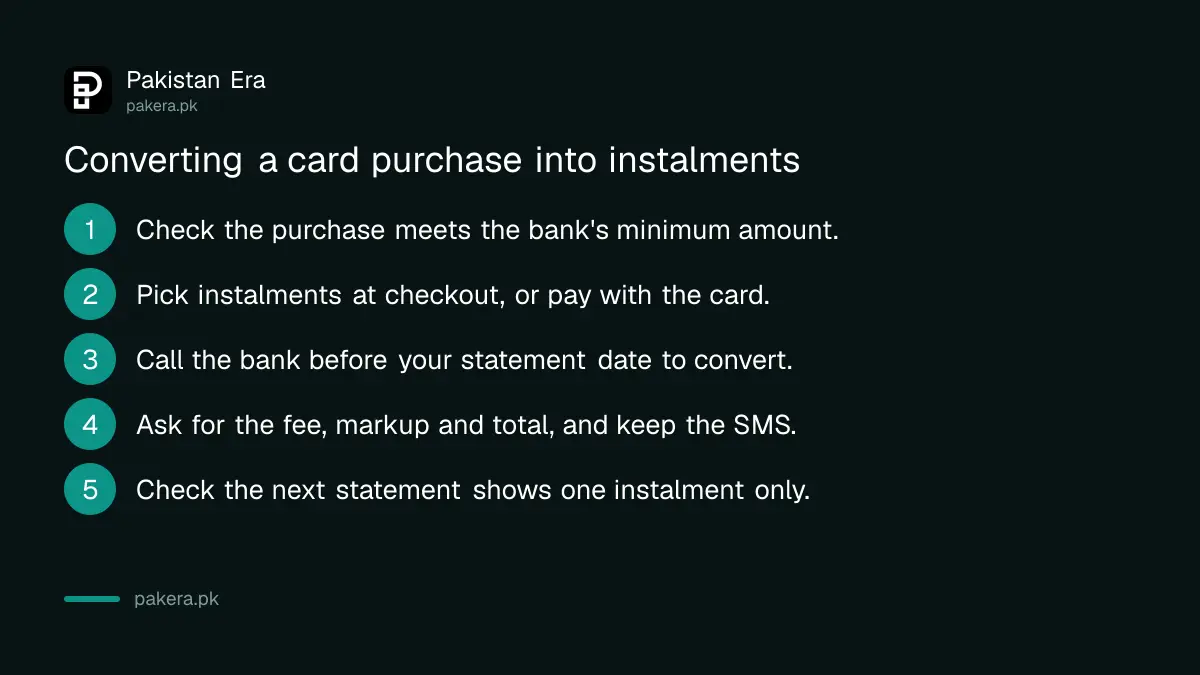
HBL wants 3 working days before your statement date and Daraz 7. Miss that and the full amount lands on one bill.
Best credit card for instalments, by what you need
HBL is best for long plans at a published rate. JS Bank and Zindigi have the lowest processing fee. MCB is cheapest for a 12 month 0% plan on Daraz. Faysal Islami Noor suits buyers who want an Islamic card and no early settlement fee.
| Best for | Card | Why |
|---|---|---|
| Long plans, 12 to 36 months | HBL | 24% a year, the lowest instalment markup published |
| Low upfront fee | JS Bank or Zindigi | Rs 1,000 or 1%, so Rs 1,000 on a Rs 100,000 purchase |
| 0% at a marketplace | MCB | 2.5% fee for up to 12 months on Daraz |
| Islamic option | Faysal Islami Noor | DigiMall plans with no early settlement charge |
| Any shop, any purchase | Askari | Converts any retail purchase of Rs 10,000 or more, in Pakistan or abroad |
The cheapest plan is still debt. Carry a normal balance beside it and markup on the rest of the bill can cost more than the plan. Our Zindigi credit card review shows how a 49.99% card rate stacks up.
Balance transfer plans move another bank's card debt
A balance transfer pays off a card at another bank and turns it into instalments at a lower rate. HBL charges 24% a year, Allied 24% with a Rs 500 fee, and Bank Alfalah 26%. UBL instead charges a one-time fee from 5.2% to 16.5%.
UBL's fee is 5.2% for 3 months, 9% for 6, 12.75% for 9 and 16.5% for 12. MCB's i-switch charges Rs 1,200 or 3%. A transfer only helps if you stop using the old card.
For bigger debts the comparison changes. The rates on car financing and personal loans follow KIBOR, while card rates do not, as our explainer on how the SBP policy rate moves your EMI sets out.
Try it on your own numbers: use our Phone Instalment Calculator to see what a card instalment plan really costs a year, fees included.
Common questions
Which credit card has the lowest instalment rate in Pakistan?
HBL, at 24% a year on its Installment Plan, according to its July to December 2026 schedule of charges.
Can I convert a purchase into instalments after paying?
Yes, at most banks, if you call before your statement date.
Is a 0% instalment plan on a credit card really free?
No. It usually carries a processing fee of 2.5% to 19% of the price, plus tax on the fee.
Does Meezan Bank offer credit card instalments?
Not yet. Meezan's website lists only debit cards.
What happens if I pay off an instalment plan early?
Most banks charge a fee, such as Rs 1,000 or 5% of the balance at Standard Chartered and Bank Alfalah. Faysal Islami Noor's DigiMall plans have none.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 6 October 2026. Figures are from each bank's own July to December 2026 schedule of charges, key fact statement or summary box, including Bank Alfalah's schedule of charges and Askari's Extended Payment Plans page, plus Daraz's and Samsung's partner terms. HBL's schedule text is jumbled, so its early settlement figure was matched by position. Banks revise these sheets every January and July.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.