Buy Now Pay Later in Pakistan: What a Rs 100,000 Phone Really Costs
We compared BNPL apps, bank card plans and wallet credit in Pakistan. A Rs 100,000 phone costs Rs 2,500 to Rs 25,000 extra over 12 months. See who is licensed.
Buy now pay later in Pakistan is worth it only when the total you pay is close to the cash price. On a Rs 100,000 phone over 12 months, the extra cost we worked out runs from about Rs 2,500 to more than Rs 25,000, depending on who lends to you.
The word "0%" does most of the selling. Almost every plan still charges something: a processing fee, a markup, a higher price, or a fee for paying early.
We read the Securities and Exchange Commission of Pakistan's (SECP) lending app whitelist of 11 September 2026, seven banks' instalment terms, and JazzCash's and Easypaisa's charges. We also priced one phone on QistBazaar on 6 October 2026.
Five kinds of buy now pay later you will meet in Pakistan
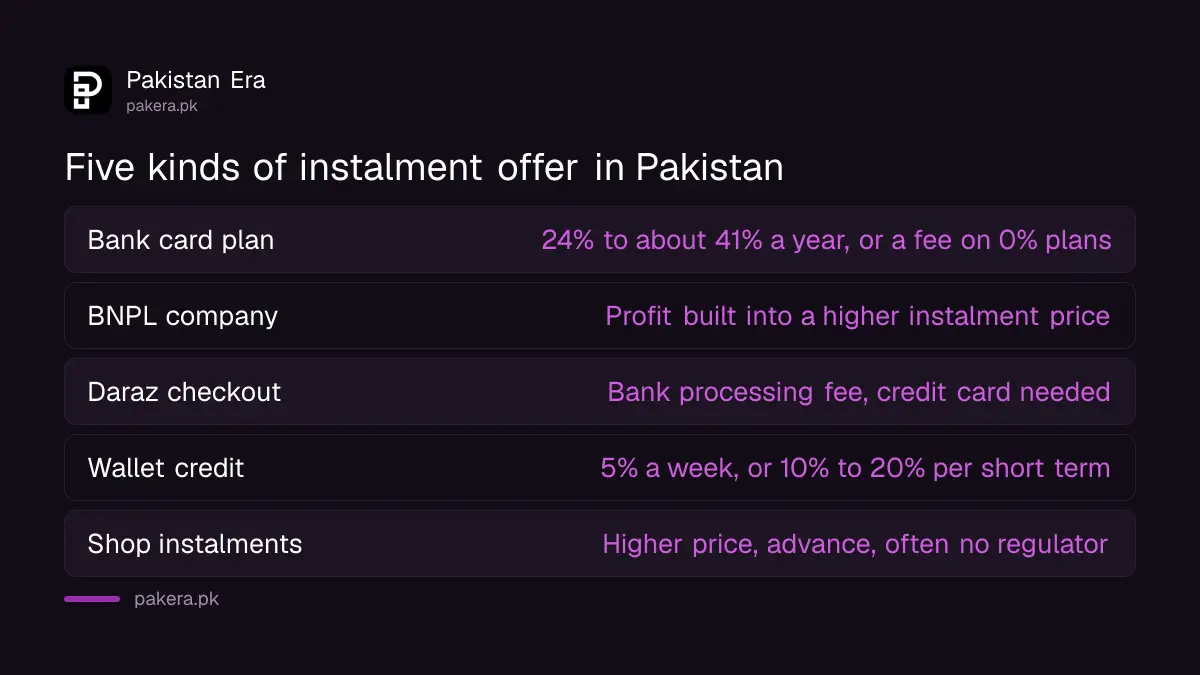
Pakistani shoppers meet five types of instalment offer: bank card plans, licensed BNPL companies, marketplace checkouts, wallet credit, and shop instalments. They differ in who lends, who regulates them, and where the cost sits.
| Type | Examples | Who regulates the lender | How you pay for it |
|---|---|---|---|
| Credit card instalment plan | HBL, UBL, Askari, MCB, Bank Alfalah | State Bank of Pakistan | 24% to 41% a year, or a fee on "0%" plans |
| BNPL company (NBFC) | QistBazaar, Baadmay, Alif Shop, PalmPay | SECP | Profit built into the price |
| Marketplace checkout | Daraz easy instalments | The card's bank | Bank processing fee |
| Wallet credit | JazzCash ReadyCash, Easypaisa BNPL | SBP or SECP | 5% a week, or 10% to 20% a term |
| Shop instalments | Electronics and bike dealers | Often nobody | Higher price and advance |
An NBFC is a non-banking finance company, a lender that is not a bank, licensed by SECP. A dealer's own instalment scheme usually has no regulator at all.
SECP's whitelist names eight BNPL lenders
SECP's White List of Digital Lending Apps, updated 11 September 2026, tags eight lenders for BNPL: five BNPL apps and three small loan apps that also offer BNPL. Any BNPL app not on that list is not a licensed digital lender.
The BNPL lenders on the list are:
- QistBazaar (Private) Limited, app QistBazaar
- MG Financial Services Limited, app Baadmay
- Alif Finance (Private) Limited, app Alif Shop
- PalmPay (Private) Limited, app Palmpay
- Tez Financial Services Limited, apps ZoodPay and ZoodMall, listed "for recovery of outstanding portfolio" only
Tez is listed only to collect money already lent, so ZoodPay is not signing up new buyers under it. Three small loan apps also carry a "Nano and BNPL" tag: Paisayaar, Aitemaad and Daira.
SECP also licensed Alibaba-owned Koko Tech Pakistan for BNPL on 14 April 2026, but it had no app on the September list. Before you sign up anywhere, check a lending app against SECP's list by its exact name.
What a Rs 100,000 phone costs over 6 and 12 months
On a Rs 100,000 phone, a "0%" bank plan with a low fee costs about Rs 2,500 extra. A full markup plan costs Rs 13,000 to Rs 26,000 over 12 months.
| Plan | Rate or fee from the lender's page | Extra cost, 6 months | Extra cost, 12 months |
|---|---|---|---|
| MCB card on Daraz, "0%" | 2.5% processing fee | Rs 2,500 | Rs 2,500 |
| Standard Chartered card on Daraz, "0%" | 2.5% (6 months), 7% (12 months) | Rs 2,500 | Rs 7,000 |
| Bank Alfalah card on Samsung's store, "0%" | 10% (6 months), 19% (12 months) | Rs 10,000 | Rs 19,000 |
| HBL Installment Plan | 24% a year | Rs 7,115 | Rs 13,472 |
| Askari EPP | 36% a year plus 3.75% fee | Rs 14,509 | Rs 24,305 |
| MCB i-plan | 3.25% a month plus 3% fee | Rs 14,678 | Rs 25,361 |
We worked out the markup plans on a reducing balance, before tax on the fee, so your bank's schedule may differ slightly. The bank-by-bank detail is in our comparison of credit card instalment plans.
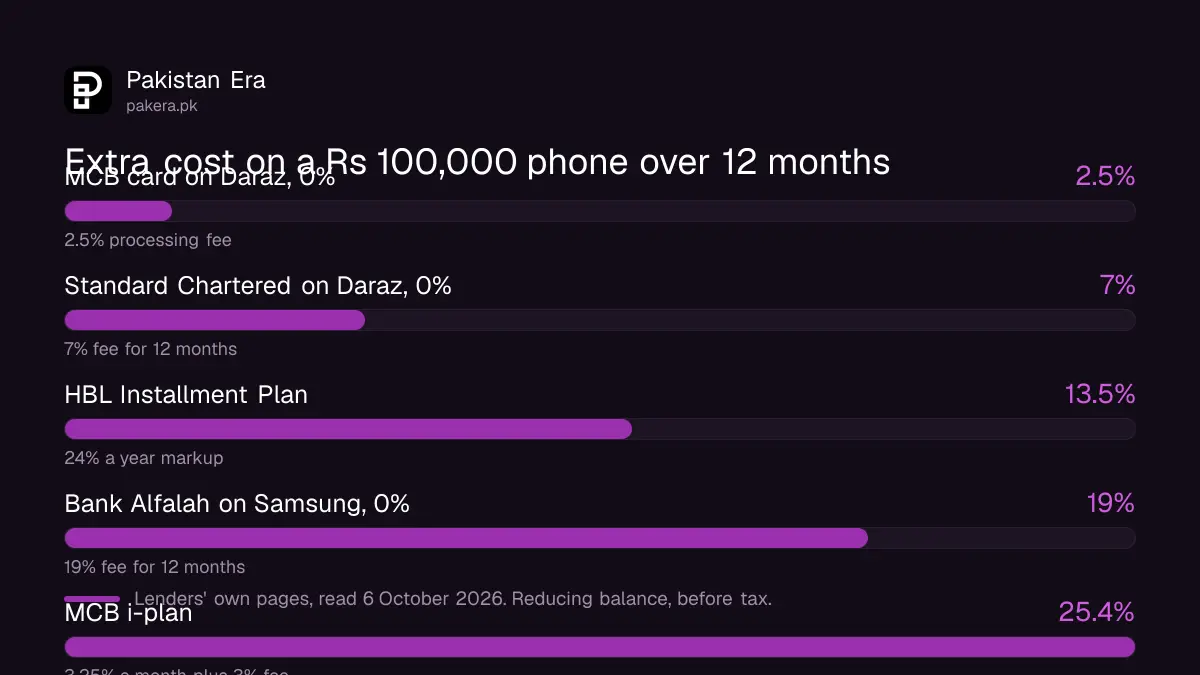
Bank Alfalah's 19% fee is labelled "0% markup", yet it costs more than HBL's open 24% plan. Over 12 months it works out to roughly 40% a year.
When 0% is really 0%, and when it is not
A plan is close to free only when the processing fee is small, the price matches the cash price elsewhere, and early settlement carries no penalty. Fail any one and "0%" is a loan with its cost moved somewhere else.
- The processing fee. It runs from 1% at JS Bank to "up to 25%" at Bank Alfalah.
- The price. A partner store can charge instalment buyers more. Compare the cash price at two other sellers.
- The early settlement fee. Standard Chartered charges Rs 1,000 or 5% of what is left. MCB charges Rs 1,200 or 6%.
We tested this on QistBazaar, which sells on Musawamah, an Islamic sale where profit is built into the price. For the Infinix Hot 70 (6GB, 128GB) on 6 October 2026, the 3 month plan totalled Rs 78,100 and the 12 month plan Rs 105,100. That is Rs 27,000, or about 35%, more for nine extra months.
QistBazaar shows every plan upfront, so nothing is hidden. But "no interest" does not mean "no cost".
Wallet credit and BNPL cost the most per month
JazzCash ReadyCash charges 5% a week on loans of Rs 100 to Rs 50,000. Easypaisa's BNPL for bills, loads and QR payments charges 10% for 14 days or 20% for 30 days.
JazzCash's loan is due in 28 days, so Rs 20,000 for four weeks costs about Rs 4,000. Easypaisa adds a one-time 5% late fee. Both suit a gap before payday, not a phone.
Late payments, fees and your eCIB record
A missed bank instalment brings a late fee and goes onto your eCIB report, the State Bank's credit record that the next lender reads. MCB and Allied Bank print this warning in their 2026 summary boxes.
We could not confirm whether each BNPL company reports to eCIB, so ask the lender before you sign. How to read your record is in our explainer on the eCIB credit report.
Red flags before you sign any instalment plan
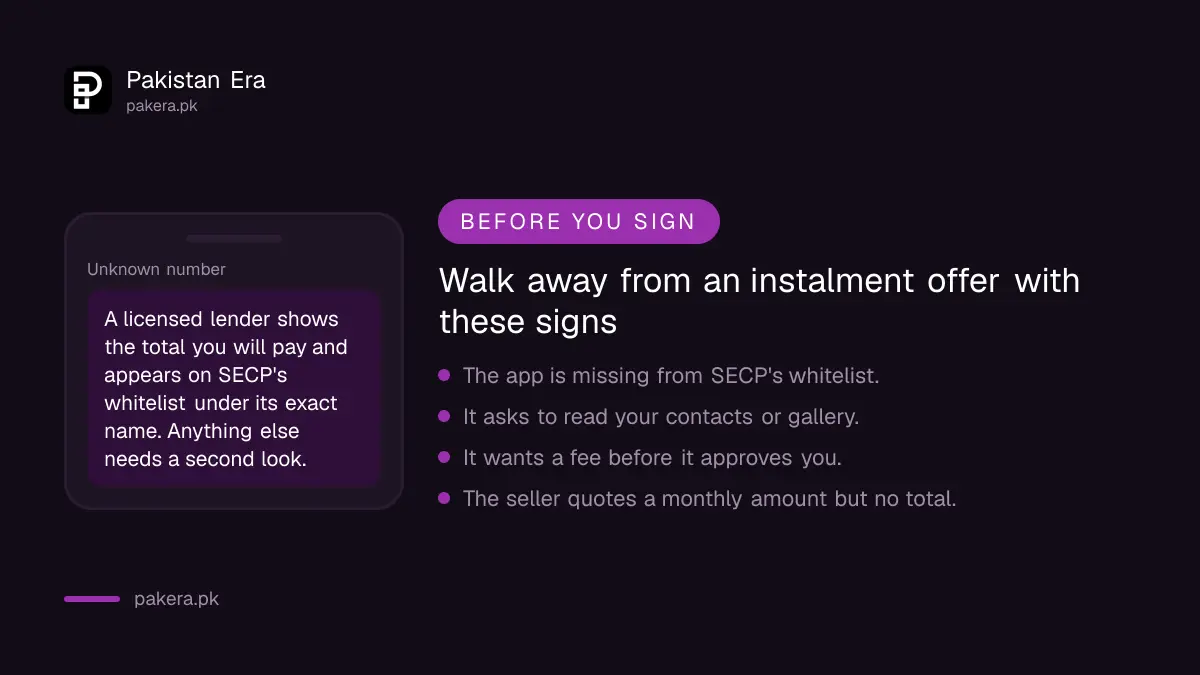
Walk away if the app is missing from SECP's whitelist, asks for your contacts, wants a fee before approval, or will not show the total payable in writing.
- The app is not on SECP's whitelist under its exact name.
- It asks for access to your contacts or photos.
- It wants a "registration" fee before approval.
- The seller quotes only the monthly amount.
- A dealer wants blank signed cheques or your original CNIC.
If an unlicensed app has already started threatening you or your contacts, report loan app harassment to the National Cyber Crime Investigation Agency and SECP.
Is buy now pay later worth it? Our verdict
Yes, when the plan is short, the fee is under about 3%, and you would have bought the item anyway. No, when the cost adds more than 10% to the price, or when you are stretching money you do not have.
A 6 month "0%" bank plan with a 2.5% fee is cheap credit, roughly 9% a year. A 12 month plan with a 19% fee is not.
For a car, the rates on car financing are lower because they track KIBOR, and how the policy rate moves your EMI explains why card plans barely follow it.
Try it on your own numbers: use our Phone Instalment Calculator to compare the real yearly cost of card and BNPL plans on any price.
Common questions
Is buy now pay later halal in Pakistan?
Some plans are designed to be. QistBazaar sells on Musawamah, while conventional card plans charge markup.
Which BNPL apps are licensed by SECP?
The 11 September 2026 whitelist names QistBazaar, Baadmay, Alif Shop and Palmpay, plus Paisayaar, Aitemaad and Daira. ZoodPay is listed for recovery only.
Can I buy on instalments without a credit card?
Yes. QistBazaar, a licensed BNPL company, sells after document checks and an advance payment, with no card needed.
Does a 0% instalment plan affect my credit limit?
Yes. Banks block the full purchase price on your card limit and release it as you pay each instalment.
What happens if I miss a BNPL payment?
You pay a late fee, and a bank reports the missed payment to your eCIB record.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 6 October 2026. Licensing is from SECP's White List of Digital Lending Apps of 11 September 2026 and SECP's 14 April 2026 release on Koko Tech. Bank figures are from each bank's July to December 2026 schedule, summary box or instalment page, and from Daraz's and Samsung's partner terms. Wallet charges are from JazzCash's ReadyCash page and Easypaisa's Schedule of Bank Charges. Offers change often, so confirm the fee on the checkout screen.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.