How to Check If a Lending App Is SECP Licensed in Pakistan
Check if a loan app is SECP licensed before you borrow: the whitelist, the illegal apps list, red flags, the company search, and where to report an illegal one.
Before you borrow from a loan app in Pakistan, check its name against the Securities and Exchange Commission of Pakistan's Whitelist of Digital Lending Apps and its separate list of apps already found illegal. Both are published on secp.gov.pk. If the app is not on the whitelist, SECP does not stand behind it.
An app that promises cash in minutes, with no paperwork and no guarantor, is the exact pitch SECP has warned against since 2023. Some of those apps belong to a licensed Non-Banking Finance Company, or NBFC, the category SECP uses for lenders that are not banks. Others borrow a licensed name to look trustworthy and are not licensed at all. The only way to tell them apart is to check.
We read SECP's own complaint and registration pages, its illegal apps list, its digital lending press releases, and the National Cyber Crime Investigation Agency's complaint channel. Where SECP's site blocked an automated read, we say so rather than guessing at what the page contains.
SECP's whitelist is the only real check for a licensed lender
SECP keeps a Whitelist of Digital Lending Apps run by licensed NBFCs, published as a dated PDF on its website and updated whenever a new app is approved or dropped. A lending app's name has to appear on that list, matched to the NBFC that owns it, before SECP will call it licensed.
SECP republishes the whitelist each time an app is added or removed, as a dated document rather than one fixed page, so an old screenshot or blog post naming "approved apps" can already be wrong. Open the whitelist yourself at secp.gov.pk and match the app's exact name and the company behind it, not a similar-sounding name.
We could not open the whitelist PDF itself through an automated fetch, because SECP's site runs a browser check that blocks that kind of request. That is a limit of our tooling, not evidence either way about any app, so treat the whitelist on SECP's own page as the authority and not this article.
SECP also names apps it has already ruled illegal
Separate from the whitelist, SECP publishes a List of Illegal Personal Loan Apps and Platforms, a running record of apps it has investigated and found to be operating without a licence. An app on that list is a clear no, whatever its Play Store rating says.
A name missing from both lists is not automatically safe. SECP adds apps to the illegal list only after it investigates them, so a very new app can be unlicensed and simply not yet listed either way. Treat "not on the whitelist" as the decisive signal, and "not yet on the illegal list" as no comfort at all.
| Where the app sits | What it means |
|---|---|
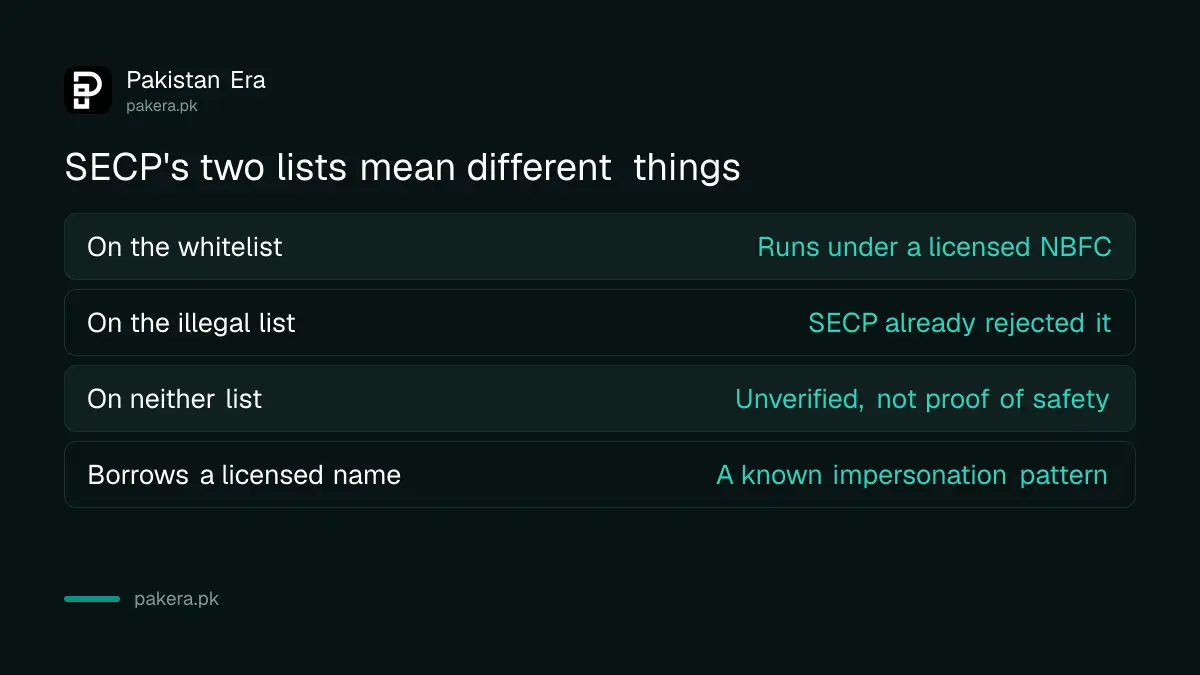
| Named on SECP's whitelist | Runs under a licensed NBFC, the strongest signal available |
| Named on SECP's illegal apps list | SECP has already investigated and rejected it |
| Named on neither list | Unverified, could be new, unlicensed, or simply unreviewed |
| Uses a licensed NBFC's name but a different app | A common impersonation SECP has warned about by name |
SECP's own warnings describe five signs of an illegal app
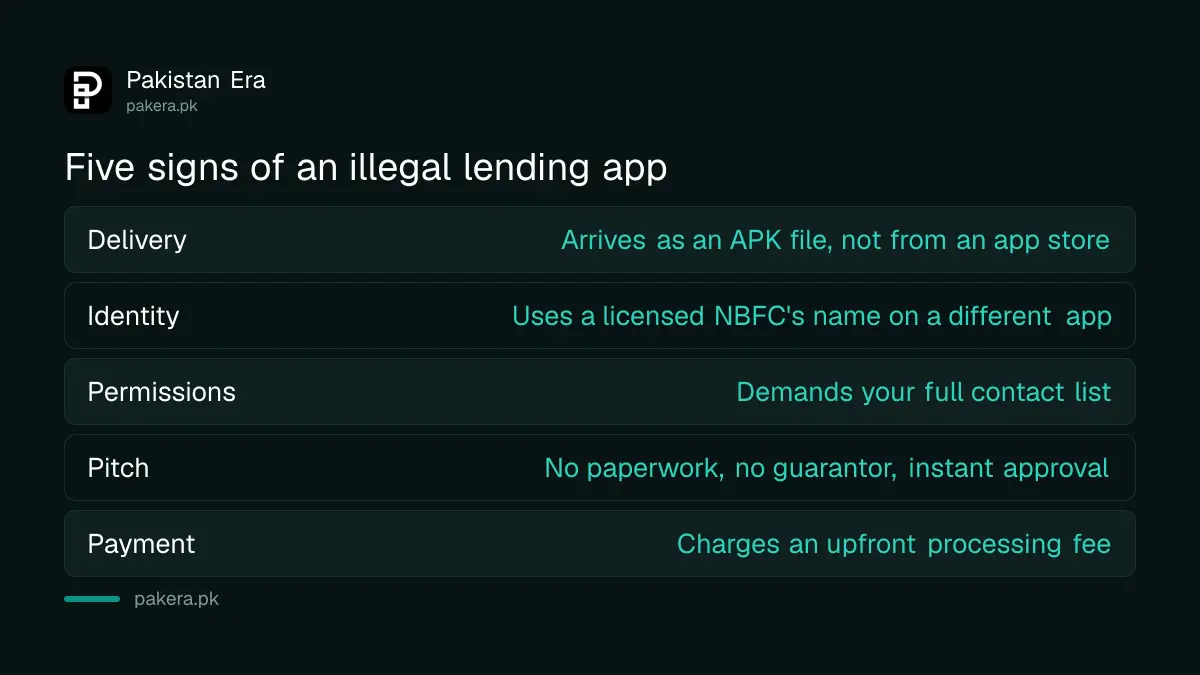
SECP's press releases on loan app crackdowns repeat the same pattern each time: the app reaches you outside an official store, borrows a real company's name, and asks for more than a lender needs. Those are the signs worth checking before the SECP whitelist, not instead of it.
- It arrived as an APK file through WhatsApp, a website or an ad, not the Google Play Store or Apple App Store.
- It uses the name of a real licensed NBFC, but the app itself is not the one on the whitelist.
- It asks to read your entire contact list before it will approve anything.
- It promises a loan with no paperwork, no guarantor and no collateral, approved within minutes.
- It takes an upfront "processing fee" before any loan is paid out.
Check the company behind the app, not only the app's name
A lending app is only as legitimate as the NBFC that runs it, and SECP's company registry is where that company's status lives. The portal is at eservices.secp.gov.pk, separate from the whitelist PDF, and a basic company name search there is free.
We tried the public search ourselves on 4 October 2026 and the page returned a server error on that attempt, so we cannot say here how its results display for a specific company. If you reach it and it is working, match the exact legal name from the loan app's terms and conditions, not a trading name from its marketing, against what the registry shows.
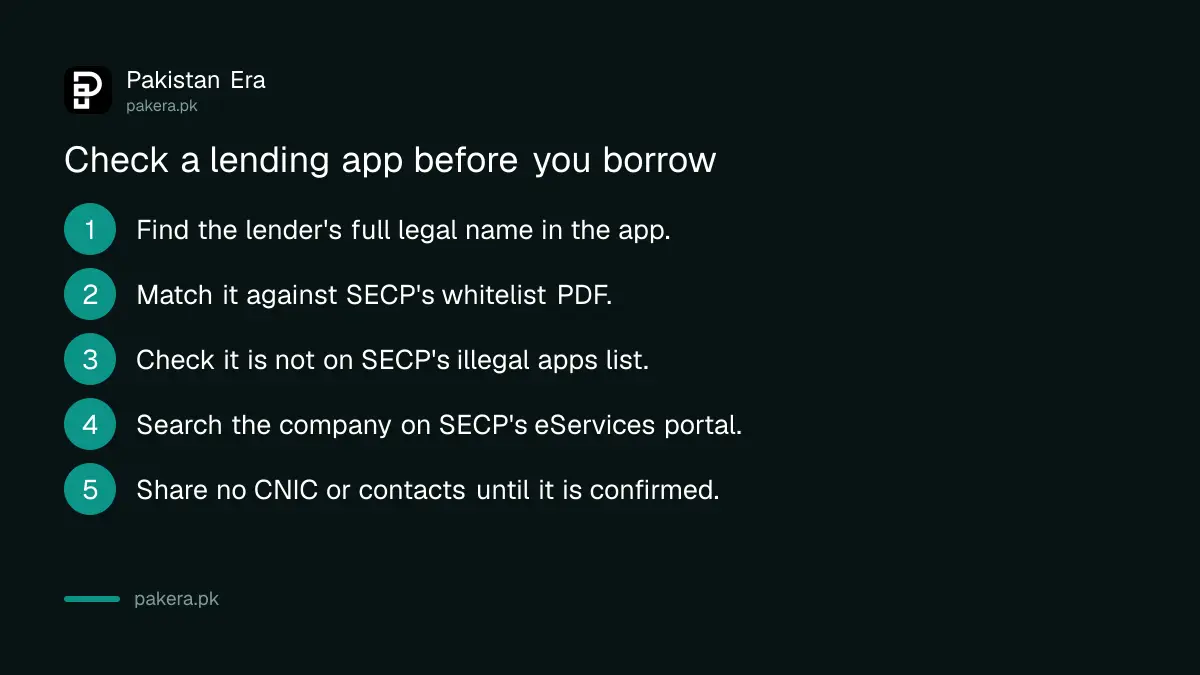
- Open the loan app's terms and conditions or "about" screen and find the full legal name of the lender.
- Search that exact name on SECP's whitelist document for the current date.
- Search the same name on SECP's illegal apps list.
- If neither list settles it, use SECP's company search at eservices.secp.gov.pk for the company's registration status.
- If you still cannot confirm it, do not share your CNIC, contacts or bank details with the app.
Report an illegal lending app to SECP and NCCIA, not the old FIA cybercrime wing
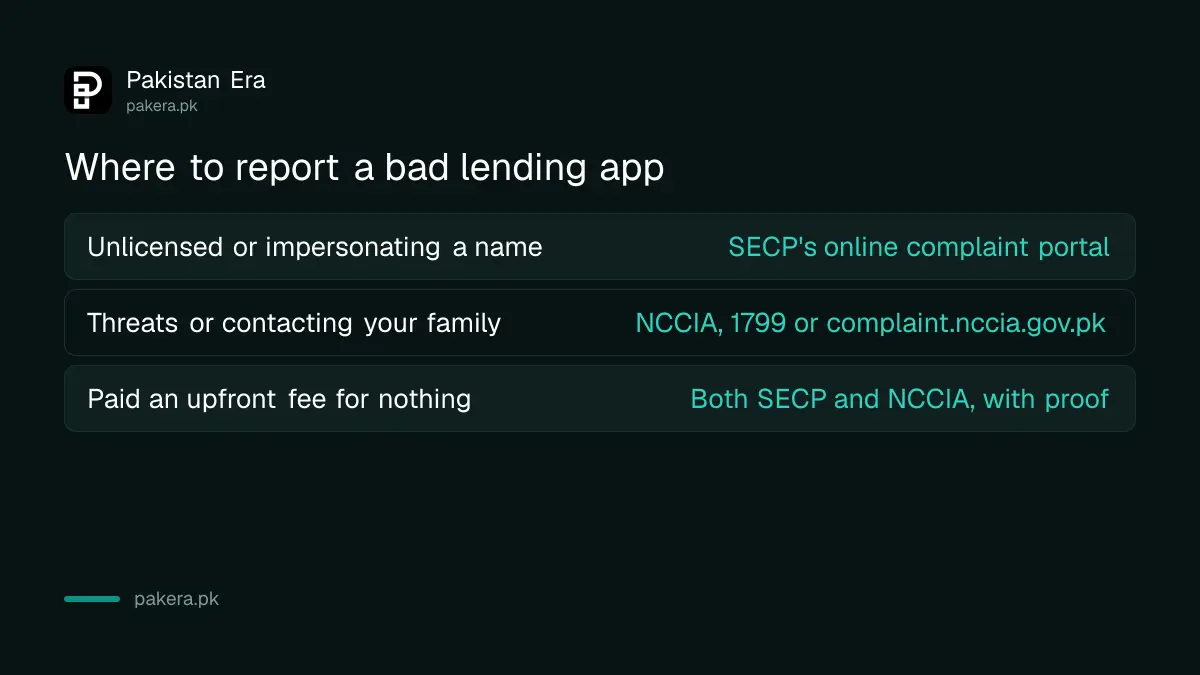
If an app turns out to be unlicensed, or starts threatening you over a missed payment, SECP takes complaints against the lender and the National Cyber Crime Investigation Agency takes complaints about the harassment itself. The Federal Investigation Agency's old Cybercrime Wing closed in 2024 and NCCIA took over its cases, so a tip pointing you to "FIA cybercrime" is sending you to a desk that no longer exists.
SECP's own complaints page asks you to raise the issue with the company first, then use the Submit Your Complaint button on its site for anything unresolved. NCCIA's complaint portal is separate and is built for the threats and blackmail side of a bad loan app, such as calls to your contacts or messages using your photos.
| What happened | Who to tell |
|---|---|
| App is unlicensed or misusing a licensed name | SECP, through its online complaint portal |
| App is threatening you or contacting your family | NCCIA, 1799 or complaint.nccia.gov.pk |
| You already paid an upfront fee and got nothing | Both SECP and NCCIA, with your payment proof |
A loan app can also come after someone who has already been threatened over an unpaid balance, which is a different situation from checking an app before you install it. SECP has named specific lenders this way before, including one app it delisted while scam calls kept using its old name to collect from borrowers who had never touched the real service.
Common questions
Is there a single app that shows every SECP licensed lender?
No. SECP publishes the whitelist as a dated PDF document on its own site rather than as a searchable app or live page, so you check the current PDF each time.
What if the app is not on either SECP list?
Treat it as unverified. SECP adds apps to its illegal list only after investigating them, so a new unlicensed app can sit off both lists for a time.
Can a bank-linked wallet's loan feature skip this check?
No. If a wallet or platform offers a loan feature through a partner NBFC, that NBFC and its app still need to appear on SECP's whitelist under its own name.
Does SECP or the State Bank regulate NBFC lenders?
SECP does. The State Bank's own complaint guidance says it has no jurisdiction over non-bank finance companies and directs those complaints to SECP instead.
Who do I contact if a loan app accesses my contacts to threaten me?
The National Cyber Crime Investigation Agency, on its 1799 helpline or through complaint.nccia.gov.pk. That is a cyber crime matter, separate from SECP's check on the lender's licence.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on 4 October 2026. SECP's Whitelist of Digital Lending Apps and its separate List of Illegal Personal Loan Apps and Platforms are named from SECP's own document pages and press releases, including its February 2024 crackdown notice naming eight apps and describing how they reached borrowers. SECP's complaint process, including raising an issue with the company first and its online portal, is read from SECP's investor complaints page. NCCIA's 1799 helpline and complaint.nccia.gov.pk portal, and the FIA Cybercrime Wing's closure into NCCIA in 2024, are confirmed from NCCIA's own site and Pakistani reporting on the agency's creation. We could not complete an automated read of the whitelist PDF or a live search on SECP's eServices portal, both blocked by the site's own browser check on our attempt, and we have said so wherever it affects a claim. We did not test whether any specific named app is currently licensed, because that changes with every update to SECP's own list.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.