MCB Home Loan 2026: KIBOR Plus 2% to 3.5%, Up to Rs 50 Million and Rs 10,000 Fee in Pakistan
MCB Home Loan 2026: 6 month KIBOR plus 2% to 3.5% by equity, up to Rs 50 million for 25 years, Rs 75,000 salary rule, Rs 10,000 fee and prepayment charges.
MCB Home Loan, MCB Bank's housing finance in Pakistan, costs 6 month KIBOR plus 2% to 3.5% in 2026, depending on your down payment and whether you are salaried. With 6 month KIBOR at 12.44% on 13 November 2026, that is about 14.44% to 15.94% a year. MCB lends up to Rs 50 million for 2 to 25 years. The processing fee on a standard home loan is up to Rs 10,000.
Salaried applicants need Rs 75,000 net a month and self-employed applicants Rs 100,000. Your total instalments cannot pass half of your net income.
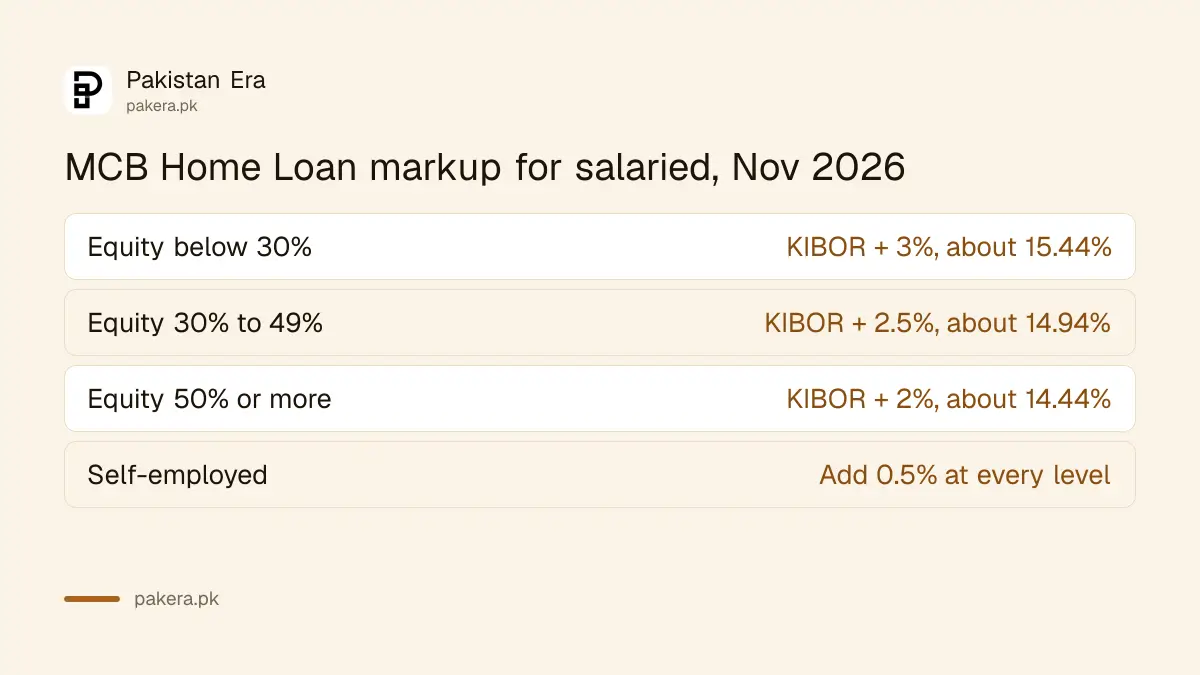
MCB Home Loan markup is 6 month KIBOR plus 2% to 3.5%
The more you put down, the lower the margin. A salaried buyer with less than 30% equity pays 6 month KIBOR plus 3%, and one with half the price in cash pays plus 2%. Self-employed buyers pay half a point more at every level.
| Your equity (down payment) | Salaried | Self-employed |
|---|---|---|
| Below 30% | KIBOR + 3.00%, about 15.44% | KIBOR + 3.50%, about 15.94% |
| 30% to below 50% | KIBOR + 2.50%, about 14.94% | KIBOR + 3.00%, about 15.44% |
| 50% or more | KIBOR + 2.00%, about 14.44% | KIBOR + 2.50%, about 14.94% |
The percentages are our sums on the 12.44% six month offer rate in the KIBOR rates for 13 November 2026. The rate is variable. MCB resets it on the first working day of January and July each year. Only KIBOR changes; your margin stays fixed for the whole loan.
What an MCB home loan costs each month
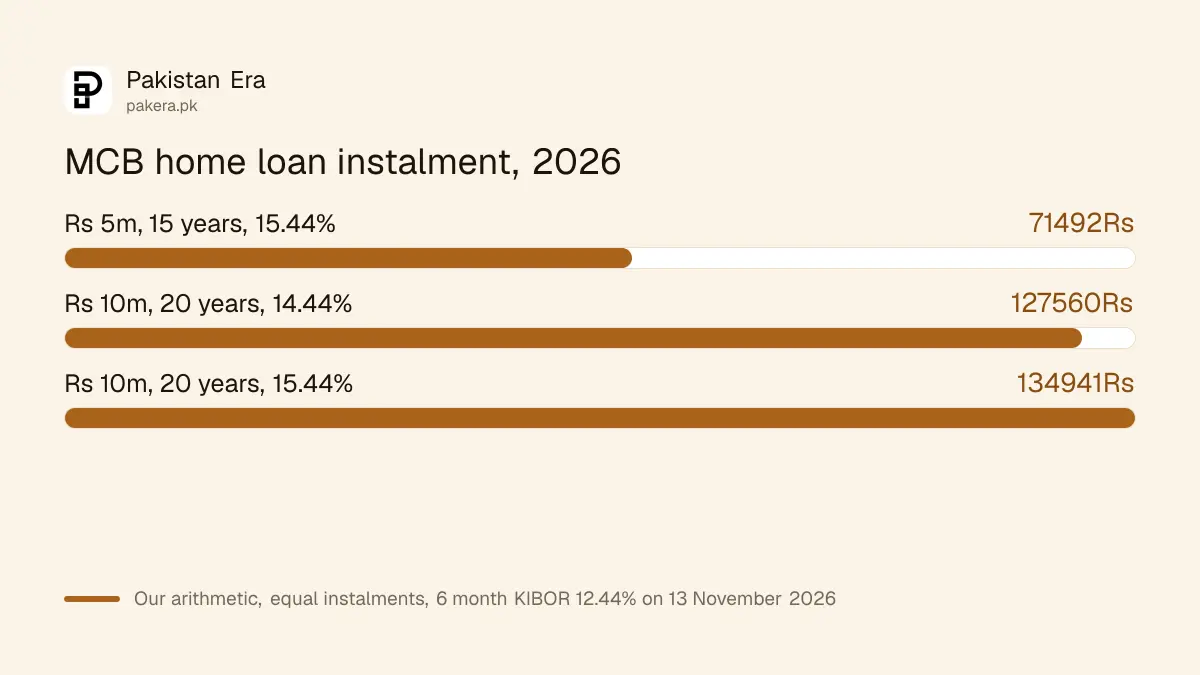
Rs 10 million over 20 years costs about Rs 135,000 a month at 15.44% and about Rs 127,600 at 14.44%. Putting down half the price instead of under 30% saves about Rs 7,400 a month on that loan.
| Loan | Tenure and rate | About a month | Net income needed at 50% |
|---|---|---|---|
| Rs 5,000,000 | 15 years, 15.44% | Rs 71,492 | About Rs 143,000 |
| Rs 10,000,000 | 20 years, 14.44% | Rs 127,560 | About Rs 255,000 |
| Rs 10,000,000 | 20 years, 15.44% | Rs 134,941 | About Rs 270,000 |
| Rs 10,000,000 | 20 years, 15.94% | Rs 138,676 | About Rs 277,000 |
These are our equal instalment sums. MCB's monthly instalment also carries the property insurance premium, so the real bill is a little higher. The income column assumes no other loans. A car loan or card bill counts against the same 50% limit.
How much MCB lends, and for what
MCB finances up to 80% of the value of a house or flat. The ceiling depends on the purpose: Rs 50 million to buy a home or a plot and build on it, Rs 25 million to build, and Rs 15 million to renovate.
| Purpose | Maximum loan |
|---|---|
| Buy a house or flat | Rs 50 million |
| Buy a plot and build | Rs 50 million |
| Build on your own plot | Rs 25 million |
| Balance transfer from another bank | Rs 20 million |
| Renovate your home | Rs 15 million |
The bank values the property and checks your debt burden before it fixes the amount. For a purchase, MCB pays the seller directly. For building or renovation, the money is paid in your name. Building on a plot is its own process, explained in home loans for plot and construction.
Who can apply for an MCB home loan
Salaried people, businessmen, self-employed professionals, landlords and pensioners can apply. The main borrower must be at least 25, a joint borrower at least 22, and both must finish repaying by 65 or retirement age.
- Income: Rs 75,000 net a month salaried, Rs 100,000 self-employed, after tax.
- Experience: 2 years for salaried staff, 3 years in business for the self-employed.
- Bank statements: 6 months for salaried, 12 months for self-employed.
- Debt burden: all monthly instalments together cannot pass 50% of net income.
- Co-borrower: a parent, spouse, brother or adult child, whose income is added to yours.
Documents are the application form, CNIC copy, two photos, a list of all your bank loans, income and job or business proof, and property papers. The general rules for every bank are in home loan eligibility rules.
Overseas Pakistanis can apply too, but only salaried ones, only to buy a house, and only with a local co-borrower who is a blood relative. They need Rs 500,000 net a month or its equivalent, one year of banking history, and a NICOP or POC.
MCB Home Loan processing fee and other charges
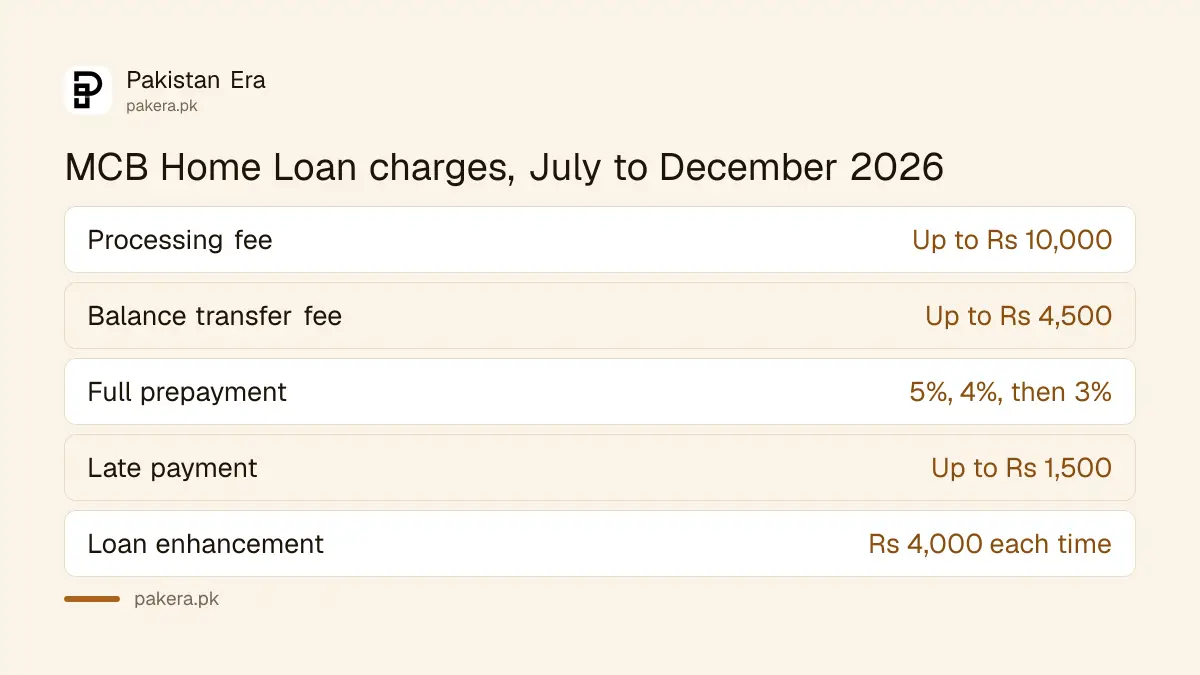
The schedule of charges for July to December 2026 sets the processing fee at up to Rs 10,000 on a standard home loan, and it is not refunded. Legal checks, valuation, income estimation and insurance are paid at actual cost. A late instalment costs up to Rs 1,500.
| MCB Home Loan charge | July to December 2026 |
|---|---|
| Processing fee, standard home loan | Up to Rs 10,000, non-refundable |
| Processing fee, balance transfer | Up to Rs 4,500 |
| Processing fee, overseas Pakistanis | Up to Rs 10,000 |
| Full prepayment | Up to 5%, 4%, then 3% of remaining principal |
| Late payment | Up to Rs 1,500 per instalment |
| Loan enhancement | Rs 4,000 each time |
Two part payments in any 12 months, six months apart, are free if each is at least 5% and together no more than 20% of the balance. Anything beyond that pays the same 5%, 4% and 3% scale. Excise duty is added to fees. Account fees are in the MCB schedule of charges.
How to apply for an MCB home loan
Apply at any MCB branch or one of the 11 customer service centres, or call 111-000-622. MCB has separate application forms for salaried, formal business and informal income applicants, in English and Urdu.
- Pick the right form: green for salaried, blue for formal business, pink for informal income.
- Gather your CNIC, photos, income proof, bank statements and a list of existing loans.
- Get copies of the property papers, such as the title, transfer letter or sale agreement.
- Submit at a branch and pay the processing fee.
- Wait for the legal check, valuation and income estimation, paid at actual.
- Sign the offer and mortgage papers. MCB pays the seller, or pays you for building or renovation.
Property insurance and life insurance on the borrower are both compulsory. Instalments fall due on the first working day of each month. If the bank does not resolve a complaint, take it to the State Bank's Sunwai complaint portal.
Common questions
What is the MCB home loan interest rate in 2026?
6 month KIBOR plus 2% to 3.5%, about 14.44% to 15.94% on mid November 2026 KIBOR. The margin falls as your down payment rises.
How much home loan can I get from MCB?
Up to Rs 50 million to buy a house or a plot with construction, Rs 25 million to build, and Rs 15 million to renovate.
What is the minimum salary for an MCB home loan?
Rs 75,000 net a month for salaried applicants and Rs 100,000 for the self-employed.
What is the MCB home loan processing fee?
Up to Rs 10,000 for a standard home loan, non-refundable, plus excise duty. Legal and valuation costs are extra.
Can overseas Pakistanis get an MCB home loan?
Yes, if salaried, buying a house, earning Rs 500,000 a month or its equivalent, and applying with a local blood relative as co-borrower.
When does the MCB home loan rate change?
On the first working day of January and July. Only KIBOR moves; your margin stays the same.
How we verified this
What we checked and where we read it.
We read MCB Bank's MCB Home Loan page, its pricing sheet, home loan FAQs and housing finance key fact statement (dated 3 November 2025), and the consumer banking section of the schedule of bank charges for July to December 2026, on 15 November 2026. The product page shows the equity bands without their symbols; the separate pricing sheet gives them as below 30%, 30% to below 50%, and 50% or more. KIBOR is the State Bank's 6 month offer rate for 13 November 2026. Rates in percent, instalments and income figures are our arithmetic.
About the author
Tax, Bills and Technology Writer
Ali Akhtar is a young and curious voice here at Pakistan Era. He is currently pursuing his A-Levels and has a growing interest in Pakistan’s changing industrial landscape and educational trends. Ali likes to write in a way that helps him explain and explore the world around him. His writing reflects the perspective of the new generation navigating the evolving trends of Pakistan where technology, youth innovation, and shifting opportunities are reshaping the country’s future.