Home Loan to Build a House in Pakistan: 8 Lenders, Stages and Apna Ghar at 5%
Banks in Pakistan lend to build on your plot or buy a plot and build. Compare 8 lenders, stage payments, your share and Apna Ghar at 5% for 10 years. Check now.
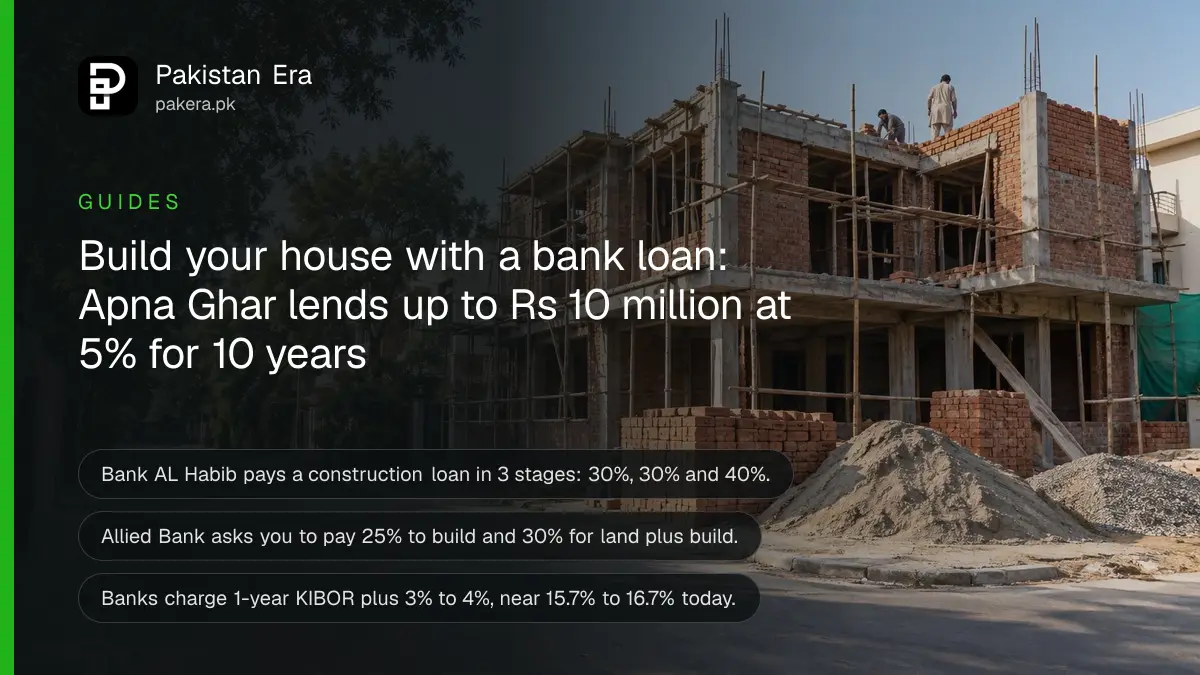
You can get a bank loan to build a house in Pakistan, either on a plot you already own or to buy a plot and build on it. Bank AL Habib, Allied Bank, Meezan, Bank Alfalah, MCB, JS Bank, HBFC and Dubai Islamic all offer it. The bank pays the builder money in stages, not in one go. First-time owners can get up to Rs 10 million at a fixed 5% for 10 years under Apna Ghar.
We read each bank's own product page and the State Bank's housing finance rules on 6 and 7 October 2026. The 2026 rules list "construction of a house on a plot already owned" and "purchase of a plot and construction of a house thereon" as allowed purposes for a home loan. So this is a normal product, not a favour.
The catch is the paperwork and the cash you need up front. A construction loan asks more of you than a loan to buy a finished house.
Banks that lend to buy a plot and build in 2026
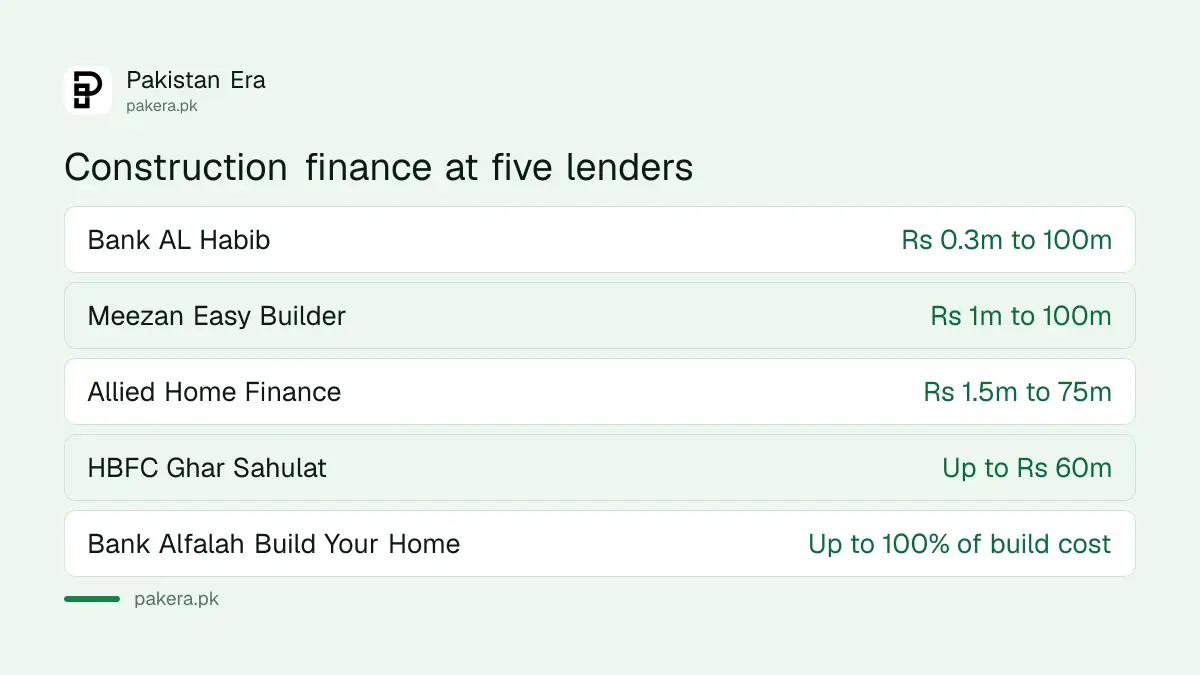
Eight lenders we checked offer construction finance on their own pages. Limits run from Rs 300,000 at Bank AL Habib to Rs 100 million at Meezan and Bank AL Habib. Most price the loan at 1-year KIBOR plus 3% to 4%, which works out near 15.7% to 16.7% a year today.
| Lender and product | Construction amount | Your share or bank's share | Tenure | Price |
|---|---|---|---|---|
| Bank AL Habib Housing Finance | Rs 0.3m to 100m (plot plus build), Rs 0.3m to 50m (build only) | Not stated | 1 to 25 years | KIBOR + 3% salaried, + 3.5% others |
| Allied Home Finance | Rs 1.5m to 75m | You pay 25% (build), 30% (land plus build) | 3 to 25 years | KIBOR + 1.75% to 5% |
| Meezan Easy Builder | Rs 1m to 100m | Bank up to 75% salaried, 70% businessmen | 2 to 25 years | KIBOR + 3% salaried, + 4% business |
| Bank Alfalah Plot and Build | No fixed limit | Bank up to 80% of total home value | 3 to 25 years | KIBOR + 3% salaried, + 4% others |
| Bank Alfalah Build Your Home | No fixed limit | Up to 100% of construction cost | 3 to 25 years | KIBOR + 3% salaried, + 4% others |
| HBFC Ghar Sahulat | Up to Rs 60m | Bank up to 85% | 3 to 20 years | KIBOR + 3% salaried, + 3.5% self-employed |
| Dubai Islamic Construction Finance | Rs 0.5m to 50m | Bank up to 70% (home finance) | Up to 20 years | Margin not published |
| MCB Home Loan and JS GharApna | Up to Rs 50m (MCB), Rs 100m (JS) | JS up to 80% | MCB 2 to 25, JS 1 to 25 years | MCB 6-month KIBOR + 2% to 3.5%, JS KIBOR + 3% to 4.25% |
KIBOR means the Karachi Interbank Offered Rate, the benchmark banks add their margin to. The 1-year KIBOR stood at 12.68% on 5 October 2026. HBL no longer lists a resident home loan on its loans page, and we could not read Faysal Bank's site.
The bank pays a construction loan in stages
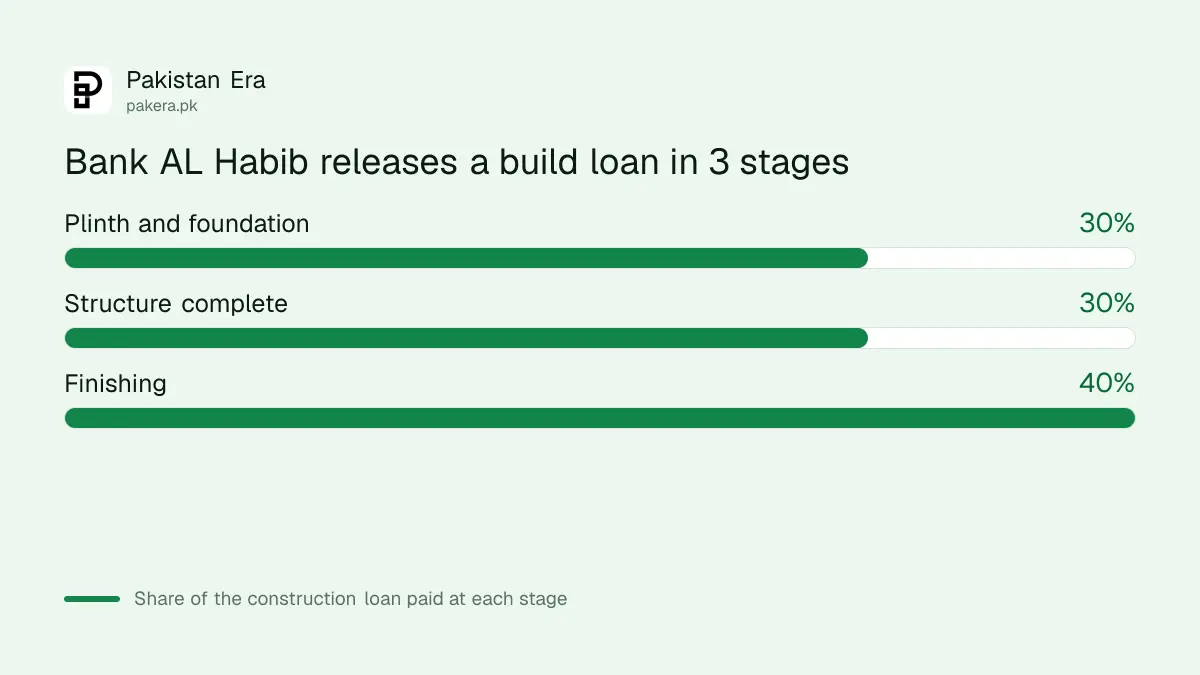
A construction loan is released in parts as the house goes up. Bank AL Habib pays 30% at plinth and foundation, 30% when the structure is done and 40% at finishing. Bank Alfalah pays construction money in 4 equal tranches.
Before each payment, the bank checks the work. BankIslami's schedule of charges lists Rs 3,000 to verify your bill of quantities (BOQ, the builder's itemised cost list) and Rs 3,000 for each tranche visit. So budget for several site visits, not one.
Stages protect the bank, but they squeeze you. If the builder needs cash before the next inspection, it comes from your pocket. Keep 10% to 15% of the build cost aside for that gap. That figure is our own suggestion, not a bank rule.
How much of the cost you must pay yourself
The State Bank allows banks to lend up to 90% of the property value, but most banks lend less. Allied Bank asks you to pay 25% for construction and 30% if the loan also buys the land. Meezan and Bank Alfalah lend up to 75% and 80%.
The State Bank's 2026 rules also cap your total instalments, this loan plus any car loan or card, at 65% of your net disposable income, and allow up to 30 years. Banks set tighter limits of their own. Bank AL Habib's cap is 50% of income, and no bank we read offers more than 25 years. The rules banks use to decide your home loan apply here in full.
Your plot can count as your share. Bank Alfalah's Build Your Home finances up to 100% of the construction cost on a plot you own, and its Home Secure option lets you mortgage a family house or plot instead of paying equity. Ask how the bank values the land before you assume this.
Apna Ghar lends Rs 10 million at 5% to build
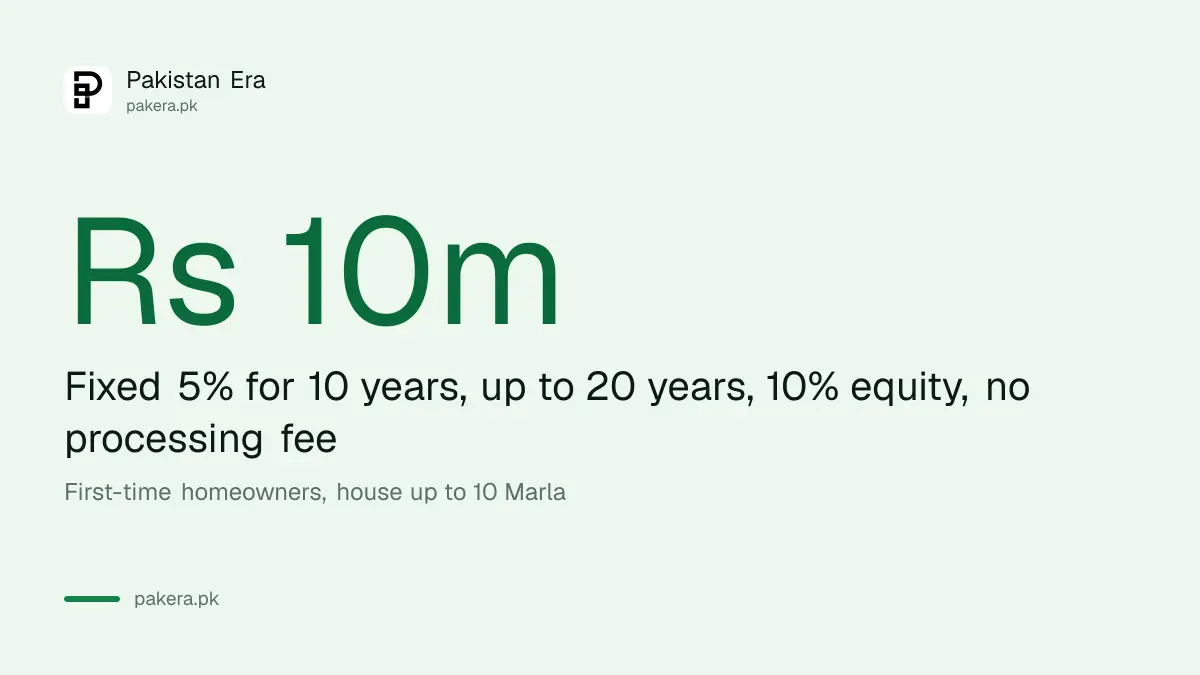
The Apna Ghar scheme covers construction on a plot you own and buying a plot to build on. First-time homeowners can borrow up to Rs 10 million at a fixed 5% for the first 10 years, over up to 20 years, with 10% equity and no processing fee.
- You must hold a CNIC and own no housing unit in your name.
- The house can be up to 10 Marla or 2,720 sq ft. A flat can be up to 1,500 sq ft.
- After year 10, the rate becomes 1-year KIBOR plus 3%.
- There is no prepayment penalty.
- Bank staff are not eligible, under a State Bank letter of 14 September 2026.
JS Bank asks for a monthly income of at least Rs 40,000 and HBFC Rs 50,000. You apply for the Apna Ghar loan at any participating commercial bank, Islamic bank, microfinance bank or HBFC. In Punjab, the separate Apni Chhat Apna Ghar loan is interest free.
The monthly instalment on Rs 6 million over 20 years
On Rs 6 million over 20 years, Apna Ghar's 5% costs about Rs 39,597 a month for the first 10 years. A bank loan at 1-year KIBOR plus 3%, or 15.68% today, costs about Rs 82,038 a month. That is more than double.
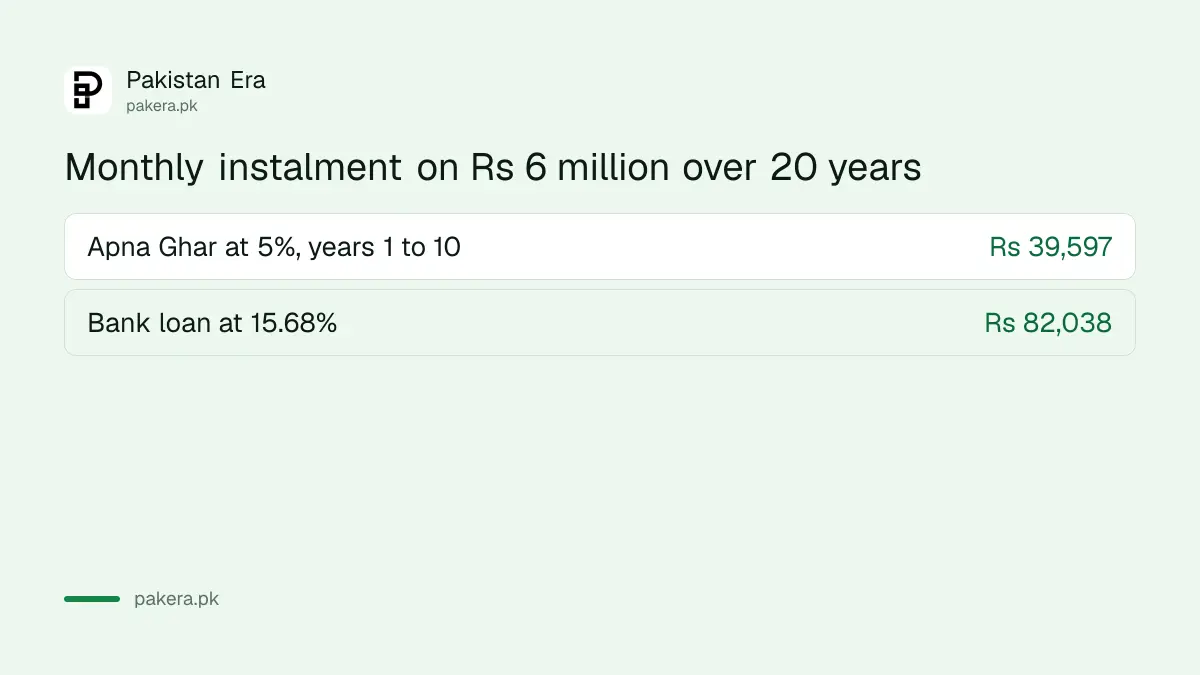
These are our own figures with a standard monthly instalment formula. A bank loan resets once a year with KIBOR, so the instalment can rise or fall. You can test your own amount, rate and term on the home loan calculator.
At Rs 82,038 a month, the 50% cap at Bank AL Habib means a take-home income of roughly Rs 164,000. That is why many families build in two steps: the structure first with savings, and a smaller loan for finishing.
How to apply for a construction loan, step by step
The order matters. Sort out the land and the plan before you approach a bank, because the bank's lawyer checks the title before any money moves.
- Confirm your plot has clear title, and if you are buying one, check the housing scheme is approved.
- Get your building plan approved by your development authority, such as the LDA in Lahore.
- Get a builder's bill of quantities and a construction timeline.
- Apply at the bank with your CNIC, income proof and property papers.
- Wait for the legal opinion and the bank's valuation of the plot.
- Sign the finance documents and register the mortgage on the plot.
- Build to each stage and call the bank for the inspection before each tranche.
We did not find an approved-plan requirement written on the bank pages we read. But an unapproved house is a risk to you and the bank alike, and authorities can seal it.
Common questions
Can I get a home loan to build on my own plot in Pakistan?
Yes. The State Bank's 2026 rules allow it, and Bank AL Habib, Allied, Meezan, Bank Alfalah, MCB, JS Bank and HBFC offer it.
Does Apna Ghar cover construction?
Yes. It covers building on a plot you own and buying a plot to build on, up to Rs 10 million at 5% for 10 years.
How is a construction loan paid out?
In stages after inspections. Bank AL Habib pays 30%, 30% and 40%, and Bank Alfalah pays 4 equal tranches.
How much down payment do I need to build a house with a bank loan?
Usually 20% to 30%. Allied asks 25% for building and 30% for land plus building.
What is the longest tenure for a construction loan?
25 years at most banks we read, and 20 years under Apna Ghar and at HBFC.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on 7 October 2026. Purposes, the 90% limit, the 65% income cap and the 30-year tenure come from the State Bank's Housing Finance Prudential Regulations 2026, issued with SH&SFD Circular 04 of 18 August 2026. Apna Ghar terms come from State Bank circulars and letters of 2025 and 2026 and the scheme pages of HBFC, JS Bank and Bank Alfalah. Bank terms come from the home finance pages of Bank AL Habib, Allied Bank, Meezan Bank, Bank Alfalah, MCB, JS Bank, HBFC and Dubai Islamic Bank, and BankIslami's schedule of charges for January to June 2026. KIBOR is from the State Bank home page on 6 October 2026.
About the author
Public Services and Education Journalist
Fajr Riaz is a journalist and content writer at Pakistan Era, based in Lahore. She covers the questions people meet in everyday life in Pakistan: how a public service works, what a change in the rules means, and where to find a reliable answer.