How to Open a Teenager Bank Account in Pakistan, Ages 13 to 18
Ages 13 to 18 can open a bank account or wallet under SBP rules, with a parent signing an indemnity. See the rules, steps and limits, then ask your bank.
A teenager aged 13 to 18 can now open a bank account or mobile wallet in Pakistan under a State Bank framework, with a parent or guardian signing an indemnity. The bank must open it within two working days of getting all requirements.
The account is in rupees only, is a savings account unless the teenager asks for something else, and comes with a debit card and app banking. There is no cheque book and no credit.
We read the State Bank of Pakistan circular, BPRD Circular No. 01 of 2026 dated 1 April 2026, on sbp.org.pk on 8 October 2026. The circular tells banks what they must offer. It does not name banks or fees, so check your own bank for those.
The State Bank allows accounts for teenagers aged 13 to 18
The framework covers resident Pakistani teenagers from 13 to 18. It applies to all banks, microfinance banks and electronic money institutions, which are the companies behind most mobile wallets. The aim, the circular says, is financial inclusion and a habit of saving.
The account opens in the teenager's own name, alone or jointly. The circular does not say who a joint holder may be, so ask your bank whether a parent can be added.
It can also receive the rupee equivalent of foreign remittances. That helps if a relative abroad wants to send money to a young family member.
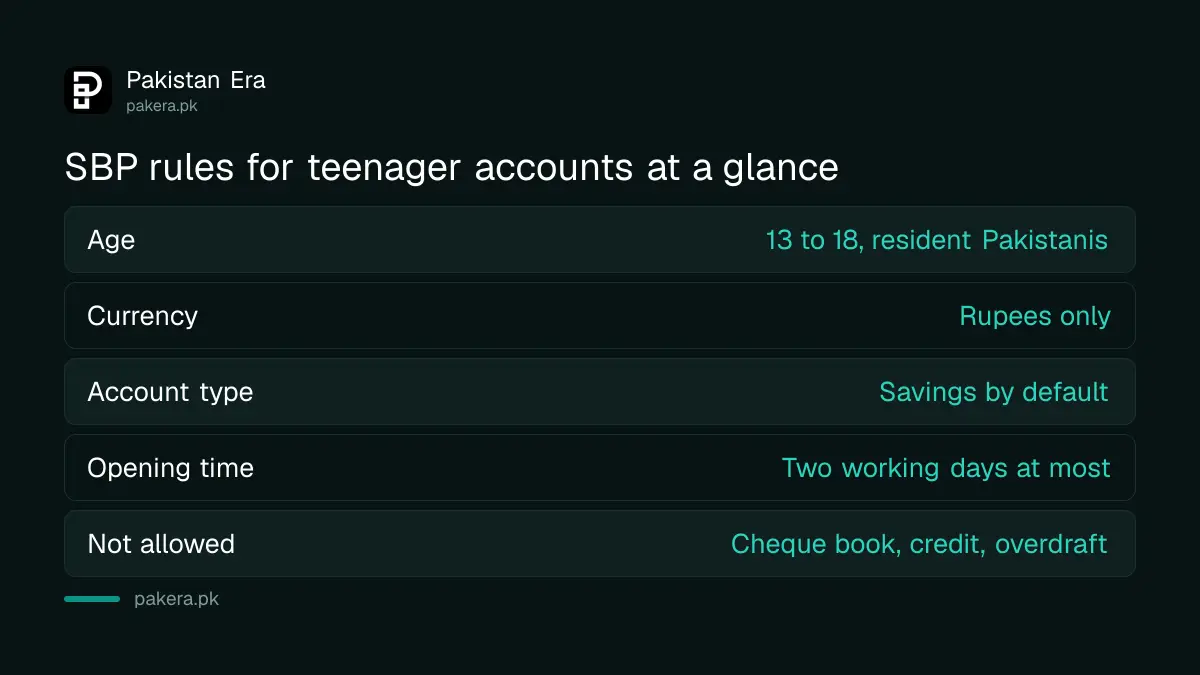
| Feature | What the State Bank requires |
|---|---|
| Age | 13 to 18, resident Pakistanis |
| Currency | Rupees only |
| Account type | Savings by default |
| Opening time | Instant once complete, never over 2 working days |
| Cards and apps | Debit card and online or app banking |
| Not allowed | Cheque book, credit and overdraft |
The parent signs an indemnity and declares the source of funds
The parent or guardian must accept full legal responsibility for the account through an indemnity, signed digitally or on paper. They must also declare the source of funds. The parent goes through the normal checks banks run on any adult customer.
For the teenager, the bank uses biometric verification where it applies, or another way of confirming identity through NADRA. The circular does not list documents. So ask your bank which paper it wants for a young person, such as a B-form or a CNIC.
The bank will also screen names and risk profile the customer, and watch transactions under the State Bank's anti money laundering rules. This is standard for every account. It does not mean something is wrong.
The circular adds that the older instructions on minor accounts still apply. If your child is under 13, opening a bank account for a child is the route.
You can apply in a branch or from your phone
Banks can open a teenager account in person or remotely, through any digital means. The bank must give the applicant a tracking number so they can check the status. The circular says opening must be instant once everything is complete, and never later than two working days.
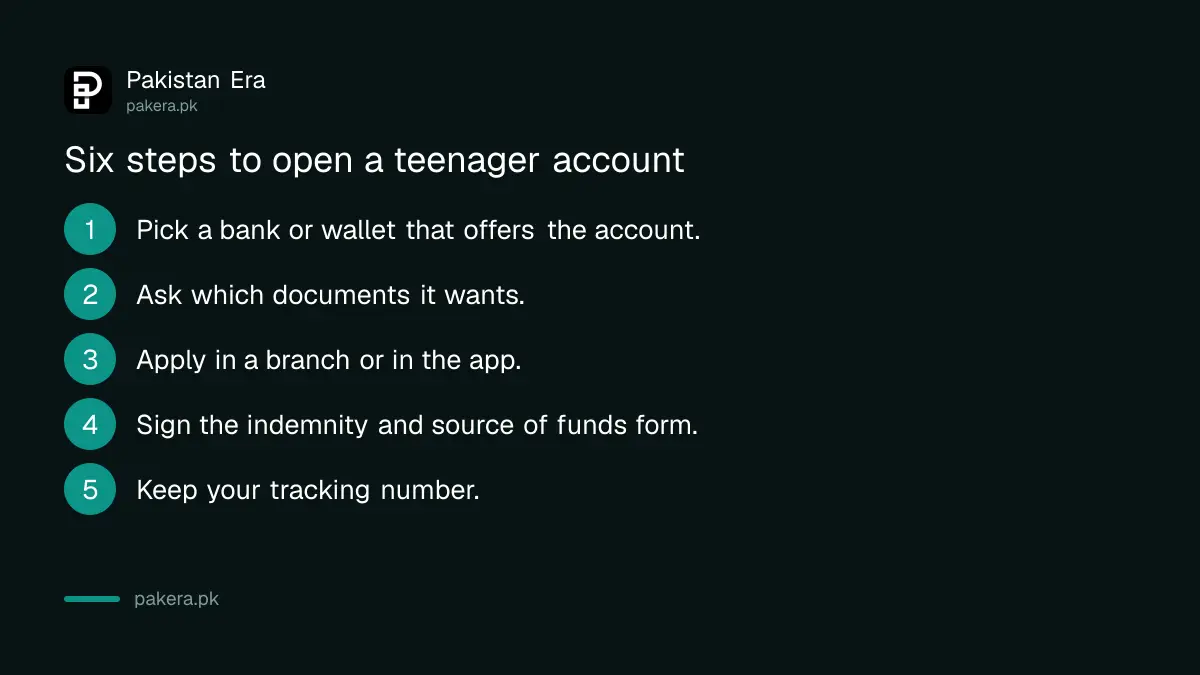
- Choose a bank, microfinance bank or wallet company that offers a teenager account.
- Ask which documents it wants for the teenager and for you.
- Apply in a branch or in the app, with your child present for identity checks if asked.
- Sign the indemnity and the source of funds declaration.
- Keep the tracking number the bank gives you.
- Check for the debit card and app login within two working days.
Not every bank has launched a product yet. We have not checked every bank. The circular does tell banks to run awareness campaigns about the account, so more products should follow. If yours has nothing yet, ask when it will.
Profit rates and fees are set by each bank
The circular says nothing about profit rates, annual card fees or minimum balances. Those are your bank's choice. Compare them before you open the account, because a high fee can cancel the small profit a teenager earns on pocket money.
Our October rates page shows one bank paying 10.25 per cent a year on its teenager account, up to Rs 10 million. See savings account profit rates in Pakistan in October 2026 for the bank and the conditions. Rates change, so check again before you apply.
Card fees also vary. The page on debit card annual fees by bank helps you compare, though it covers ordinary cards, not teenager products.
The account becomes a regular account at 18
When the teenager reaches the age of majority, the same account converts into a regular account or wallet, once the usual requirements are met. That means a cheque book and other services become possible later, after the bank completes its checks.
The circular does not say what the bank will ask for at that point. Expect a fresh identity check with the adult's own CNIC. Keep the account details and your tracking number from the start, so nothing gets lost at the switch.
If a bank refuses to open the account or delays it past two working days, complain in writing. Then use the State Bank's Sunwai complaint portal if you get no answer.
Common questions
What age can a teenager open a bank account in Pakistan?
The State Bank framework covers resident Pakistani teenagers aged 13 to 18. Younger children use minor accounts.
Does the teenager need a parent?
Yes. The parent or guardian signs an indemnity accepting full legal responsibility and declares the source of funds.
Can a teenager get a cheque book or credit card?
No. The circular bars cheque books, other negotiable instruments, credit and overdraft on these accounts.
How long does opening take?
It should be instant once all requirements are met. The circular sets a maximum of two working days.
Can a teenager receive money from abroad?
Yes, in rupees. The account may receive the rupee equivalent of foreign remittances.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 8 October 2026. We read the State Bank of Pakistan's BPRD Circular No. 01 of 2026, titled Teenager Account / Wallet and dated 1 April 2026, on sbp.org.pk. All rules on age, currency, onboarding, the two day limit, verification, the parent's indemnity, barred services and conversion at majority come from that circular. We did not check what individual banks offer or charge. The profit rate mentioned comes from our own rates page, not from the circular. Confirm products, fees and documents with your bank.
About the author
Public Services and Education Journalist
Fajr Riaz is a journalist and content writer at Pakistan Era, based in Lahore. She covers the questions people meet in everyday life in Pakistan: how a public service works, what a change in the rules means, and where to find a reliable answer.