PM Youth Loan Instalment Calculator 2026: Monthly Payment for Every Tier, Rs 0.5 Million to Rs 25 Million
PM Youth Loan monthly instalment for every tier, from Rs 0.5 million at 0% to Rs 25 million at 8%. Tables for 3, 5 and 8 years, total markup and the formula.
یہ صفحہ اردو میں پڑھیں
Short answer: A Rs 25 million PM Youth Loan at 8 per cent over 8 years costs about Rs 353,417 a month, and about Rs 8.9 million in markup in total. A Rs 0.5 million Tier 1 loan has no markup, so over 5 years it is Rs 8,333 a month. Find your amount in the tables below, then confirm the schedule with your bank.
The Prime Minister's Youth Business and Agriculture Loan Scheme raised its top limit to Rs 25 million on 10 November 2026, with a new Tier 4 at 8 per cent. Read our news report on the Rs 25 million limit for what changed. This guide answers the next question every applicant asks: what will I pay each month?
We worked out every figure ourselves using the standard reducing balance formula that banks use for term loans. The markup rates are the scheme's own, from the government's 10 November 2026 release. Your bank's real schedule may differ because of a grace period, insurance or processing charges.
The markup for each tier sets your monthly payment
Your instalment depends on three things: the amount, the markup rate and the number of months. The rate is fixed by tier. Here are the rates the scheme uses from 10 November 2026.
| Tier | Loan amount | Markup a year |
|---|---|---|
| Tier 1 | Up to Rs 0.5 million | 0 per cent |
| Tier 2 | Rs 0.5 million to Rs 1.5 million | 5 per cent |
| Tier 3 | Rs 1.5 million to Rs 7.5 million | 7 per cent |
| Tier 4 | Rs 7.5 million to Rs 25 million | 8 per cent, up to 8 years |
The 10 November release states the 8 year limit only for Tier 4. It does not give the maximum term for Tiers 1 to 3. So for those, we show 3 and 5 year terms as examples. Ask your bank for the term it will offer you.
Monthly instalments for Tiers 1, 2 and 3
These are the smaller loans. Most borrowers take Tier 1: the government expects about three in four of this year's borrowers to be Tier 1.
| Loan | Rate | 3 years: monthly | 3 years: total markup | 5 years: monthly | 5 years: total markup |
|---|---|---|---|---|---|
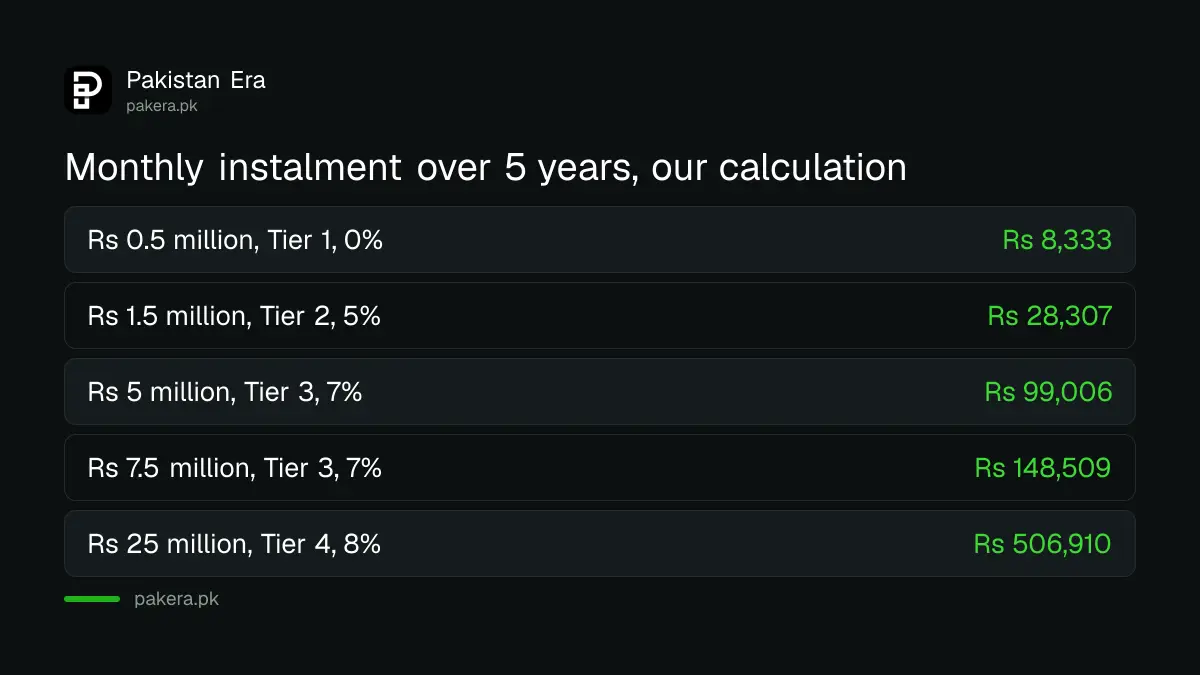
| Rs 0.5 million (Tier 1) | 0% | Rs 13,889 | Rs 0 | Rs 8,333 | Rs 0 |
| Rs 1 million (Tier 2) | 5% | Rs 29,971 | Rs 78,952 | Rs 18,871 | Rs 132,274 |
| Rs 1.5 million (Tier 2) | 5% | Rs 44,956 | Rs 118,428 | Rs 28,307 | Rs 198,411 |
| Rs 3 million (Tier 3) | 7% | Rs 92,631 | Rs 334,726 | Rs 59,404 | Rs 564,216 |
| Rs 5 million (Tier 3) | 7% | Rs 154,385 | Rs 557,877 | Rs 99,006 | Rs 940,360 |
| Rs 7.5 million (Tier 3) | 7% | Rs 231,578 | Rs 836,816 | Rs 148,509 | Rs 1,410,539 |
Monthly instalments for Tier 4, Rs 10 million to Rs 25 million
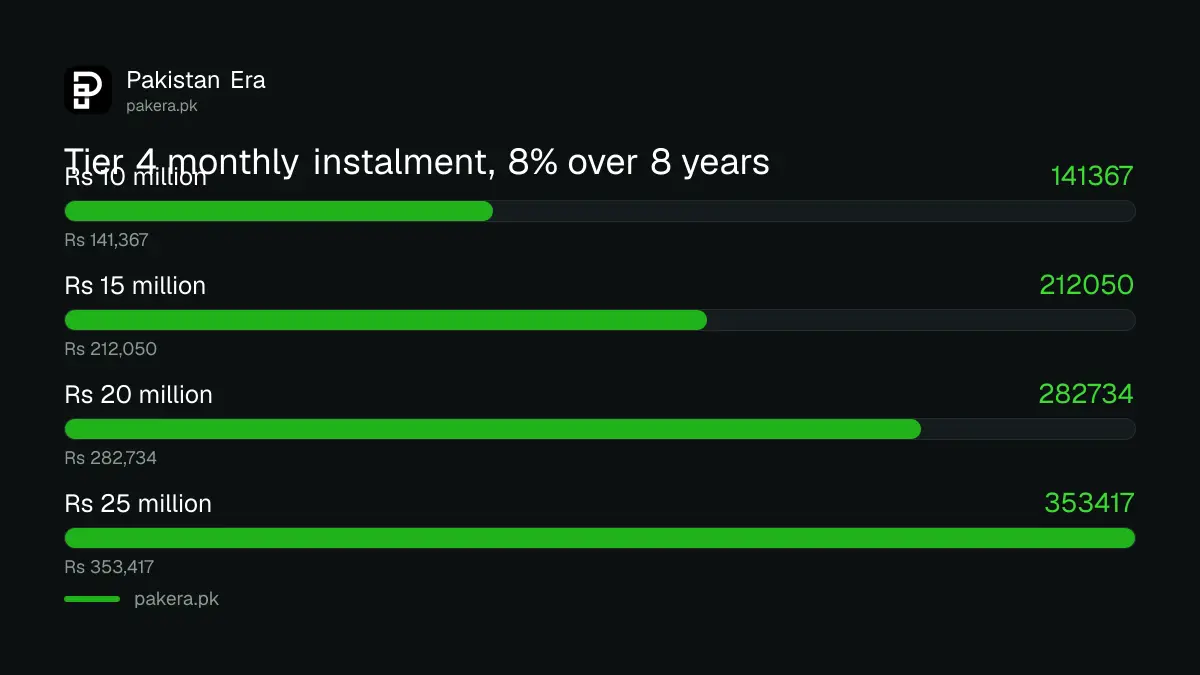
Tier 4 is new. It starts above Rs 7.5 million and runs to Rs 25 million, at 8 per cent. The scheme allows up to 8 years, so we show 5 and 8 year terms.
| Loan | 5 years: monthly | 5 years: total markup | 8 years: monthly | 8 years: total markup |
|---|---|---|---|---|
| Rs 10 million | Rs 202,764 | Rs 2,165,837 | Rs 141,367 | Rs 3,571,212 |
| Rs 15 million | Rs 304,146 | Rs 3,248,755 | Rs 212,050 | Rs 5,356,818 |
| Rs 20 million | Rs 405,528 | Rs 4,331,673 | Rs 282,734 | Rs 7,142,424 |
| Rs 25 million | Rs 506,910 | Rs 5,414,591 | Rs 353,417 | Rs 8,928,030 |
Look at the trade off in the last row. Stretching Rs 25 million from 5 to 8 years cuts the monthly bill by about Rs 153,000. But it adds about Rs 3.5 million in markup. A longer term is easier each month and costs more overall.
Work out your own instalment in five steps
If your amount is not in the tables, you can work it out on a phone calculator or in a spreadsheet. This is the method we used.
- Find your yearly rate from your tier, for example 8 per cent, and divide by 12. That gives 0.006667 a month.
- Count the months. Eight years is 96 months.
- In a spreadsheet, type =PMT(8%/12, 96, -25000000). Change the three numbers to yours.
- The result is your monthly instalment. For Rs 25 million it shows 353,417.
- Multiply the instalment by the months and take away the loan. That is your total markup.
For a Tier 1 loan at 0 per cent, just divide the loan by the months. Rs 500,000 over 60 months is Rs 8,333.
What can change the figure your bank gives you
Treat these tables as a planning guide. The bank's own repayment schedule is the one you will sign. These are the usual reasons it differs:
- Grace period. Some business loans start repayment after a few months. Markup may build up in that time.
- Insurance and charges. Banks may add life or asset insurance, or a processing fee.
- Equity. If the bank asks you to put in part of the cost yourself, the loan amount, and so the instalment, is lower.
- Late payment. Missing an instalment can add charges and hurt your credit record.
The scheme's markup rate is what you pay. The government pays the bank's margin above that. For Tiers 3 and 4, that margin drops from KIBOR plus 3 per cent to KIBOR plus 2.4 per cent from 10 November 2026, but the release says borrower rates stay the same.
Can your business carry the instalment?
A simple test: your business's monthly profit, after all costs, should be well above the instalment. A Rs 25 million loan over 8 years needs about Rs 353,000 every month, before anything for you or your family. If the plan only works in a good month, borrow less.
Apply only for what you can repay. Our guide on how to apply for the PM Youth Business Loan explains the form and what the bank checks. Farmers wanting a small loan through a specialist bank can also compare the ZTBL Asan Qarza youth loan.
Common questions
What is the monthly instalment on a Rs 25 million PM Youth Loan?
About Rs 353,417 over 8 years at 8 per cent, or about Rs 506,910 over 5 years, on our calculation.
Is there any markup on a Tier 1 loan?
No. Tier 1, up to Rs 0.5 million, is at 0 per cent. You repay only the amount borrowed.
What is the longest term for Tier 4?
Up to 8 years, according to the government's 10 November 2026 release.
Why is my bank's figure different from this table?
Grace periods, insurance, fees and equity all change the schedule. The bank's signed schedule is the one that applies.
How much total markup will I pay on Rs 10 million over 8 years?
About Rs 3.57 million, on top of the Rs 10 million, at 8 per cent.
Can I repay early?
Ask your bank. Early repayment terms are set in the loan agreement, and the release does not cover them.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 10 November 2026. Tiers and markup rates are from PID Press Release No. 97 of 10 November 2026 on pid.gov.pk. Every instalment and markup figure is our own calculation using the standard reducing balance formula, rounded to the nearest rupee. They are not bank quotes.
About the author
Global Affairs & Political Economy Writer
Muhammad Hatim is a book lover who started writing because he enjoys it. At Pakistan Era he writes about international relations, geopolitics and the global economy, with a particular interest in South Asia and the forces behind current events.