How to Apply for the ZTBL Kissan Khushhal Revolving Loan of Rs 2.5 Million
ZTBL's Kissan Khushhal Scheme gives farmers a revolving limit of up to Rs 2.5 million for three years. See the fees, markup dates, papers and steps to apply.
ZTBL's Kissan Khushhal Scheme (KKS) gives a farmer a revolving credit limit of up to Rs 2.5 million on one set of papers for three years. You can withdraw and repay many times a year. The bank charges markup only on the principal still outstanding, plus listed fees such as Rs 200 for documents.
A farmer who borrows for seed in October and again for fertiliser in January normally signs new papers each time. That costs days and fees. KKS is the bank's answer: sign once, then draw money as the crop needs it. We read the Kissan Khushhal Scheme page on ZTBL's website on 15 October 2026. Every term below comes from it. The page gives no markup percentage, so we quote none.
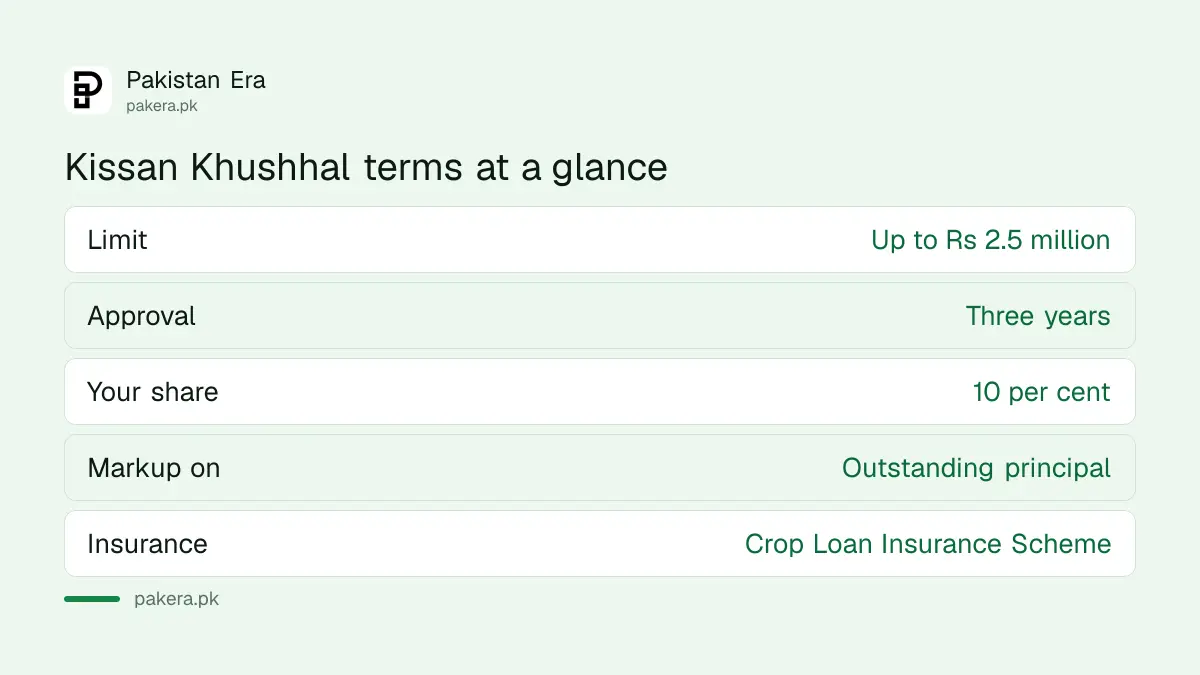
KKS is a revolving limit of up to Rs 2.5 million approved for three years
ZTBL approves the limit for three years, up to Rs 2.5 million per borrower or party. The system enters it one year at a time, and expiry falls on the last working day of the previous month, such as 28 February.
The scheme serves the working-capital and input needs of eligible new and existing farmers across the country. Documentation is done once. The Credit Review Department at head office sanctions the limit, so the branch only collects the file.
| Term | What ZTBL's page says |
|---|---|
| Limit | Up to Rs 2.5 million per borrower or party |
| Approval period | Three years, entered in the system one year at a time |
| Your share | 10 per cent of project cost |
| Security | Agricultural land, shown by passbook or Fard Jamabandi |
| Insurance | As per the Crop Loan Insurance Scheme |
You can draw and repay as often as you need inside the limit
Under KKS you present a cheque against your sanctioned limit and the branch pays it through your KKS account. You may make many withdrawals and many repayments during the year. Money you repay becomes available again, as long as the limit has not expired.
This is why markup falls when you repay early. The page says only the outstanding principal attracts markup. If you clear the whole loan, the branch charges the full accrued markup at that point. Plan withdrawals around real costs, because every rupee drawn starts to cost you from the day you take it.
Fees are listed, so ask the branch to show them in writing
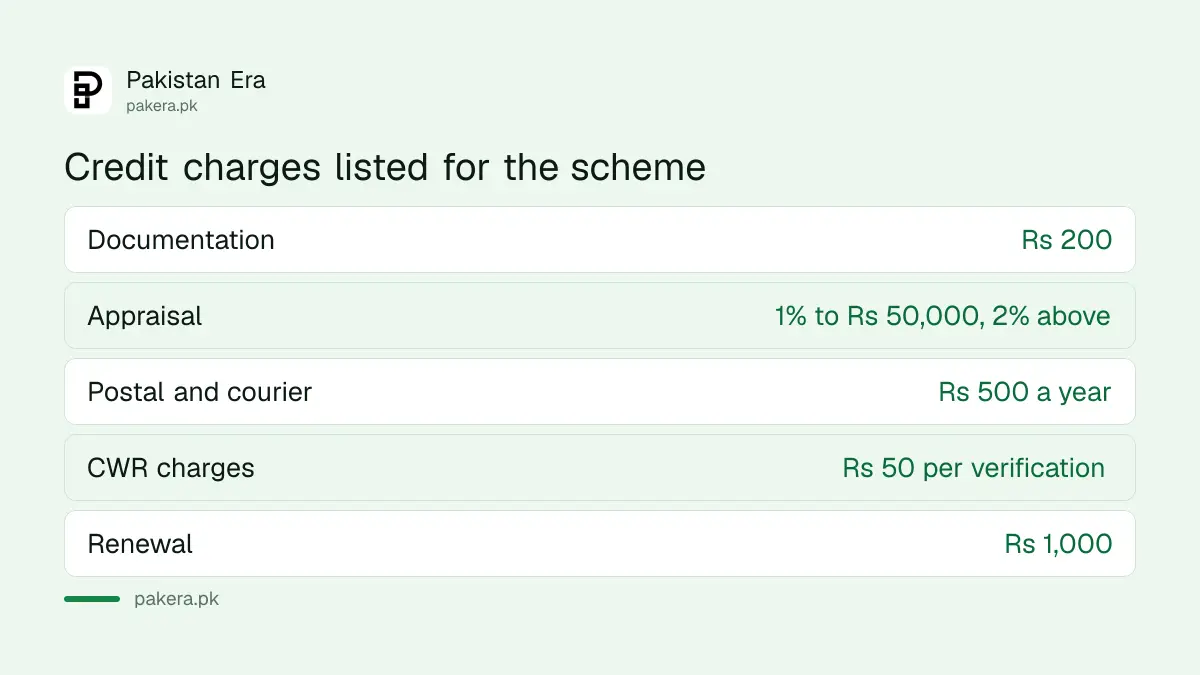
The page lists five charges: Rs 200 for documents, an appraisal fee of 1 per cent up to Rs 50,000 and 2 per cent above, Rs 500 a year for postal costs, Rs 50 per CWR verification or renewal, and Rs 1,000 per renewal.
| Charge | Amount on ZTBL's page |
|---|---|
| Documentation fee | Rs 200 |
| Appraisal fee | 1% up to Rs 50,000, 2% above Rs 50,000 |
| Postal and courier | Rs 500 a year |
| CWR charges | Rs 50 per borrower on each verification or renewal |
| Renewal charges | Rs 1,000 per renewal |
The appraisal line is short, and the page does not say whether the two rates apply to slices of the loan or to the whole amount. Do not guess. Ask the branch to write down the appraisal fee for your exact limit before you sign.
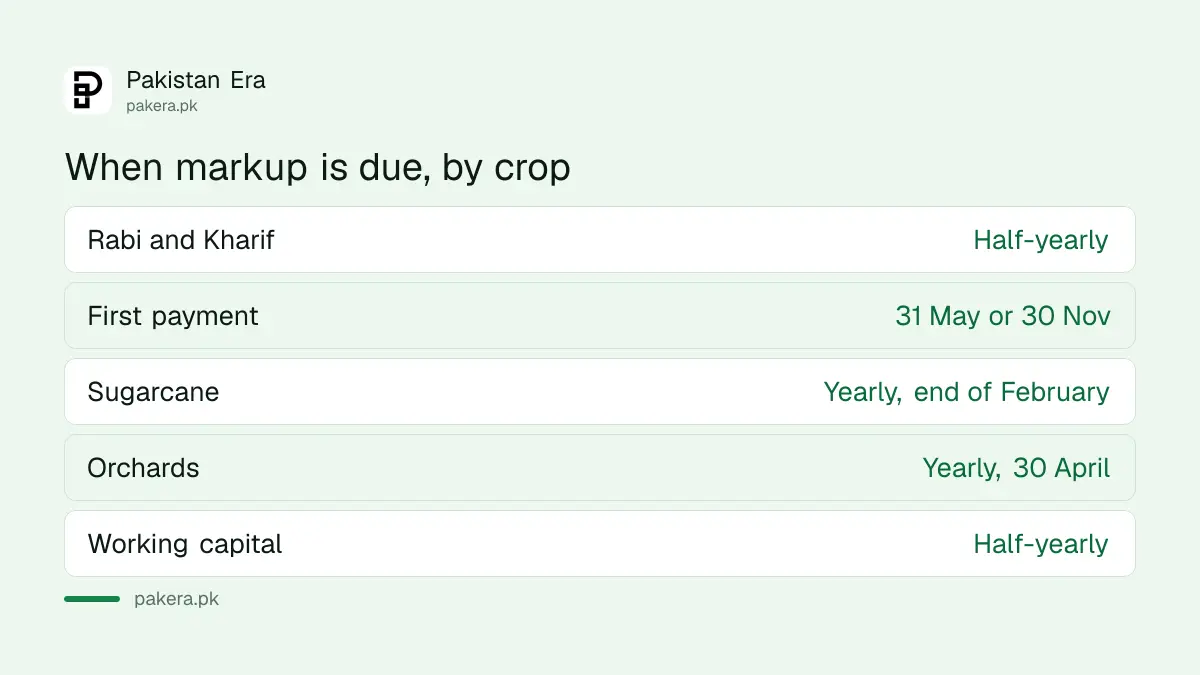
Markup is paid on a crop schedule, and principal once a year
Markup on Rabi and Kharif crops is paid half-yearly, first due on 31 May or 30 November, whichever is earlier. Sugarcane pays by end February and orchards on 30 April. Principal is paid yearly, on the last working day of the previous month.
Put these dates in your phone. The page lists no late-payment rule in this section, but a missed date can affect your standing with the bank.
Insurance and rescheduling protect you if a disaster hits the crop
ZTBL says insurance is arranged under its Crop Loan Insurance Scheme. If a natural calamity hurts the crop and your income, the bank can reschedule the loan under its policy and must tell you the new schedule, with your signed acknowledgement.
Know how a claim works before you need one. The steps are in the guide to how to claim crop loan insurance. Rescheduling is not automatic, so ask the branch in writing as soon as the damage happens. Punjab farmers can also compare this with the subsidy in the Punjab Kissan Card scheme.
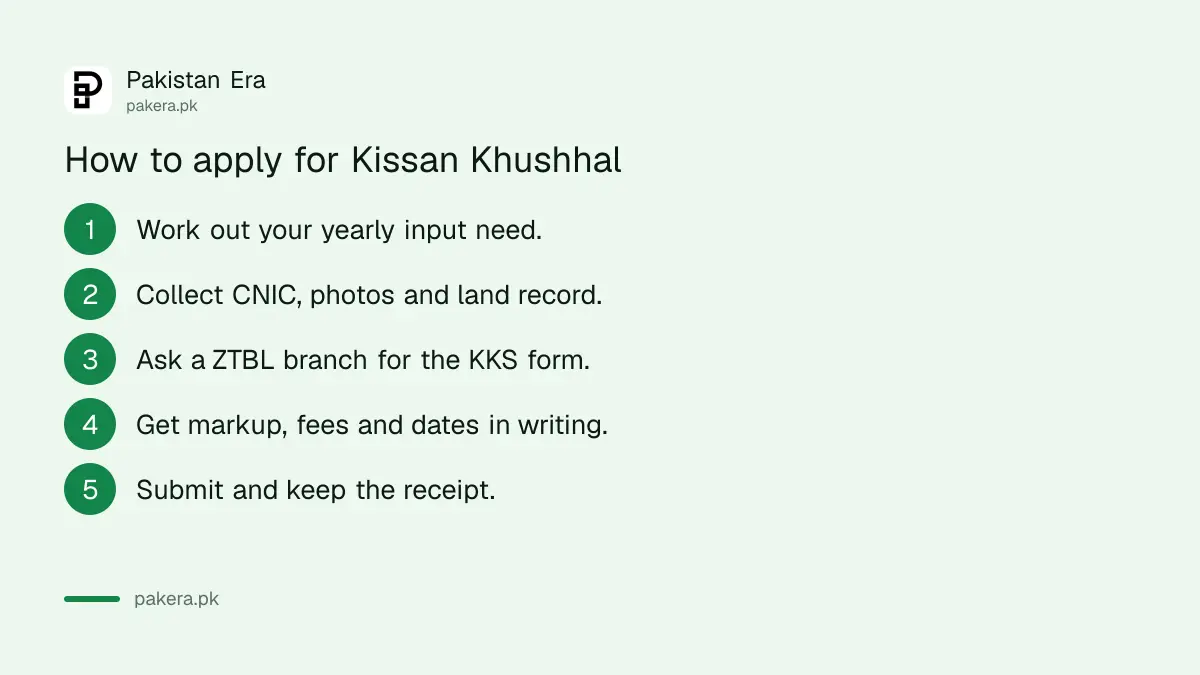
- Work out your yearly input and working-capital need, and keep it under Rs 2.5 million.
- Collect your CNIC, two photographs and the passbook or Fard Jamabandi.
- Visit a ZTBL branch and ask for the KKS application.
- Get the markup rate, all fees and the payment dates in writing.
- Submit the file, keep the receipt and note the limit expiry date once sanctioned.
The land record is the key paper. In Punjab you can get one online, as shown in the steps to get a Fard online.
Common questions about the Kissan Khushhal Scheme
What is the maximum KKS limit?
Up to Rs 2.5 million per borrower or party, sanctioned by the Credit Review Department at head office.
How long does the KKS approval last?
Three years. In the system the limit is entered for one year at a time, with expiry on the last working day of the previous month.
Which papers do I need?
A CNIC copy, the loan application, an agricultural passbook or Fard Jamabandi, and two recent photographs.
Do I pay markup on the full limit?
No. The page says only the outstanding principal attracts markup.
What is the markup rate?
The prevalent rate on production loans applies. The page gives no figure, so ask the branch.
Can I use the limit for tractors or machinery?
The page describes KKS for working capital and input needs. Machinery has its own loans, such as the tractor loan, so ask the branch before you plan it.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 15 October 2026. The limit, approval period, withdrawal rules, fees, markup dates, insurance and rescheduling terms come from ZTBL's Kissan Khushhal Scheme page at ztbl.com.pk. The fee table is copied as listed. We did not apply or call a branch. ZTBL can change its charges, so confirm every figure at the branch before you sign.
About the author
Public Services and Education Journalist
Fajr Riaz is a journalist and content writer at Pakistan Era, based in Lahore. She covers the questions people meet in everyday life in Pakistan: how a public service works, what a change in the rules means, and where to find a reliable answer.