Bank Loan Charged Off or Written Off in Pakistan: Why You Still Owe the Money Under SBP Rules
A bank charge-off only clears the loan from its books. SBP's rules say the right to recover from you stays. See what remains, what to check and how to settle.
When a bank in Pakistan "charges off" or "writes off" your loan, it only removes the loan from its own books. SBP's rules say plainly that a charge-off does not end the bank's right to recover the money from you, in court or any other lawful way. A letter that says "written off" is not a letter that says "paid".
Borrowers sometimes hear that their loan was written off and assume the debt is gone. That mistake can be costly, because a collection call or a court notice can arrive years later. We read three State Bank of Pakistan rulebooks on 21 October 2026: the Prudential Regulations for Agriculture Financing (updated 12 February 2024), the Prudential Regulations for Microfinance Banks (updated 16 May 2025) and the Prudential Regulations for SME Financing (updated 16 July 2026). Everything below comes from them unless we say otherwise.
A charge-off is a bookkeeping step for the bank
SBP defines charge-off as extinguishing the loan in the bank's books through provisions it has already made. For microfinance banks it says the purpose is "to clear the balance sheet" and that this shall in no way end the bank's right of recovery. The agriculture rules say the same.
The microfinance rules add that charge-off means reducing the value of a loan in the loss category to zero by offsetting provisions. You are not a party to that entry. It is the bank balancing its accounts, and nothing in these documents tells the bank to inform you or to cancel the debt.
The debt can still be recovered after the write-off
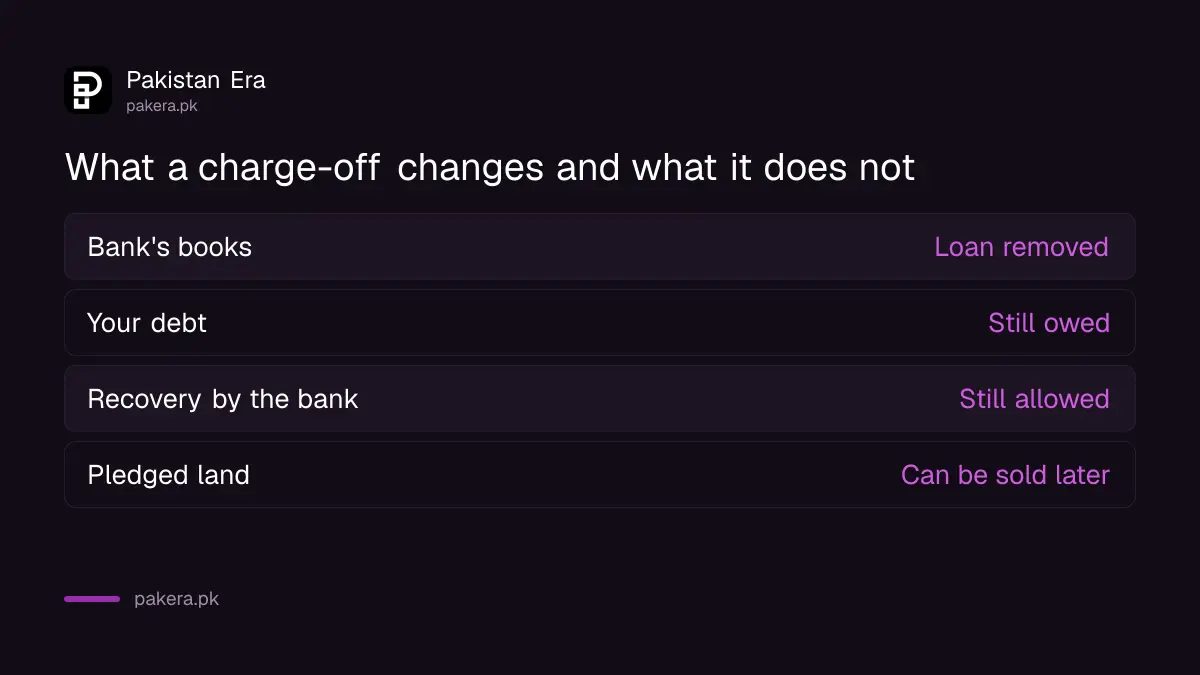
The agriculture rules say that charging off a loan does not mean the end of the bank's right to recover its money from the borrower through litigation or any other way. The bank may also sell or dispose of the security it holds or has repossessed.
The same section says that security in the form of land and buildings may take time to be taken into possession and sold later, and that charge-off will not wait for that. So a written-off loan can still have a live mortgage behind it. If you pledged land, the charge on the revenue record stays until it is cleared.
| What the bank does | What it means for you |
|---|---|
| Charges off the loan | The loan leaves its books; you still owe it |
| Keeps recovering | Calls, notices and court action remain possible |
| Disposes of security | Pledged land, stock or machinery can be sold |
| Reports to the credit bureau | Your record may keep showing the overdue loan |
A loan reaches loss class first, then charge-off
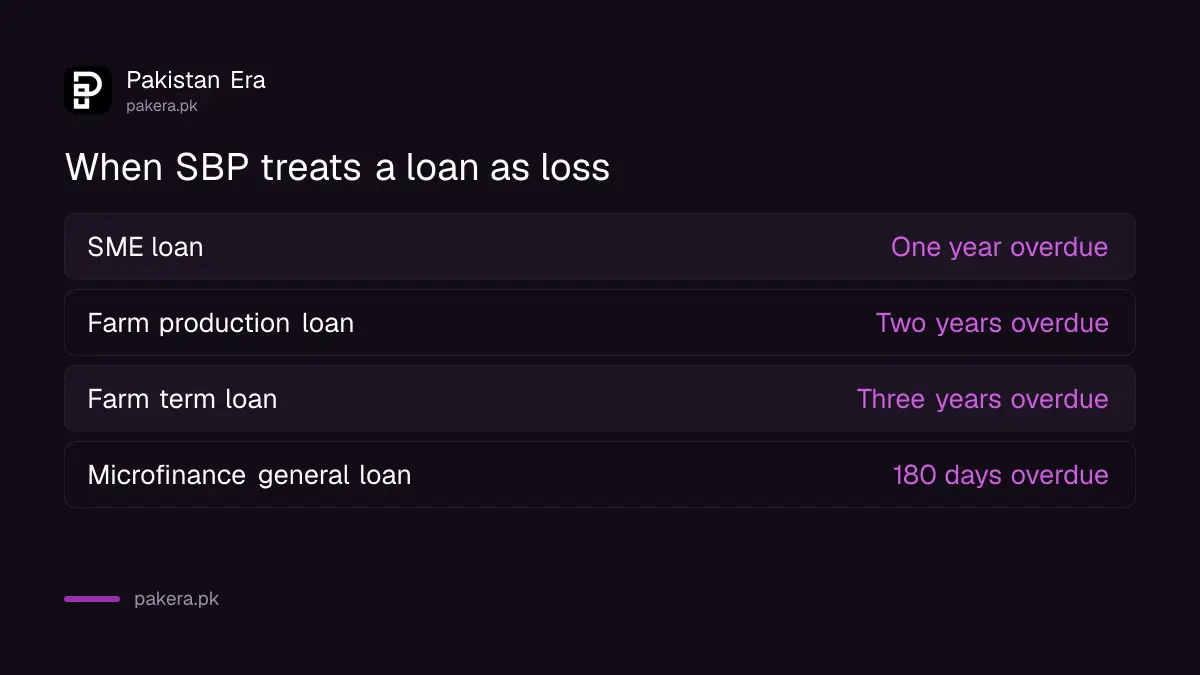
The SME rules class a loan as loss at one year overdue. Farm loans reach loss at two years for production loans and three years for term loans. Microfinance general loans reach loss at 180 days. A charge-off comes later still, on timelines that each SBP rulebook sets.
The microfinance table sets waiting periods of three to five years from classification for most loan types, and for housing loans five years. The PDF layout makes the last row for general loans hard to read, so check the table for your own loan type before relying on a date. These are SBP's periods for the bank's books, not a deadline for your repayment.
Ask for any settlement in writing before you pay
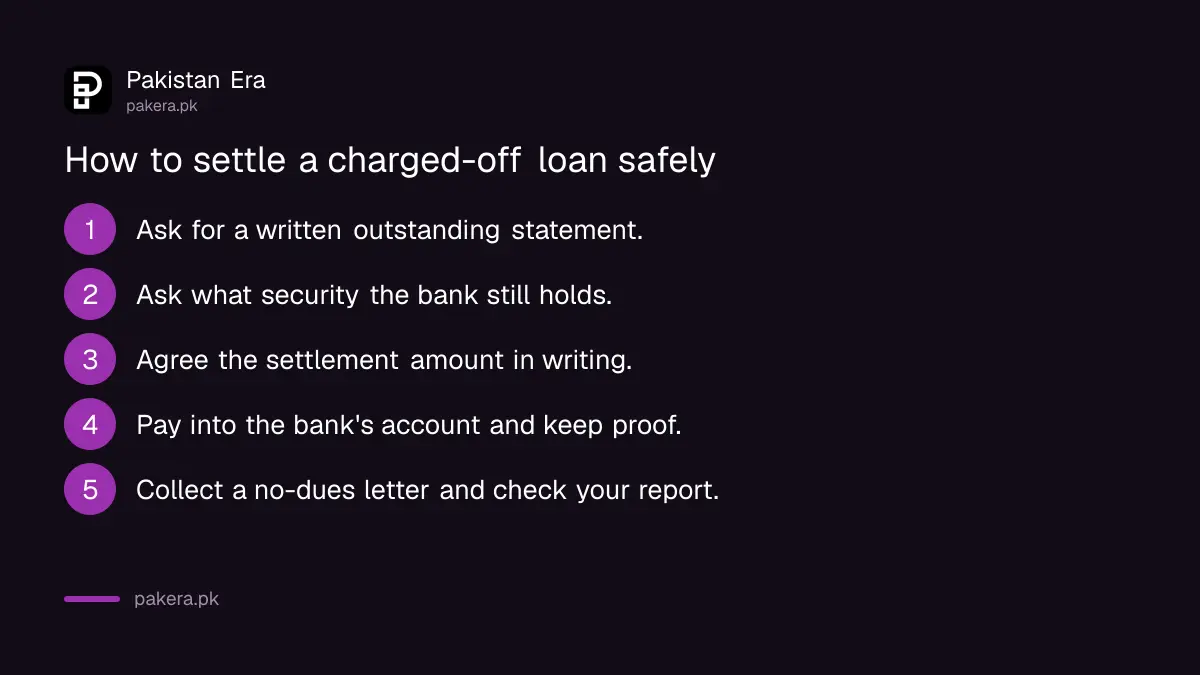
The rules do not describe settlement letters, so this part is our practical advice, not an SBP rule. If a bank offers a settlement on a classified or charged-off loan, ask for the amount, the date and the words "full and final settlement" on bank letterhead before you pay.
- Ask the bank for a written statement of the outstanding principal, mark-up and charges.
- Ask what security is still held and whether any charge is registered on your land or property.
- Agree the settlement amount in writing and pay by cheque or bank transfer, never cash to a collector.
- Collect a clearance or no-dues letter and ask for any registered charge to be released.
- Check your credit report a few weeks later to see that the entry is updated.
Check your credit report and know the collection rules
A credit report shows whether your loan is still listed as overdue. Order your own copy through the Tasdeeq and eCIB check, and read the eCIB explainer to understand the codes. We did not find a rule in these three documents that says how long a charged-off loan stays on the bureau record.
Collection must still be lawful. Banks owe you advance notice and polite conduct, as set out in the recovery agent rules. For disputes, file a complaint through the Sunwai portal. Borrowers in distress can first ask for the options in rescheduling an overdue SME loan, before the loan reaches this stage.
Common questions
Does a written-off loan disappear from my record?
Not by itself. The three SBP documents we read do not say how long the bureau keeps it. Check your own report.
Can the bank sue me after a charge-off?
SBP's rules say charge-off does not end the bank's right to recover through litigation or other means. Legal time limits are a matter of law that we did not research here.
Does charge-off cancel my mortgage?
No. The agriculture rules say land and buildings may be taken and sold later, so a registered charge can stay.
Is a charge-off the same as a waiver?
No. A waiver cancels some or all of what you owe, and only the bank's board can grant one. A charge-off is an accounting entry.
Should I pay a collector in cash?
No. Pay into the bank's own account, get a receipt and keep a written settlement letter.
How we verified this
What we checked, where we read it, and what we could not confirm.
We read the SBP agriculture, microfinance and SME prudential regulations listed above on sbp.org.pk on 21 October 2026. We did not read any bank's recovery or settlement policy, any court ruling or the law on time limits for recovery suits, so this article explains SBP's rules, not your legal defences. For a specific case, ask a lawyer.
About the author
Public Services and Education Journalist
Fajr Riaz is a journalist and content writer at Pakistan Era, based in Lahore. She covers the questions people meet in everyday life in Pakistan: how a public service works, what a change in the rules means, and where to find a reliable answer.