How to Dispute a Credit Card Charge in Pakistan
State Bank caps a Pakistani bank at 45 days to settle a disputed credit card charge. No interest meanwhile, and a refund if you win, even on a cancelled card.
A Pakistani bank cannot sit on a disputed credit card charge forever. State Bank caps the whole process at forty five days for a transaction made inside Pakistan, and the clock is on the bank, not you. Most cardholders never ask for the complaint number that starts that clock, and without it there is nothing forcing the bank to move.
We read the State Bank of Pakistan's 2009 operational guidelines for credit card business at source on 5 October 2026 to lay out exactly what a bank owes you once you dispute a charge.
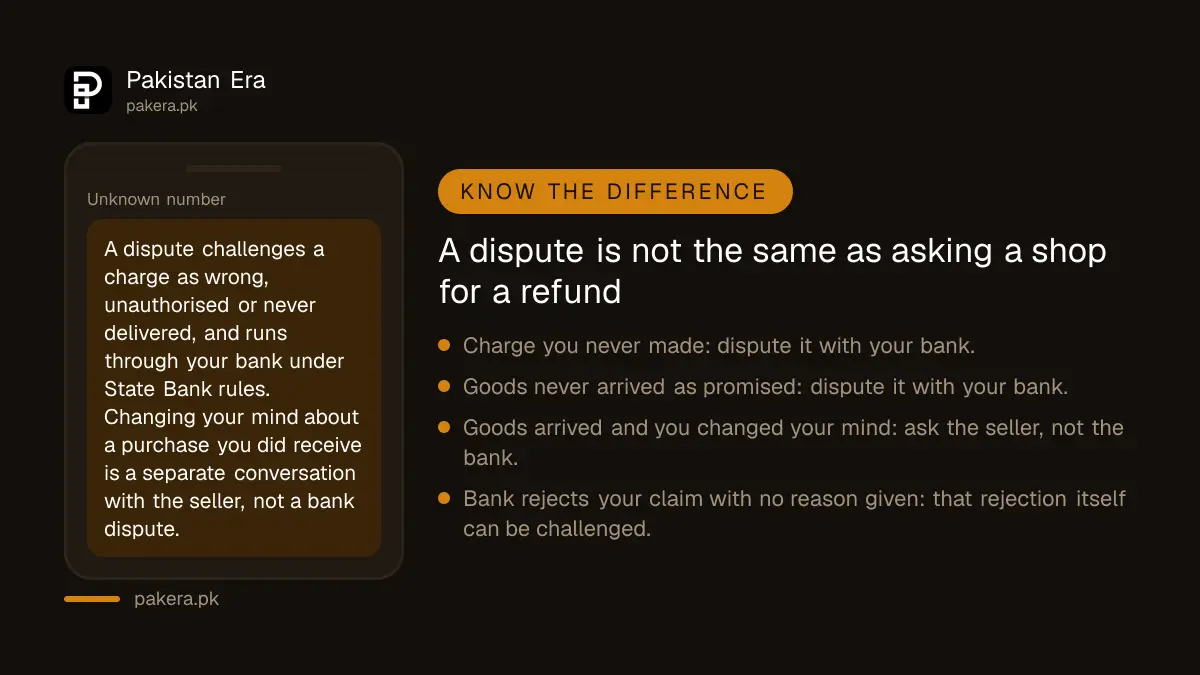
A dispute is a specific claim, not a change of mind
You dispute a charge you did not make, a charge for goods that never arrived as promised, or an amount that simply does not match what you agreed to. That is different from receiving exactly what you ordered and deciding afterward that you do not want it.
Mixing the two up wastes your own time. A genuine change of mind goes to the seller under consumer protection rules, not your bank's dispute desk.
Opening a dispute starts a clock your bank has to follow
Call your bank as soon as you see the charge. Every complaint must get a number, and the bank has to give it to you, not just note it internally.
Confirm the dispute in writing the same day, by email or through the bank's own online complaint form if it has one. Keep paying the rest of your statement as normal; only the disputed line is frozen.
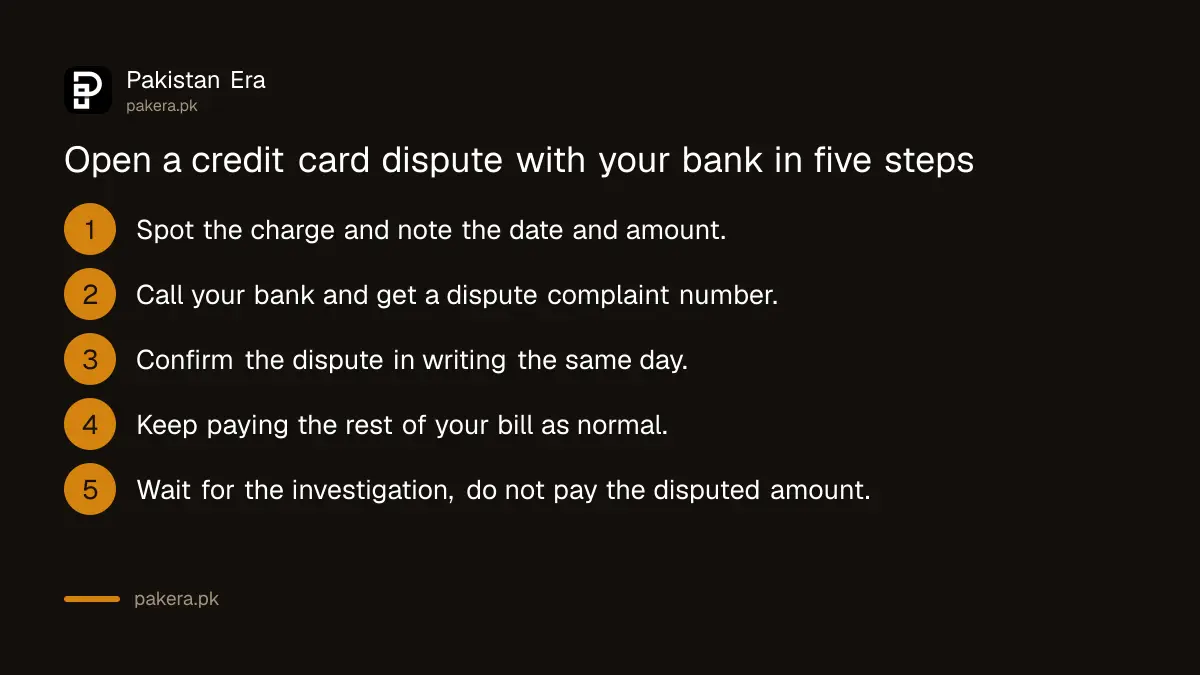
- Note the exact date, amount and merchant name on the charge.
- Call your bank and insist on a dispute complaint number before you hang up.
- Put the same complaint in writing the same day, through email or the bank's portal.
- Continue paying every part of your bill except the disputed amount.
- Wait for the bank's investigation rather than repeatedly calling to check.
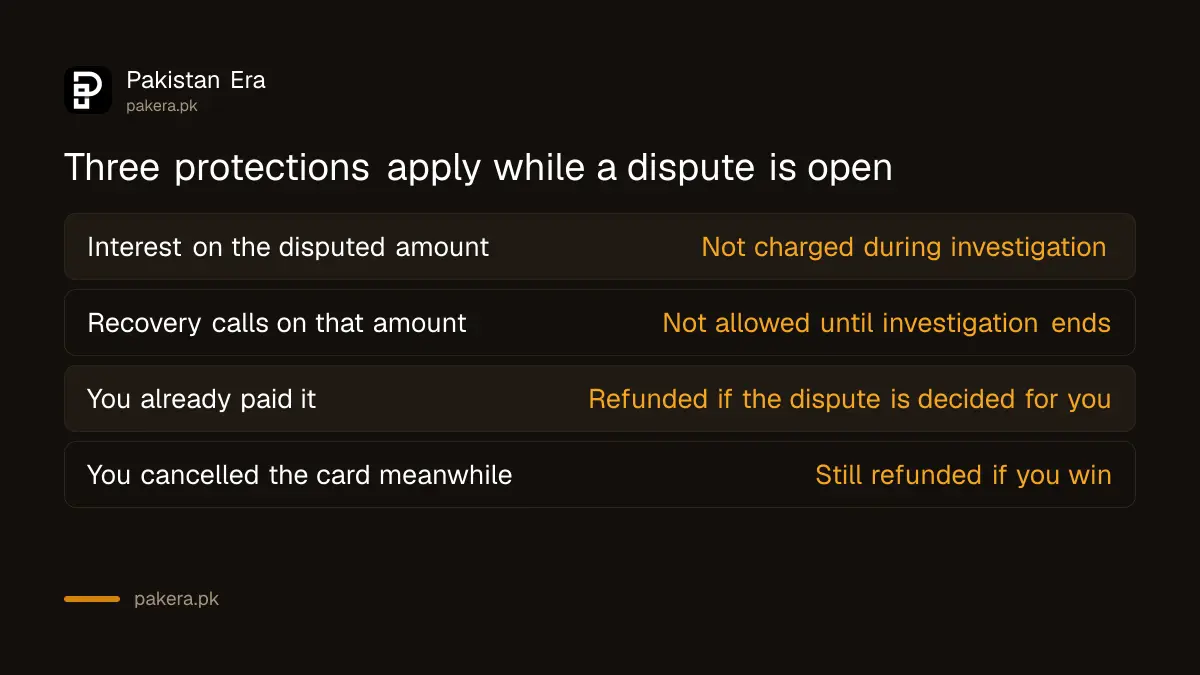
Three protections apply the moment a dispute is open
The guidelines are blunt about what cannot happen to you while a dispute runs. None of these require you to ask twice.
| Protection | What the rule says |
|---|---|
| Interest on the disputed amount | Not charged during the investigation |
| Recovery or collection calls | Not allowed until the investigation is complete |
| You already paid the charge | Refunded in full if the dispute is decided for you |
If the dispute is later settled in the bank's favour, only then can it recover the interest that built up during the wait. That order matters: the bank carries the risk of the delay, not you.
Forty five days is the outer limit, not a target
Banks must resolve a disputed transaction according to the franchise rules of VISA, Mastercard, Amex or whichever network issued the card, factoring in the merchant's location and time zone. But for anything that happened inside Pakistan, the guideline sets a hard ceiling.
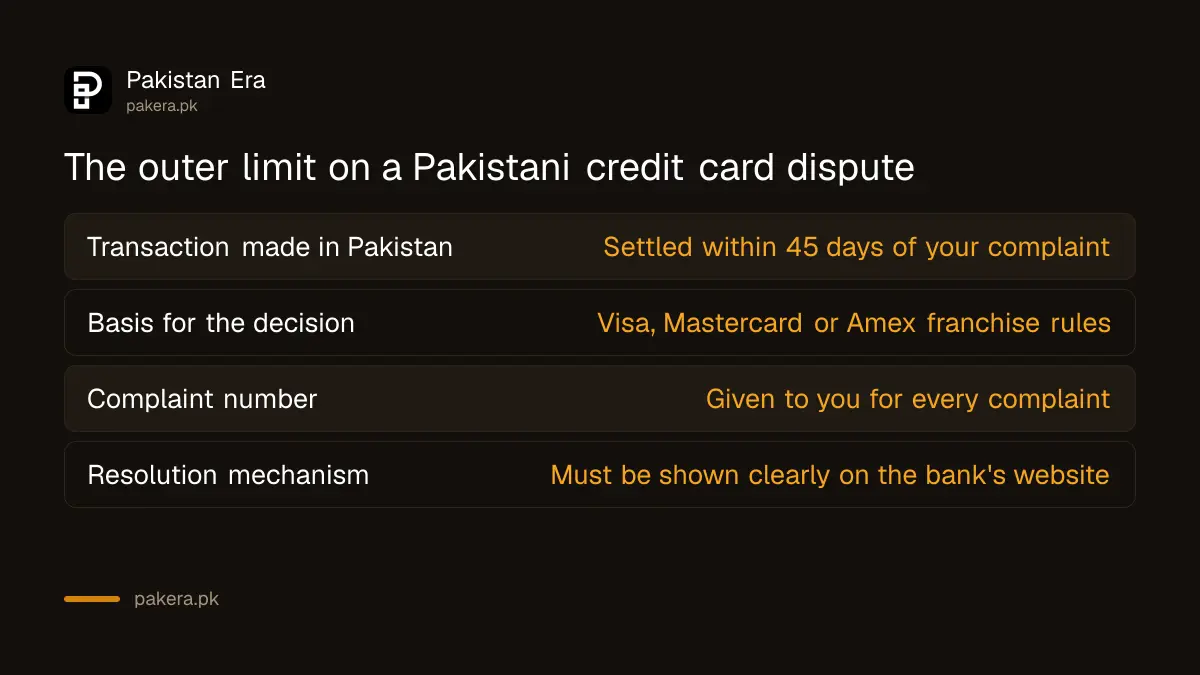
Forty five days from the date of your complaint, not from the date of the charge. A bank that drags a straightforward dispute past that point has missed its own regulator's ceiling, which is worth saying plainly when you escalate.
Even a cancelled card does not forfeit a win
Cardholders sometimes cancel the card in frustration while a dispute is still open. The guideline specifically protects that situation: if you already paid the disputed amount and later cancelled the card, you are still refunded if the dispute is decided in your favour.
A wrongly rejected claim carries a penalty for the bank
This is the part most cardholders do not know exists. If a bank rejects your claim on a wrong or inappropriate basis, the guideline makes the bank liable for a penalty, not just a quiet correction.
That is leverage. If your dispute is denied with a reason that does not hold up, such as a receipt you never signed or a delivery address you never used, say so in writing and ask the bank to justify the specific basis for rejection.
If your bank still will not move
Past the 45 day ceiling, or facing a rejection that does not add up, you are not out of options. Escalation is free and does not need a lawyer.
- Put the full history of your dispute, with dates, in writing to the bank's complaint unit.
- State plainly that the 45 day limit has been missed, if it has.
- If there is still no satisfactory answer, the Banking Mohtasib ombudsman route is free and does not require your bank's cooperation to start.
Before any of this, it helps to know what a card actually costs you to hold in the first place; our comparison of credit card fees across Pakistani banks covers that, and anyone still deciding which card to apply for can see what one real product's terms look like in our Zindigi credit card guide.
Frequently asked questions
How long does a bank have to settle a credit card dispute?
Forty five days from the date you lodge the complaint, for a transaction that took place inside Pakistan.
Will I be charged interest on a disputed amount?
No, not while the investigation is open. Interest is only recovered afterward if the dispute is settled in the bank's favour.
What if I already paid the disputed charge?
You are refunded in full if the dispute is decided in your favour, even if you had already paid it or cancelled the card since.
Is a return because I changed my mind the same as a dispute?
No. That is a seller matter under consumer protection rules, not a bank dispute, since you did receive what you ordered.
What happens if the bank rejects my dispute unfairly?
The guideline makes the bank liable for a penalty for a wrong or inappropriate rejection, which is grounds to push back in writing.
What can I do if the bank ignores the 45 day limit?
Escalate in writing to the bank first, then take it to the free Banking Mohtasib ombudsman if there is still no satisfactory answer.
About the author
Tax, Bills and Technology Writer
Ali Akhtar is a young and curious voice here at Pakistan Era. He is currently pursuing his A-Levels and has a growing interest in Pakistan’s changing industrial landscape and educational trends. Ali likes to write in a way that helps him explain and explore the world around him. His writing reflects the perspective of the new generation navigating the evolving trends of Pakistan where technology, youth innovation, and shifting opportunities are reshaping the country’s future.