Gold Loan From a Microfinance Bank in Pakistan: Gold Back in 3 Days, 3 Notices Before Auction
SBP rules make microfinance banks return pledged gold within 3 working days of repayment and send 3 notices before any auction. See valuation and surplus rules.
Short answer: if you pledge gold for a loan at a microfinance bank in Pakistan, the bank must return your gold within 3 working days of full repayment, value it on net gold weight only, and send you three notices before it can auction anything. If the sale raises more than you owe, the extra money is yours.
These rules are in Annexure H of the State Bank of Pakistan's Prudential Regulations for Microfinance Banks, updated on 16 May 2025. We read them on the SBP website on 20 October 2026. The annexure exists because, in the SBP's words, microfinance banks now deal with gold collateral "on daily basis".
Gold-backed loans are common because they are fast: the jewellery is the security, so the paperwork is light. But the gold sits in the bank's vault, and families worry about two things. Will the gold be valued fairly, and will it be sold without warning? The SBP rules answer both.
Your gold must come back within 3 working days of repayment
Once you repay the loan and mark-up in full, the microfinance bank must return your gold within 3 working days. It must give you an acknowledgement receipt that lists the details of the gold returned. Keep that receipt.
The bank must also have written procedures for releasing gold if the borrower dies or is absent. That is why the application form must include a "Next to Kin" section, or a separate certificate, naming who receives the gold in case of the borrower's death. Fill it in. It saves your family a fight later.
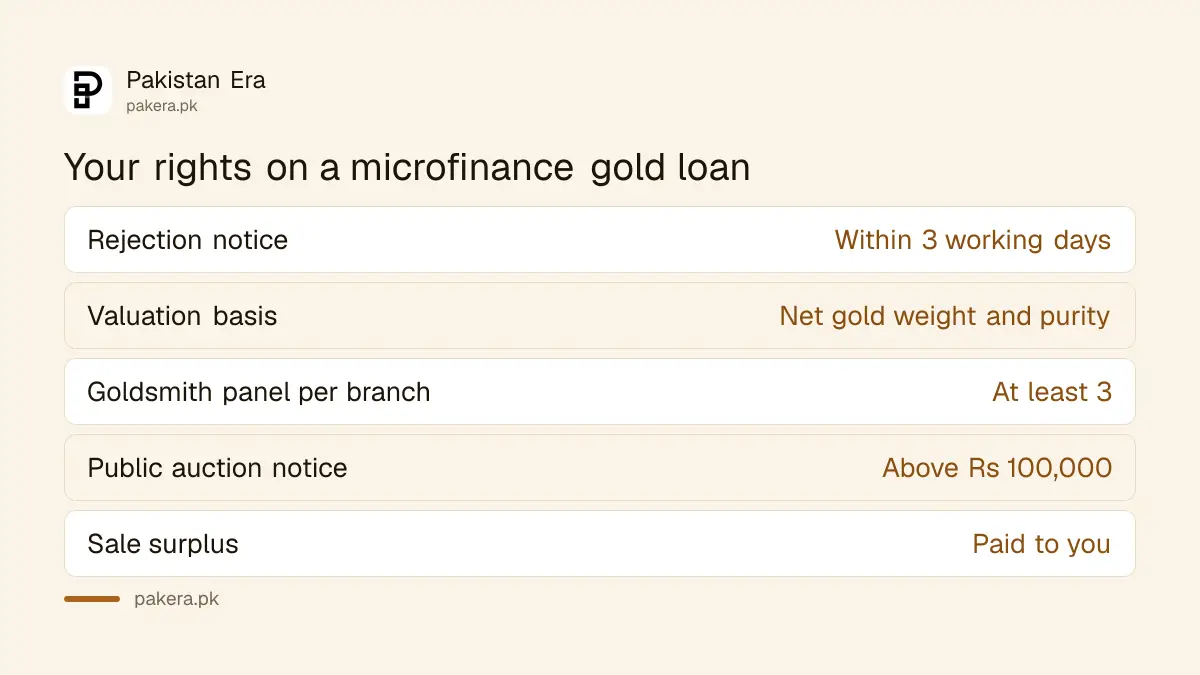
The same 3 working day rule applies at the start. If the bank rejects your loan application, it must tell you within 3 working days.
Gold is valued on net weight and purity only
The valuation must be based only on the weight and fitness, or purity, of the gold. Stones, lace, alloy, strings and fastenings are taken out of the weight. The certificate must show gross weight, net weight and value at the prevailing market price.
| What the valuation certificate must show | Why it matters to you |
|---|---|
| Description of each ornament | Proves what you handed over |
| Fitness, meaning purity | Lower purity means a lower loan |
| Gross weight | The full weight of the piece |
| Net gold weight without stones and fittings | The weight the loan is based on |
| Value at the prevailing market price | Lets you check against the day's rate |
Valuation should preferably happen in the bank's own branch, in front of you and a bank officer. Each branch must keep a panel of at least three goldsmiths or shroffs and assign them at random. A goldsmith on the panel must have years in business, a clean credit record and no criminal conviction. To check the bank's figure against the market, compare it with the day's rate per tola, explained in how the gold rate per tola works.
The bank must send three notices before any auction
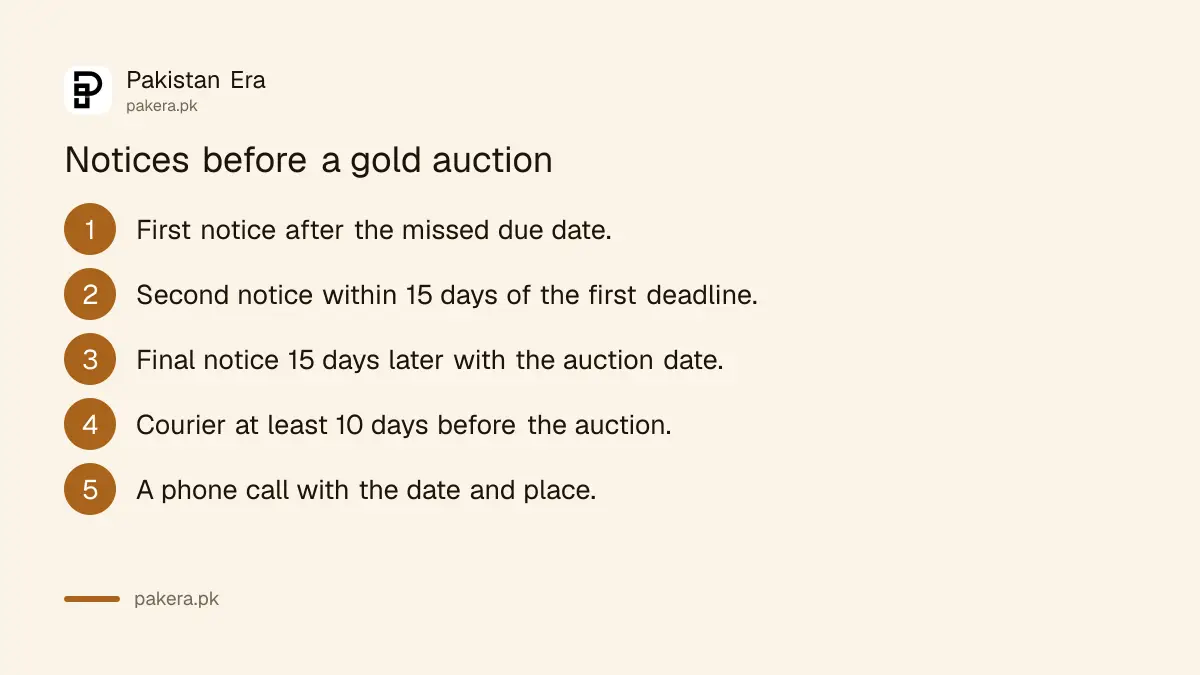
If you miss the due date, the bank cannot sell your gold straight away. It must send a first notice, then a second notice, then a third and final notice with the auction date, at least 10 days before the auction by registered courier.
- First notice: sent after you miss the due date, giving a timeline to settle the loan.
- Second notice: sent within 15 days after the first notice's deadline, warning that the gold will be auctioned and the loan adjusted.
- Third and final notice: sent 15 days after the second, with a public auction notice and the auction date, by registered courier at least 10 days before the auction.
- Phone call: the bank must also tell you the auction date and place by telephone or mobile call.
On our reading of those gaps, at least 25 days pass between the second notice and the auction itself. That is time to repay, renegotiate or arrange funds. The bank must print this auction procedure in bold in the loan application, so you can check it before you sign.
If a bank skips a notice or auctions early, complain to the bank in writing first and keep the courier slips you received. If that fails, the next step is the SBP, as explained in complaining about a microfinance bank.
Auctions are public above Rs 100,000 and the surplus is yours
If the gold is worth less than Rs 100,000, the bank must call the borrower, the gold's owner, the loan witness and its goldsmith panel to the auction. Above Rs 100,000, it must advertise the auction in at least two local newspapers, one in Urdu.
The notice must give the net gold details recorded when you pledged it. If the gold sells for more than the loan, mark-up and charges, the bank must tell you promptly to collect the surplus. The bank must also keep a detailed record of every auction.
| Gold value at auction | Who must be told |
|---|---|
| Below Rs 100,000 | Borrower, gold owner, loan witness and goldsmith panel, called to attend |
| Above Rs 100,000 | Public notice in at least two local newspapers, one in Urdu |
The bank must insure and guard your gold
Pledged gold must be insured against theft, fire, riots and other risks. It must be kept in a fireproof safe or strong room, in tamper-proof bags tagged with your account details, under dual control and video surveillance.
Only branches the bank has authorised for gold loans can take gold, and the bank must keep an updated list of them. The bank must also insure the loan itself against the borrower's death. One more rule worth knowing: a microfinance bank cannot lend you money to buy gold.
Gold loans count toward the general limits on how much a microfinance bank can lend you, set out in microfinance bank loan limits. And each bank's total gold-backed lending is capped at 35% of its loan book.
Common questions
How soon must a microfinance bank return my gold?
Within 3 working days of full repayment of the loan and mark-up, with a receipt listing the gold returned.
Can a microfinance bank auction my gold without telling me?
No. It must send three notices, the last by registered courier at least 10 days before the auction, and call you.
Do stones count in a gold loan valuation?
No. The valuation is based on net gold weight and purity, without stones, lace, alloy or fastenings.
What happens if my gold sells for more than I owe?
The surplus is yours. The bank must tell you promptly to collect it.
Can I take a microfinance loan to buy gold?
No. The SBP rules say a microfinance bank shall not lend to a borrower to buy gold or gold ornaments.
How we verified this
What we checked, where we read it, and what we could not confirm.
We read Annexure H, "Financing against Gold Backed Collateral, Instructions for MFBs", and Regulation R-5 of the State Bank of Pakistan's Prudential Regulations for Microfinance Banks, updated on 16 May 2025, on 20 October 2026. These rules apply to SBP-licensed microfinance banks. We did not check how commercial banks or private lenders handle gold, did not pledge gold ourselves, and could not see any bank's internal gold policy or loan to value margin.
About the author
Public Services and Education Journalist
Fajr Riaz is a journalist and content writer at Pakistan Era, based in Lahore. She covers the questions people meet in everyday life in Pakistan: how a public service works, what a change in the rules means, and where to find a reliable answer.