Tax on Golden Handshake, Gratuity and Provident Fund in Pakistan: What Is Exempt and How to Pay Less
Tax on golden handshake, gratuity and provident fund in Pakistan: PF exempt, gratuity up to Rs 300,000 or Rs 75,000, and the section 12(6) average rate option.
When you leave a job in Pakistan, your provident fund balance from a recognised fund is tax free. Gratuity is tax free in full from an approved gratuity fund, or up to Rs 300,000 from an FBR-approved scheme, and otherwise only half of it, capped at Rs 75,000. A golden handshake is taxable salary, but you can choose to pay tax on it at your average rate for the last three years.
Severance, gratuity, provident fund and salary arrears often arrive in one large payment. Taxed at slab rates, that one-off sum can push you into the top bracket. The Income Tax Ordinance, 2001 gives two elections in section 12 that stop this, and the Second Schedule exempts most retirement funds. Here is each payment and what to do.
How each end-of-service payment is taxed
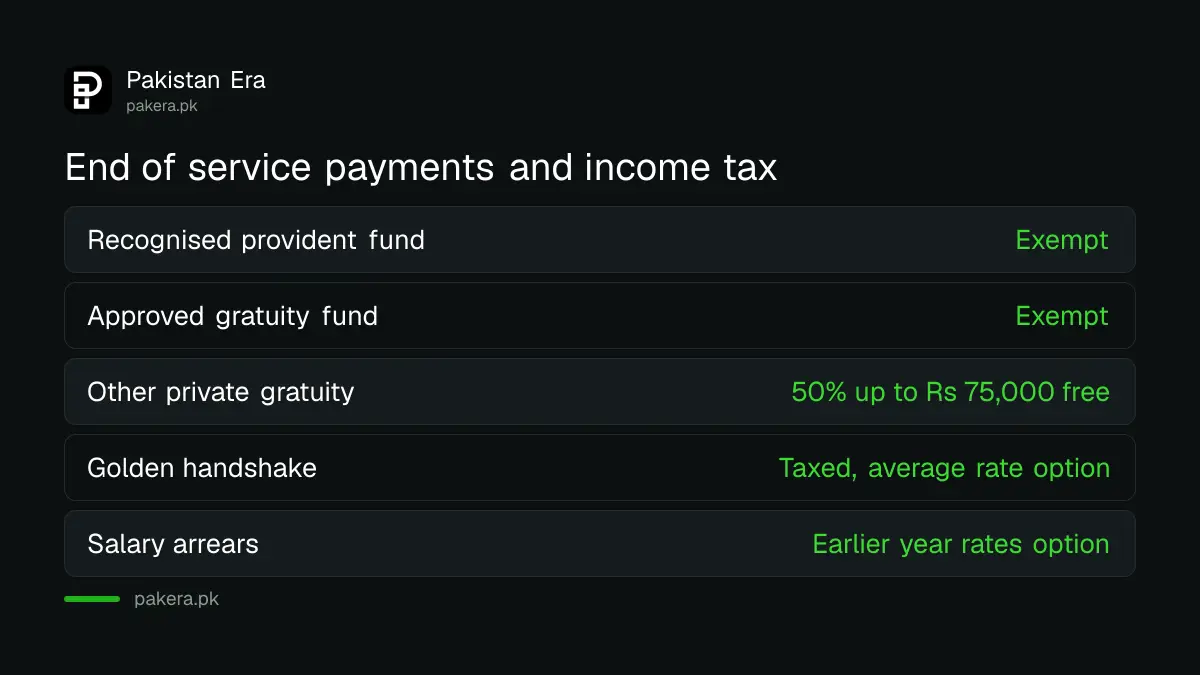
Provident fund, approved pension fund transfers and government gratuity are exempt. Other gratuity is partly exempt. A golden handshake, notice pay and salary arrears are taxable salary, but two elections in section 12 can lower the rate. Leave encashment is exempt only for government and armed forces employees on retirement.
| Payment | Tax treatment | Law |
|---|---|---|
| Recognised provident fund balance | Exempt | Clause (23), Part I, Second Schedule |
| Provident fund under the Provident Funds Act, 1925 (government) | Exempt | Clause (22) |
| Gratuity, government or statutory body employee | Exempt as per service rules | Clause (13)(i) |
| Gratuity from an approved gratuity fund | Exempt | Clause (13)(ii) |
| Gratuity under an FBR-approved scheme for all staff | Exempt up to Rs 300,000 | Clause (13)(iii) |
| Any other gratuity | Exempt up to 50% or Rs 75,000, whichever is less | Clause (13)(iv) |
| Commutation of pension from government or an approved scheme | Exempt | Clause (12) |
| Golden handshake, severance, redundancy pay | Taxable salary, average-rate election available | Sections 12(2)(e)(iii) and 12(6) |
| Salary arrears | Taxable, election to use the earlier year's rates | Section 12(7) |
| Leave encashment before retirement (government, armed forces) | Exempt | Clause (19) |
Gratuity is exempt in full, up to Rs 300,000, or only half
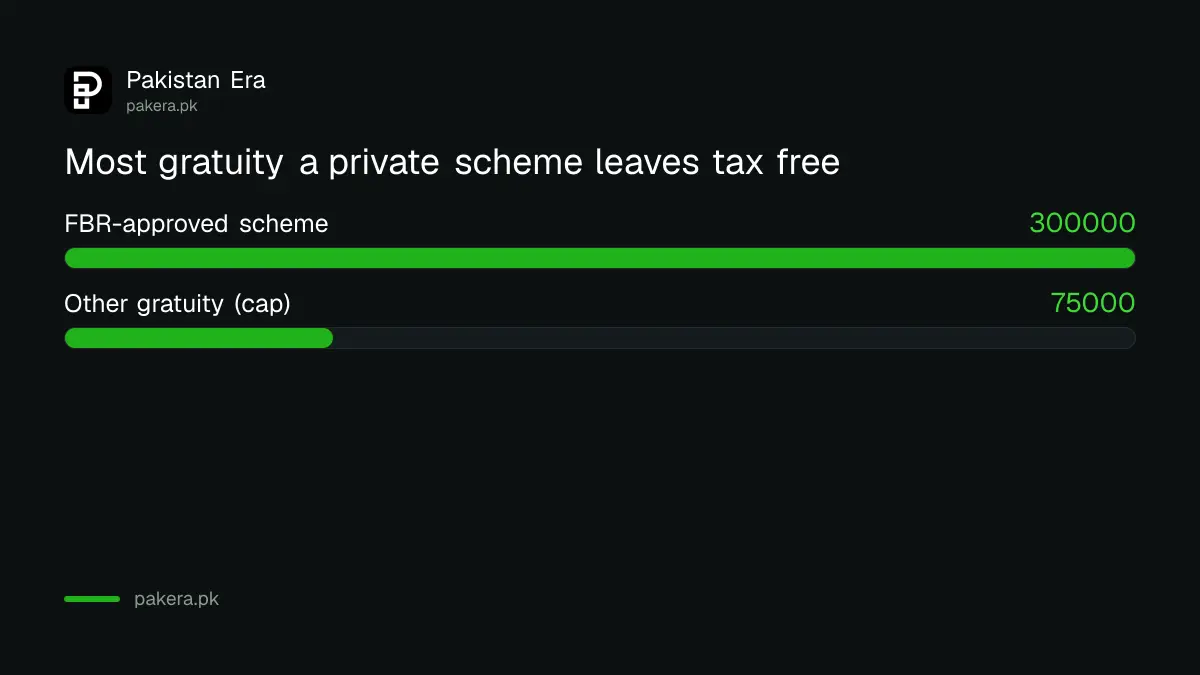
Clause (13) has four levels. Government and statutory body staff get the full amount under their service rules. An approved gratuity fund is fully exempt. An FBR-approved scheme for all employees is exempt up to Rs 300,000. Everyone else gets 50% exempt, capped at Rs 75,000.
Example: a private company with no approved fund pays you Rs 400,000 as gratuity. Half is Rs 200,000, which is more than Rs 75,000, so only Rs 75,000 is exempt. The other Rs 325,000 is taxed as salary.
Four cases get no exemption at all under the proviso to clause (13):
- gratuity paid outside Pakistan;
- gratuity paid by a company to a director who is not a regular employee;
- gratuity paid to someone who is not a resident individual;
- a second gratuity, where you have already received gratuity from the same or any other employer.
The last point catches people who change jobs. If you took gratuity from your first employer, gratuity from the next one is fully taxable. Before you accept a payout, ask HR whether the company's gratuity fund is approved by the Commissioner, because that decides whether it is fully tax free.
Provident fund and pension fund money is tax free
The accumulated balance of a recognised provident fund is exempt under clause (23). Government provident funds under the Provident Funds Act, 1925 are exempt under clause (22). Moving a provident fund balance into an approved pension fund, and later withdrawing it, is exempt under clause (23C).
Voluntary Pension System accounts follow clause (23A). Up to 50% of the balance can be withdrawn tax free on retirement, on disability that stops you working, or by your nominees on death. Different rules apply to early withdrawals. For the federal scheme for new government staff, see the list of fund managers for the federal contributory pension scheme.
Golden handshake: elect your average rate under section 12(6)
Section 12(2)(e)(iii) makes any amount paid on leaving a job taxable salary. That includes golden handshake, redundancy and compensation. Section 12(6) lets you ask the Commissioner, in writing, to tax it at your average rate for the previous three tax years instead of the slab rate.
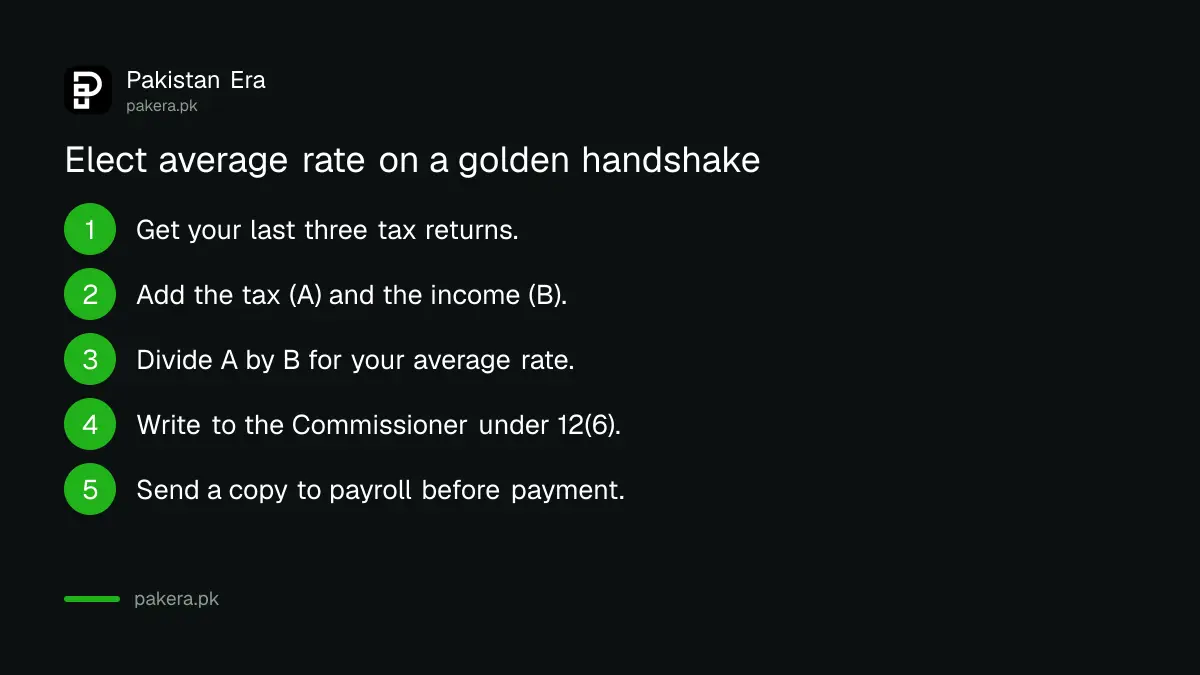
The formula is A divided by B, as a percentage. A is the total tax paid or payable on your taxable income for the three previous tax years. B is your total taxable income for the same three years.
Example: over the last three tax years you paid Rs 900,000 tax on a total taxable income of Rs 9,000,000. Your average rate is 10%. A golden handshake of Rs 5,000,000 is then taxed at 10%, which is Rs 500,000. Added on top of a normal salary, the same amount would fall in a much higher slab.
- Collect your last three tax returns, or the tax certificates for those years, from IRIS or your employer.
- Add up the tax paid or payable (A) and the taxable income (B) for the three years.
- Divide A by B to get your average rate.
- Write to the Commissioner Inland Revenue for your tax office, electing to have the golden handshake taxed under section 12(6), with your workings.
- Give a copy to your employer so payroll can deduct at that rate.
- File the election by the due date of your return for the year you received the money, or a later date the Commissioner allows.
Salary arrears can be taxed at the earlier year's rates
When back pay for an earlier year pushes you into a higher slab this year, section 12(7) lets you elect, in writing to the Commissioner, to pay tax at the rates that would have applied in the year you did the work. The deadline is the same as for a golden handshake.
This helps most with pay revisions announced late, court-ordered back pay, or promotions given with effect from a past date. Work out the tax both ways first. If the earlier year's rates give a higher figure, simply do not elect.
Whatever you elect, check the tax your employer deducted against the withholding tax certificate your employer issues, and claim any excess when you file your salaried return on IRIS. Refunds then show in the FBR refund status check.
Common questions
Is provident fund taxable at retirement in Pakistan?
No. The accumulated balance of a recognised provident fund is exempt under clause (23) of Part I of the Second Schedule.
How much gratuity is tax free in a private company?
All of it from an approved gratuity fund, up to Rs 300,000 under an FBR-approved scheme, otherwise 50% capped at Rs 75,000.
Is golden handshake taxable?
Yes, as salary. But you can elect under section 12(6) to be taxed at your average rate for the last three tax years.
What is the deadline for the section 12(6) election?
The due date for your return of income for the year you received the payment, or a later date the Commissioner allows.
Is my second gratuity tax free?
No. Clause (13) gives no exemption to gratuity received by someone who already got gratuity from the same or another employer.
Is commutation of pension taxable?
No, when paid by government or under a pension scheme approved by FBR, under clause (12) of the Second Schedule.
How we verified this
What we checked and where we read it.
We checked section 12(2), (6), (7) and (8) and clauses (12), (13), (19), (22), (23), (23A) and (23C) of Part I of the Second Schedule in the Income Tax Ordinance, 2001 amended up to 30 June 2026 on FBR's download server, on 15 November 2026. The Rs 300,000 limit in clause (13)(iii) dates from the Finance Act, 2016. The examples are our own arithmetic. For pension itself, see filing a tax return as a pensioner.
About the author
Tax, Bills and Technology Writer
Ali Akhtar is a young and curious voice here at Pakistan Era. He is currently pursuing his A-Levels and has a growing interest in Pakistan’s changing industrial landscape and educational trends. Ali likes to write in a way that helps him explain and explore the world around him. His writing reflects the perspective of the new generation navigating the evolving trends of Pakistan where technology, youth innovation, and shifting opportunities are reshaping the country’s future.