What to Do If FBR Suspends or Blacklists Your Sales Tax Registration in Pakistan
FBR suspended your sales tax registration? A show cause notice must follow in 10 days and blacklisting can be appealed in 30. See the steps and what to send.
Short answer: If FBR suspends your sales tax registration, the Commissioner must send you a show cause notice within 10 days of the suspension order. After your reply and a hearing, the Commissioner either revokes the suspension or issues a speaking order to blacklist you, within 30 days of your reply. A blacklisting order can be appealed within 30 days.
A supplier in Sialkot opens his FBR portal one morning and finds his registration suspended. By noon his buyers are calling. Their input tax credit, the tax they deduct from their own bill, may now be in question. The law gives him a fixed sequence of steps. The first one is to know which step he is on.
We read section 21 and section 45B of the Sales Tax Act, 1990, as amended up to 30 June 2026, on FBR's own website on 12 October 2026. Part of section 21 was added by the Finance Act, 2025, and another part by the Finance Act, 2026.
The Commissioner can suspend or blacklist for fake invoices, tracking breaches or fraud
Section 21(2) lets the Commissioner suspend or blacklist a registered person who has issued fake invoices, has not complied with the invoice integration rules in section 23 or the tracking rules in section 40C, or has otherwise committed tax fraud.
The words about section 23 and section 40C were added by the Finance Act, 2026. So a registration can now be suspended for a failure to integrate invoicing with FBR's system or to link goods movement with the tracking system, not only for fake invoices.
Section 21(1) is different. It lets the Board de-register a person who is not required to be registered, under the rules. That is a clean-up step, not a punishment.
Suspension must be followed by a show cause notice within 10 days
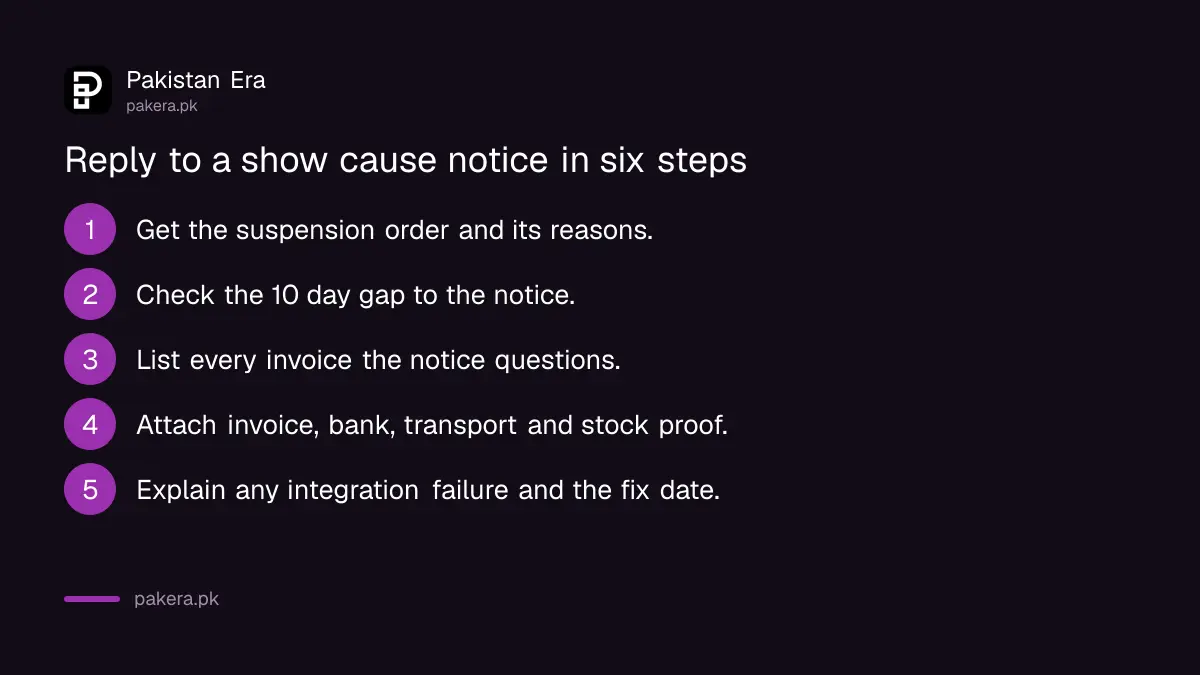
Under section 21(2A), added by the Finance Act, 2025, the Commissioner must issue a show cause notice within ten days of the suspension order. The Commissioner may then revoke the suspension, or issue an appealable speaking order for blacklisting within 30 days of receiving your reply.
| Stage | Time limit in the Act | What you do |
|---|---|---|
| Suspension order issued | Day 0 | Get a copy and read the reasons |
| Show cause notice | Within 10 days of suspension | Check it was issued in time and read the allegations |
| Your reply and hearing | As the notice states | Reply in writing with invoices, bank and transport proof |
| Order revoking suspension or blacklisting | Within 30 days of your reply | If blacklisted, take the order and appeal |
| Appeal | Within 30 days of receipt of the order | File with the Commissioner (Appeals) |
Your buyers lose their credit while you are suspended
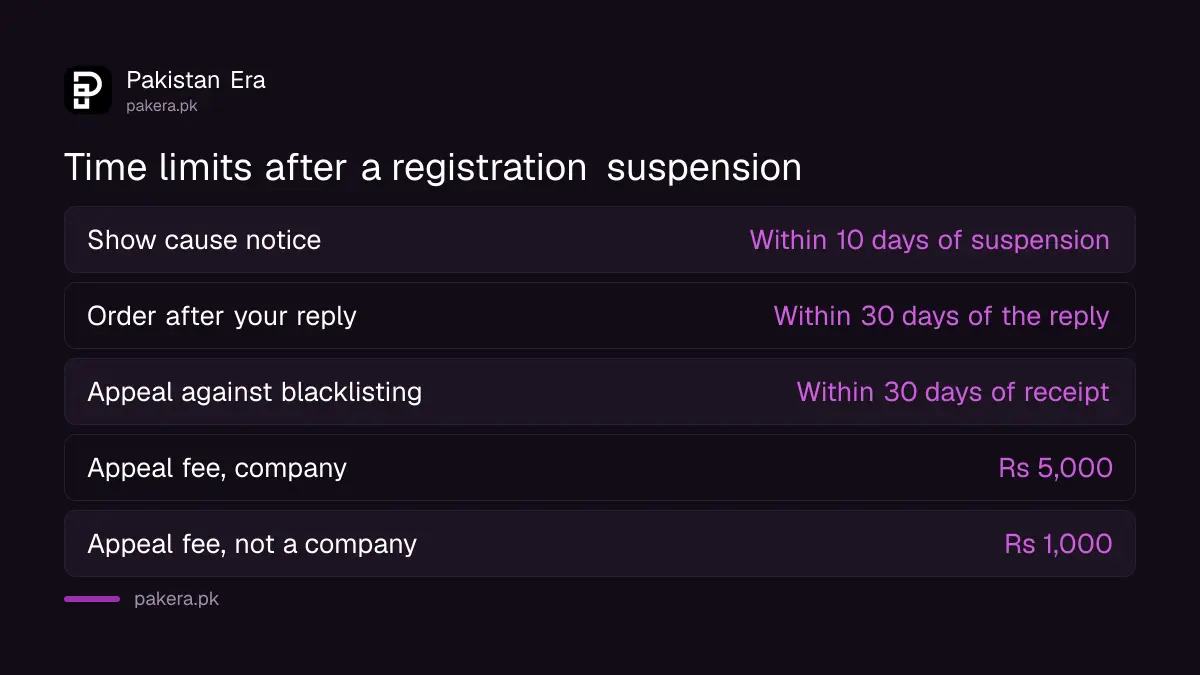
While a registration is suspended, invoices you issue are not entertained for sales tax refund or input tax credit. Once you are blacklisted, refund or credit claimed against your invoices, before or after the blacklisting, is rejected by a speaking order after the buyer is heard.
This is why a suspension travels fast through a supply chain. Your buyers should check your status before they claim credit. If you are a buyer, the same rule is a reason to verify each supplier, as covered in the only two places FBR accepts for verifying an NTN.
Separately, section 21(4) lets the Board or the Commissioner, after recording reasons in writing, block refunds or input tax adjustments of a person who is believed to issue fake or flying invoices, to not physically exist or to commit other fraud, and send the case for investigation.
What to put in your reply to the show cause notice
Answer each allegation with documents. A reply that says only "we did nothing wrong" does not help. A reply that shows the invoice, the bank transfer, the delivery record and the stock register does.
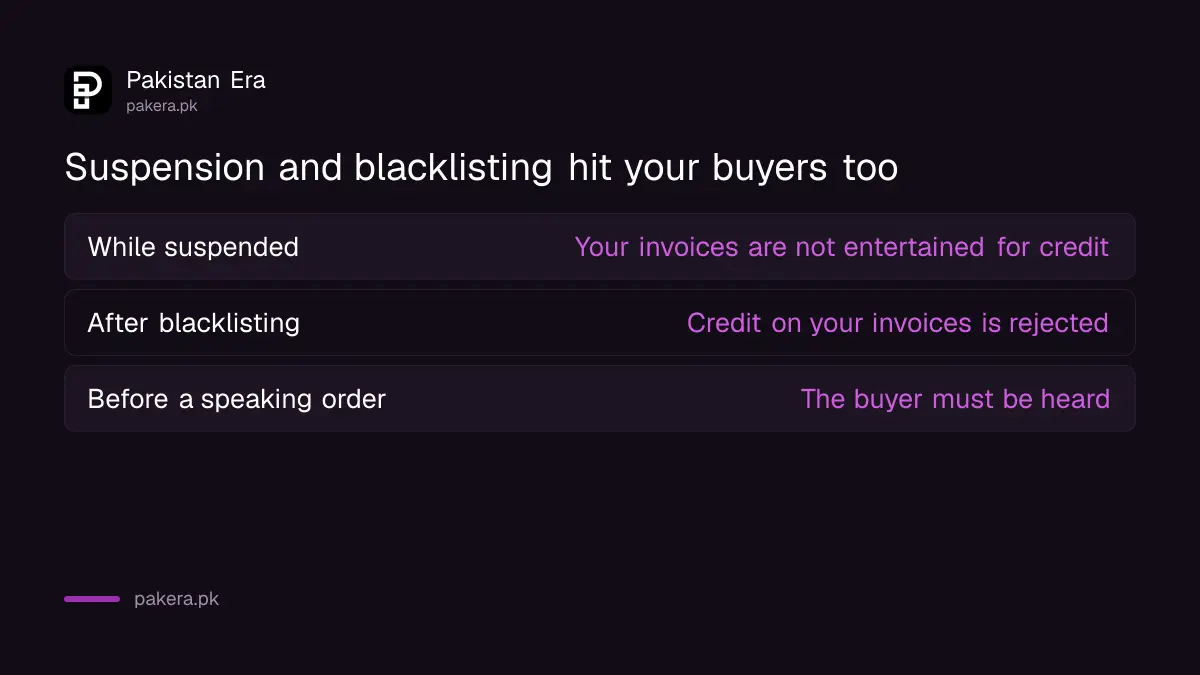
- Request a copy of the suspension order and the reasons, if you have not got them.
- Note the date of the suspension order and the date of the show cause notice, and check the 10 day gap.
- List each invoice or transaction the notice questions.
- For each one, attach the invoice, the bank proof, the delivery or transport record and the stock entry.
- Explain any integration or tracking failure and show the date you fixed it.
- Ask for a hearing in writing, attend it and keep the hearing note.
Records are what you will rely on, and the rules on keeping them are in the six year sales tax record rules. If the registration was only opened recently, what FBR can ask at that stage is listed in the documents FBR can ask for at sales tax registration.
A blacklisting order can be appealed within 30 days
Section 45B lets anyone aggrieved by an order under section 21 appeal to the Commissioner Inland Revenue (Appeals) within 30 days of receiving it. A late appeal may be admitted for sufficient cause. You can also go directly to the Appellate Tribunal Inland Revenue without using this step.
For an appeal that is not against an assessment, the fee in the Act is Rs 5,000 if the appellant is a company, and Rs 1,000 if not. The appeal must be in the prescribed form, verified and state the grounds precisely.
Do not wait for the final order to begin gathering papers. The 30 days run from receipt, and the order may arrive close to the end of the Commissioner's own 30 day window.
Common questions
How long can a registration stay suspended?
The Act sets no fixed period, but it does require a show cause notice within 10 days and an order within 30 days of your reply.
Can I file returns while suspended?
The Act does not say. Check the suspension order and the Board's procedure, and ask the Commissioner in writing if the order is silent.
Does suspension cancel my registration?
No. Suspension is temporary. The Commissioner can revoke it, or issue a blacklisting order after your reply and a hearing.
Are my customers affected?
Yes. Invoices issued during suspension are not entertained for refund or input tax credit. After blacklisting, credit on your invoices is rejected after a hearing.
Where do I appeal a blacklisting order?
To the Commissioner Inland Revenue (Appeals) within 30 days of receipt, or directly to the Appellate Tribunal Inland Revenue.
What is the difference between de-registration and blacklisting?
De-registration under section 21(1) is for a person not required to be registered. Blacklisting under section 21(2) is for fake invoices or fraud.
How we verified this
What we checked, where we read it, and what we could not confirm.
We read sections 21, 21A and 45B of the Sales Tax Act, 1990, amended up to 30 June 2026, published by the Federal Board of Revenue, on 12 October 2026. We did not read the Board's notified suspension procedure, so check it and your own order before you act. This page is general information, not legal advice.
About the author
Global Affairs & Political Economy Writer
Muhammad Hatim is a book lover who started writing because he enjoys it. At Pakistan Era he writes about international relations, geopolitics and the global economy, with a particular interest in South Asia and the forces behind current events.