How Much Tax Is Deducted From a Prize Bond or Lottery Win in Pakistan
Prize bond wins lose 15% to tax for filers and 30% for non-filers. Lottery and raffle wins lose 20% or 40%. See the rates, a payout table and how to check.
Tax is taken out of a prize bond win before you receive it: 15 per cent if you are on FBR's Active Taxpayers List, and 30 per cent if you are not. Lottery, raffle and quiz wins lose 20 per cent, or 40 per cent off the list. The tax is final, so nothing more is due on that prize.
A Rs 100,000 prize does not arrive as Rs 100,000. We read FBR's withholding tax rate card for tax year 2027 and the Income Tax Ordinance, 2001 on 15 October 2026, and the rates below come from them. If you hold bonds, the next draw date matters less than your tax status on the day you claim.
Prize bond wins lose 15 per cent if you are on the Active Taxpayers List
Section 156 makes whoever pays a prize bond prize deduct tax from the gross amount. The rate is 15 per cent for a person on the Active Taxpayers List and 30 per cent for a person not on it. The same rate applies to a crossword puzzle prize.
The basic rate of 15 per cent sits in Division VI of Part III of the First Schedule. The doubling for people who are not on the list comes from rule 1 of the Tenth Schedule, which raises the rate by 100 per cent. FBR's rate card shows both columns side by side.
The first thing to check is your own status. You can check your filer status with one SMS before you claim.
Lottery, raffle and quiz wins lose 20 per cent, or 40 per cent off the list
A lottery, a raffle, a quiz prize and a prize offered by a company to promote sales are taxed at 20 per cent of the gross amount. A person who is not on the Active Taxpayers List pays double, which is 40 per cent.
That covers the "win a car" draw at a shop and the quiz prize on a TV show, because the Ordinance names both kinds of winnings in section 156. The deduction is made by the company or person who pays the prize.
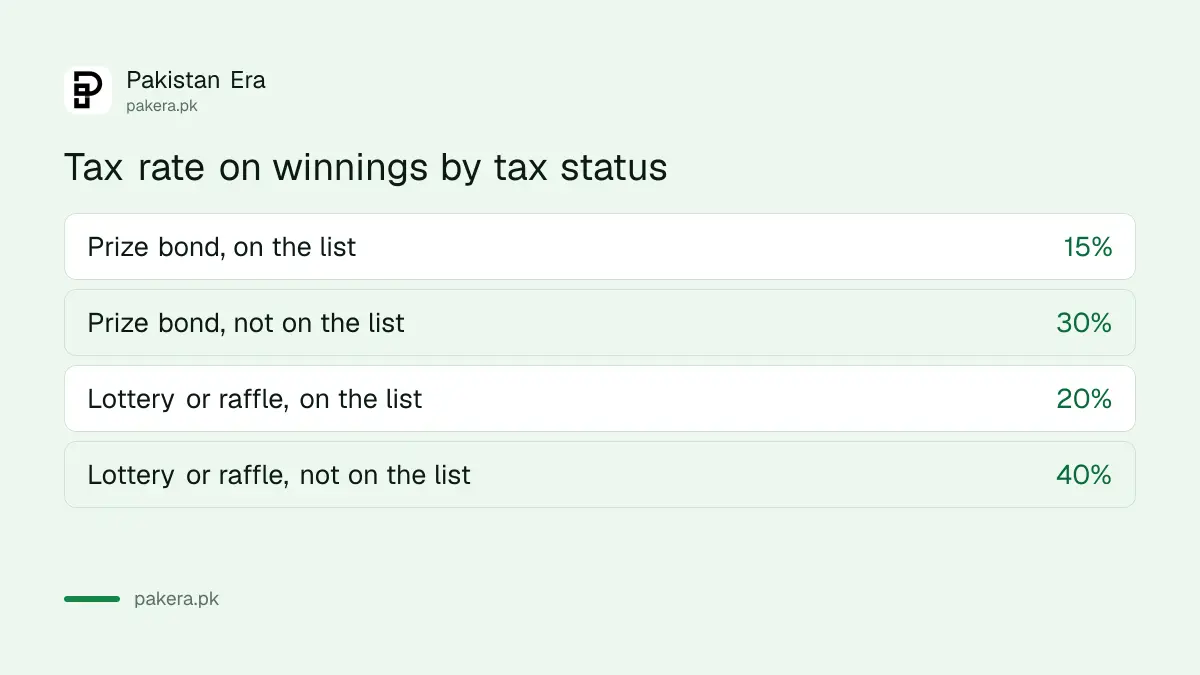
| Type of prize | On the Active Taxpayers List | Not on the list |
|---|---|---|
| Prize bond or crossword puzzle | 15% | 30% |
| Raffle, lottery, quiz, sales promotion prize | 20% | 40% |
The tax is final, so you owe nothing more on that prize
Section 156(3) says the tax deducted from a prize is a final tax on that income. The full tax on the prize is the amount already taken out, and the prize does not go into your normal slab calculation.
Section 39 of the Ordinance lists prize bond and lottery winnings as income from other sources, so they are income in law. We did not check how the current return form asks you to show final tax income, so follow the form or your accountant when you file.
Work out what you will actually receive
Multiply the gross prize by the rate, then subtract the result. The figures below are our own arithmetic on a Rs 100,000 prize, not an FBR example.
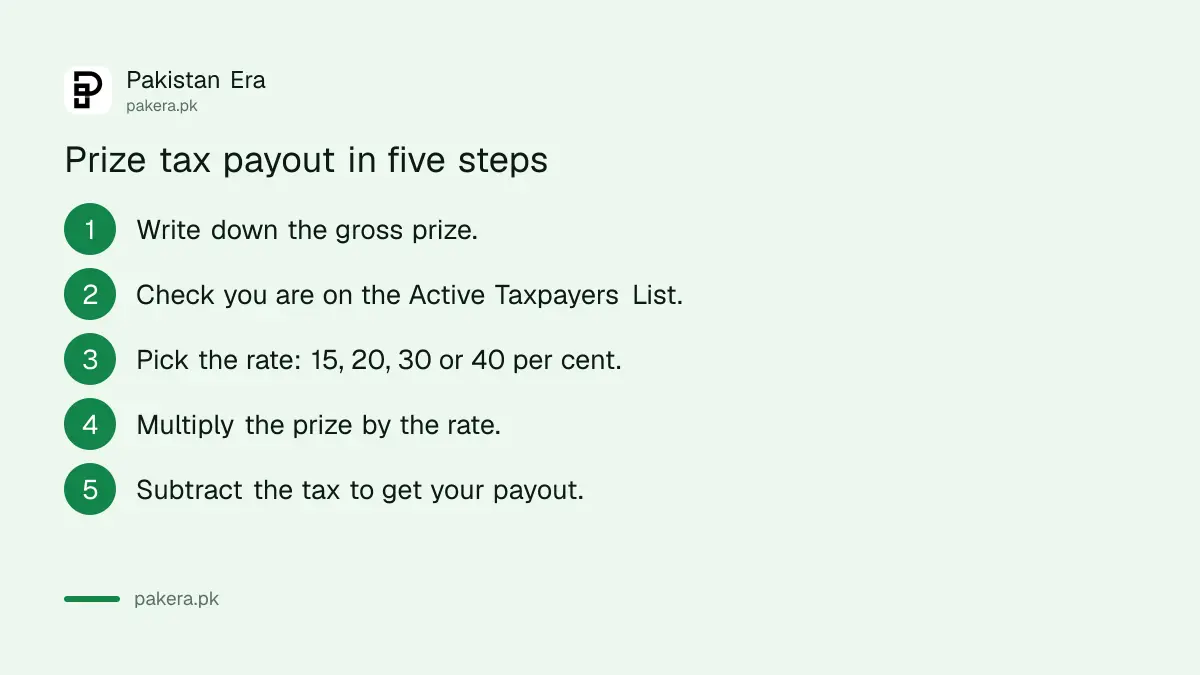
- Write down the gross prize announced for your bond or ticket.
- Check whether you are on the Active Taxpayers List today.
- Pick the rate from the table: 15, 20, 30 or 40 per cent.
- Multiply the gross prize by that rate to get the tax.
- Subtract the tax from the gross prize to get your payout.
| Rs 100,000 prize | Tax | You receive |
|---|---|---|
| Prize bond, on the list | Rs 15,000 | Rs 85,000 |
| Prize bond, not on the list | Rs 30,000 | Rs 70,000 |
| Lottery, on the list | Rs 20,000 | Rs 80,000 |
| Lottery, not on the list | Rs 40,000 | Rs 60,000 |
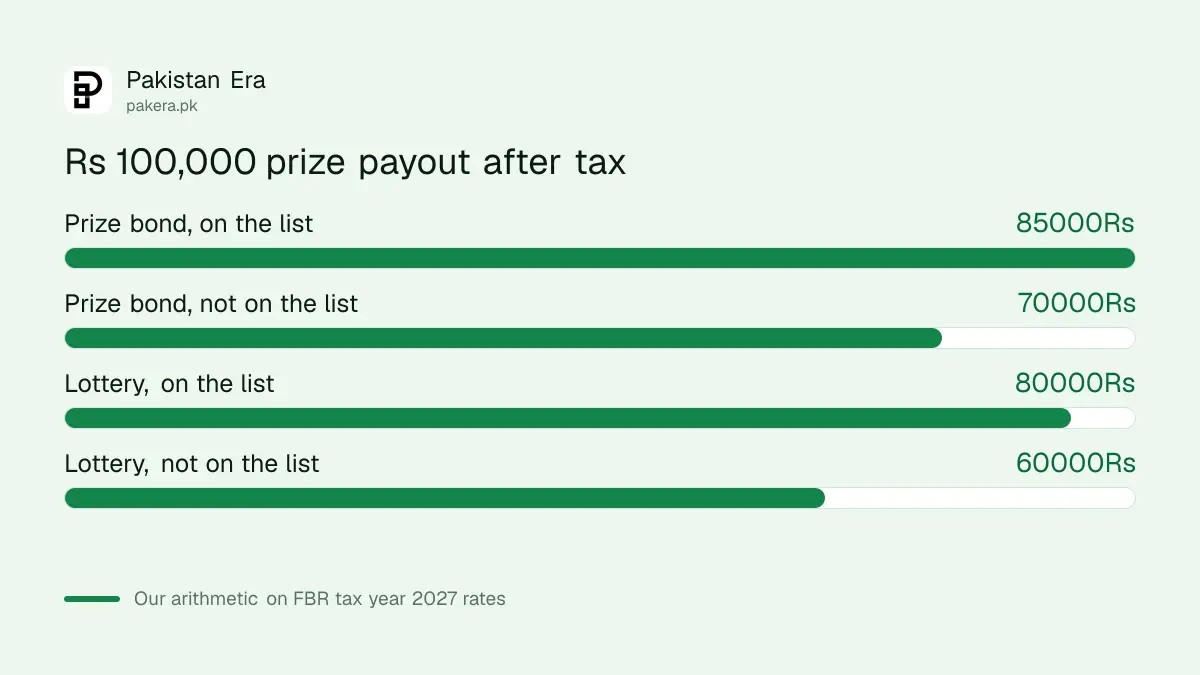
Check your status before you claim, because the gap is Rs 15,000 on every Rs 100,000
On a prize bond, being off the list costs an extra 15 per cent of the prize. On a prize of Rs 100,000, that is Rs 15,000. The list is not fixed, because FBR refreshes it.
The Active Taxpayers List after the 15 October deadline explains who stays on it and who drops off. If you are off it, the steps to become a tax filer come first, and then you can claim.
The Ordinance does not say on which day your status is read for a prize. The rate card does not say either. Treat the day of payment as the safe test, and check the day before. When you are ready to collect, the steps to claim a prize bond prize are the same whatever the tax.
A prize that is not cash is taxed on its market value
Section 156(2) covers a prize that is not cash, such as a motorcycle or an appliance. The person giving the prize must collect tax on the fair market value of the prize. Fair market value means the price it would ordinarily fetch in the open market.
That means a winner may be asked to pay the tax before taking the prize home. A prize worth Rs 200,000 at 20 per cent means Rs 40,000 in tax, on our arithmetic. Ask the organiser in writing what value they used.
Common questions about tax on prize bonds and lottery wins
Is tax deducted on a Rs 750 prize bond prize?
Yes. Section 156 applies to every prize bond prize, whatever the denomination. The rate is 15 per cent on the gross prize if you are on the Active Taxpayers List, and 30 per cent if you are not.
Do I pay tax if I am not a filer?
Yes, and it is higher. A person not on the Active Taxpayers List pays double: 30 per cent on a prize bond prize and 40 per cent on a lottery or raffle win.
Can I claim the deducted tax back?
Not as a refund of the extra rate. Section 156(3) makes the deduction final tax on that income. We found nothing in the Ordinance that returns the higher non-filer rate later.
Is a quiz show prize taxed too?
Yes. Section 156 names a prize on winning a quiz. It is taxed at 20 per cent, or 40 per cent for someone not on the Active Taxpayers List.
Who deducts the tax?
The person paying the prize. The Ordinance says every person paying a prize bond prize or winnings must deduct the tax from the gross amount before paying.
Does the rate change by prize size?
Not in FBR's rate card. It lists one rate for prize bond and crossword prizes and one for the other winnings, with no slabs by amount.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 15 October 2026. The rates come from FBR's Withholding Income Tax Rate Card, updated to 30 June 2026 under the Finance Act, 2026, and the legal text from the Income Tax Ordinance, 2001 on FBR's site, sections 39 and 156 and the Tenth Schedule. The rate card says the Ordinance prevails if the two differ. The payout examples are our own arithmetic. We did not claim a prize to test a deduction.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.