UBL Address Home Loan 2026: KIBOR Plus 3.5% Rate, Rs 150,000 Income Rule and Rs 12,000 Fee in Pakistan
UBL Address home loan 2026: KIBOR plus 3.5% salaried, plus 4% self-employed, about 16.55% in November, Rs 150,000 income, Rs 12,000 fee and 5% payoff charge.
UBL Address, United Bank's home loan in Pakistan, charges 1 year KIBOR plus 3.5% for salaried borrowers and KIBOR plus 4% for business people and professionals in 2026. With KIBOR at 13.05% on 30 October 2026, a November loan costs about 16.55% or 17.05%. You need income of at least Rs 150,000 a month and a loan of at least Rs 1 million.
UBL Address covers buying a house, building one, buying land and building on it, renovating, and moving an existing home loan from another bank. The rate floats: it is reset once a year, on each anniversary of the loan.
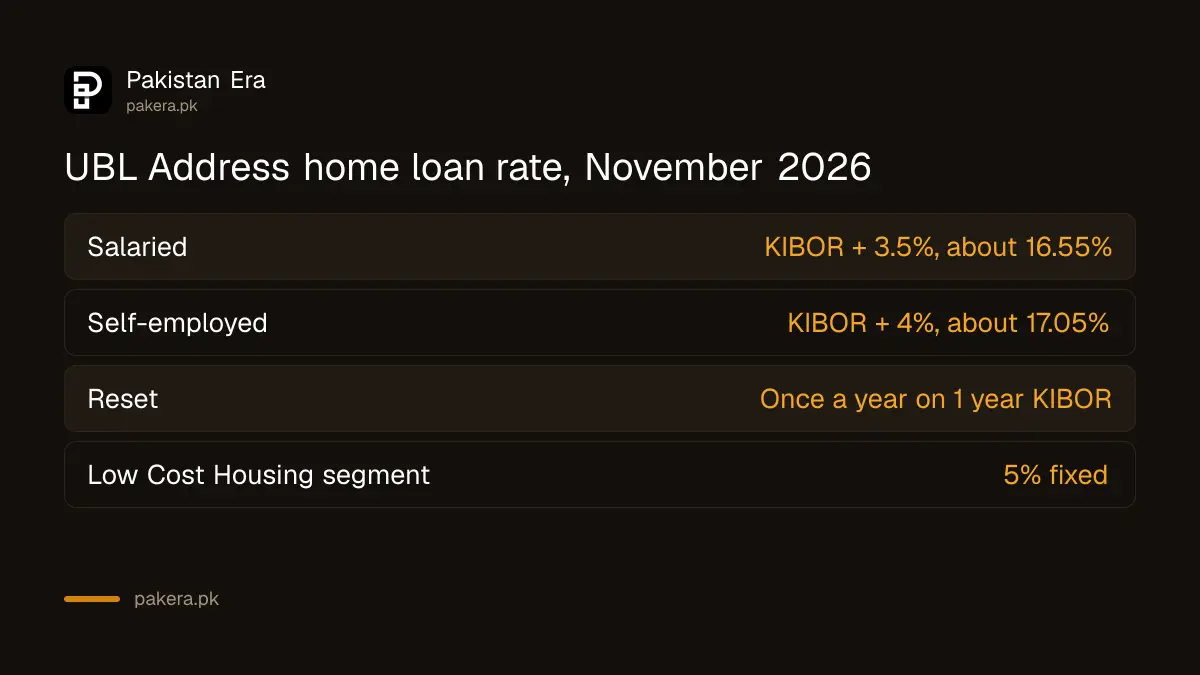
UBL Address markup is KIBOR plus 3.5% or 4%
Salaried borrowers pay 1 year KIBOR plus 3.5% and self-employed business people and professionals pay KIBOR plus 4%. UBL uses the 1 year KIBOR on the last working day of the month before booking, then before each anniversary, so the rate can go up or down yearly.
| Borrower | Rate | About, November 2026 |
|---|---|---|
| Salaried | 1 year KIBOR + 3.5% | 16.55% |
| Self-employed business person or professional | 1 year KIBOR + 4.0% | 17.05% |
| Low Cost Housing special segment | 5% fixed | 5% |
The November figures are our sums, using the 13.05% offer rate on Friday 30 October 2026, the last working day of October. A loan booked in December will use the KIBOR of 30 November. The Low Cost Housing segment is the State Bank's subsidised tier, which has its own rules and limits. The KIBOR rate today page shows where the benchmark stands now.
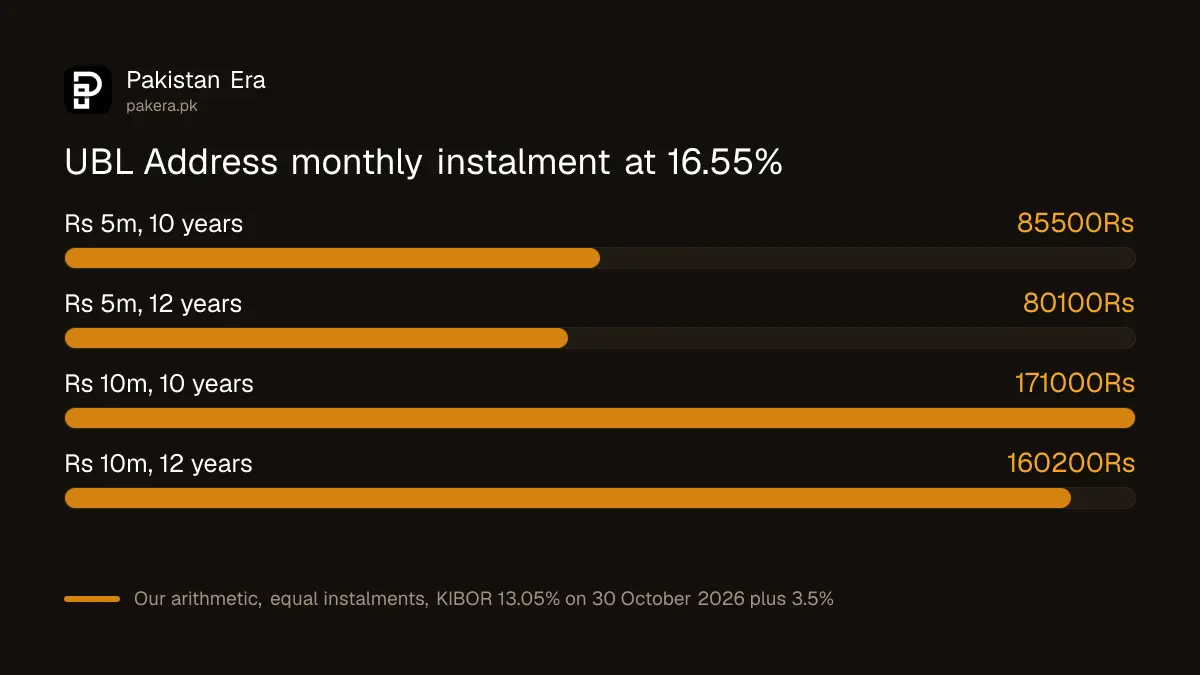
What a UBL Address home loan costs each month
On Rs 10 million over 10 years at 16.55%, the instalment is about Rs 171,000 a month. Over 12 years it drops to about Rs 160,200, but you pay about Rs 2.5 million more markup in total. These sums assume KIBOR stays at 13.05%.
| Loan | Tenure and rate | About a month | Total markup, about |
|---|---|---|---|
| Rs 5,000,000 | 10 years, 16.55% | Rs 85,500 | Rs 5.3 million |
| Rs 5,000,000 | 12 years, 16.55% | Rs 80,100 | Rs 6.5 million |
| Rs 10,000,000 | 10 years, 16.55% | Rs 171,000 | Rs 10.5 million |
| Rs 10,000,000 | 12 years, 16.55% | Rs 160,200 | Rs 13.1 million |
| Rs 10,000,000 | 12 years, 17.05%, self-employed | Rs 163,500 | Rs 13.5 million |
These are equal monthly instalment sums, not a bank quote. Every 1% rise in KIBOR adds about Rs 6,700 a month to a Rs 10 million, 12 year loan. Keep at least that much spare in your budget before you sign a floating loan.
UBL Address loan size, tenure and uses
The smallest UBL Address loan is Rs 1 million. The key fact statement caps it at Rs 100 million, or Rs 75 million when you move a loan from another bank, and gives a term of 1 to 12 years. Every purpose below uses the same pricing.
- Home purchase: buy a ready house or apartment.
- Build a home: construction on land you already own.
- Land plus construction: buy a plot and build on it.
- Home renovation: repair or extend your house.
- Balance transfer: move your home loan from another bank to UBL.
- Approved projects: financing in housing projects UBL has cleared.
Plot and construction loans are released in stages as building goes up, and each stage needs a site inspection. Read how that works at other banks too in our page on home loans for a plot and construction.
Who can get a UBL Address home loan
You must be a resident Pakistani, salaried or self-employed, aged 21 to 65. Every segment needs a monthly income of at least Rs 150,000, whether you work for a known company, a smaller employer or yourself. A co-borrower can join the loan.
| Requirement | Salaried | Self-employed business or professional |
|---|---|---|
| Minimum monthly income | Rs 150,000 | Rs 150,000 |
| Age | 21 to 65 | 21 to 65 |
| Work record | 2 years of employment confirmed | Proof of length of business |
| Bank statements | Last 12 months | Last 2 years |
| Tax record | Not listed | 3 years of tax returns |
Overseas Pakistanis apply under a separate UBL Address NRP plan and through UBL Roshan Apna Ghar. For the general rules every bank applies, including how much of your income can go on instalments, see home loan eligibility rules in Pakistan.
Documents for UBL Address
Everyone gives a CNIC copy, two recent photographs of each borrower and a signed letter of understanding that states the rate at booking. Salaried borrowers add salary and job proof. Business people add account, tax and company papers.
- Copy of CNIC and two recent photographs for the main borrower and each co-borrower.
- Signed letter of understanding showing the rate on the day the loan is booked.
- Salaried: current salary slip, salary certificate or employment letter confirming 2 years of work, 12 months of bank statements, and the previous employment letter if you changed jobs.
- Self-employed: company account maintenance certificate, 2 years of bank statements, 3 years of tax returns, and audited accounts or a partnership deed where they exist.
- The property's title papers, which UBL's lawyer checks and its appraiser values.
Your relationship manager tells you of any extra papers your profession needs. The property side is set out in our home loan documents list by property type.
UBL Address processing fee and payoff charges
The processing fee is Rs 12,000 for a new loan, Rs 6,000 for a balance transfer and Rs 15,000 for overseas Pakistanis, none refundable. Appraisal and legal work are at actual cost. A late instalment costs Rs 1,500 a month. Paying off in full costs 5% of the principal settled.
| UBL Address charge | July to December 2026 |
|---|---|
| Processing fee, new loan | Rs 12,000, non-refundable |
| Processing fee, balance transfer | Rs 6,000, non-refundable |
| Processing fee, overseas Pakistani | Rs 15,000, non-refundable |
| Property appraisal, legal work, stamp duty | At actual cost |
| Late payment | Rs 1,500 a month per late instalment |
| Property insurance | Premium paid by the bank |
| Full early payoff | 5% of principal settled |
| Partial payoff beyond the free limit | 5% of principal settled |
A partial payment between Rs 50,000 and 15% of the principal still owed carries no charge. Pay more than that at once and the 5% charge applies. Loans under the State Bank's subsidised Tier III have no early payoff charge. Cashier cheque and income estimation charges are extra.
Common questions
What is the UBL home loan interest rate in 2026?
1 year KIBOR plus 3.5% for salaried borrowers and plus 4% for the self-employed. With KIBOR at 13.05% on 30 October 2026, that is about 16.55% and 17.05%.
What is the minimum salary for UBL Address?
Rs 150,000 a month, for salaried borrowers at known and other companies and for self-employed applicants alike.
What is the UBL Address processing fee?
Rs 12,000 for a new loan, Rs 6,000 for a balance transfer and Rs 15,000 for overseas Pakistanis, under the July to December 2026 schedule of charges.
Can I prepay a UBL home loan?
Yes. Partial payments from Rs 50,000 up to 15% of the principal owed are free. A full payoff, or a larger part payment, costs 5% of the principal settled.
What is the smallest UBL Address loan?
Rs 1 million. The key fact statement allows up to Rs 100 million, and Rs 75 million for a balance transfer.
How do I contact UBL for a home loan?
Call the UAN, 111-825-888, or visit any UBL branch, which can take a UBL Address application.
How we verified this
What we checked and where we read it.
We read UBL's UBL Address page, the UBL Address key fact statement and section E of the schedule of charges for July to December 2026 on 15 November 2026. The key fact statement shows a Rs 10,000 plus FED processing fee, while the July to December 2026 schedule, which lists the fee as revised, shows Rs 12,000; we used the schedule. KIBOR is the State Bank's 1 year offer rate for 30 October 2026 as recorded on our KIBOR pages. Rates in percent and instalments are our arithmetic.
About the author
Tax, Bills and Technology Writer
Ali Akhtar is a young and curious voice here at Pakistan Era. He is currently pursuing his A-Levels and has a growing interest in Pakistan’s changing industrial landscape and educational trends. Ali likes to write in a way that helps him explain and explore the world around him. His writing reflects the perspective of the new generation navigating the evolving trends of Pakistan where technology, youth innovation, and shifting opportunities are reshaping the country’s future.