How to Withhold Sindh Sales Tax as a Withholding Agent: SRB's One-Fifth and Four-Fifths Rules
SRB withholding agents in Sindh keep one-fifth, four-fifths or all of the sales tax on a service bill. See who withholds, the forms, deposit dates and examples.
Short answer: If your company or office in Sindh pays for a taxable service, you are usually a withholding agent under SRB's Withholding Rules, 2014. A company keeps back one-fifth of the Sindh sales tax shown on a registered provider's invoice, a government office keeps back four-fifths, and anyone paying an unregistered provider keeps back the whole tax. The amount goes to Sindh's account B-02384 on a PSID challan.
Most firms get this wrong in one of two ways. They pay the full invoice and leave SRB to chase the provider, or they withhold the full tax when only a fifth was due. We read the Sindh Sales Tax Special Procedure (Withholding) Rules, 2014, as amended up to 1 July 2026, on SRB's website. Here is the short version.
Companies, government offices and SRB-registered buyers withhold
The rules name the withholding agents. They include federal, provincial and local government offices, autonomous bodies and state-owned enterprises not formed as companies, bodies funded from government budgets, and companies. SRB-registered persons also withhold when they buy from an unregistered or non-active provider.
Some cases apply to a wider group. FBR or SRB registered persons, plus the bodies above, withhold on advertising, on renting of immovable property and on auctioneers' services. Insurers withhold on services of insurance agents and brokers. Users of cab and truck aggregators are covered too, but the aggregator itself does the withholding there.
Location matters. You are a withholding agent only if you are resident in Sindh or have a place of business there. A person based in another province with no place of business in Sindh is covered only after signing up on Form SSTW-01.
How much to withhold depends on who you are and who you pay
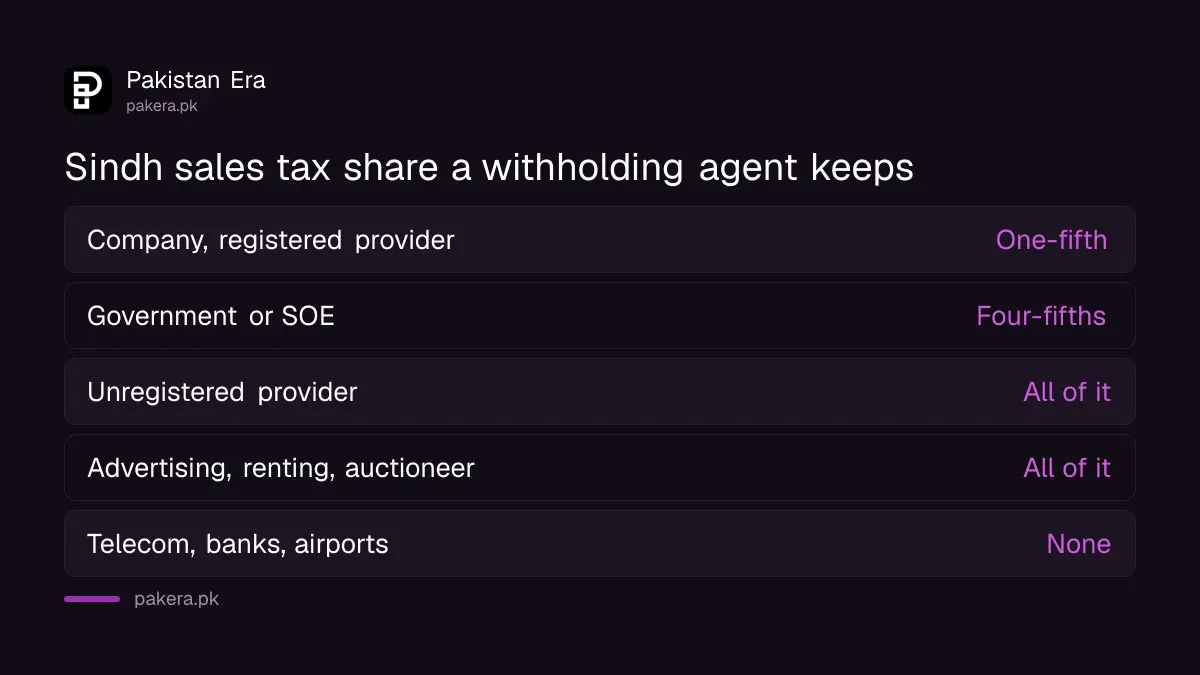
A company paying an SRB-registered provider withholds one-fifth of the sales tax on the invoice and pays the rest to the provider. A government office or autonomous body withholds four-fifths. For unregistered or non-active providers, advertising, renting and auctioneers, you withhold the full tax.
| Who pays | Who provides the service | Share of tax to withhold | Rule |
|---|---|---|---|
| Company or other agent | SRB-registered provider | One-fifth of the tax on the invoice | Rule 3(3) |
| Government office, autonomous body or SOE | SRB-registered provider | Four-fifths of the tax on the invoice | Rule 3(4A) |
| Any withholding agent | Unregistered or non-active provider | All of it, at the rate for that service | Rule 3(4) |
| FBR or SRB registered buyer | Advertising, renting of property, auctioneer | All of the tax on the invoice | Rule 3(5) |
| Any withholding agent | Telecom, banks, insurers, ports, airports, power transmission | None, the provider collects it | Rule 3(1) proviso |
Rule 3(3) gives its own example. A service worth Rs 1,000 carries Rs 150 in sales tax at 15 per cent. The company withholds Rs 30, which is one-fifth, and pays the provider Rs 1,120. On a Rs 200,000 invoice with Rs 30,000 tax, the same rule means withholding Rs 6,000 and paying Rs 224,000.
If the invoice does not show the tax, work it out from the gross amount with the tax fraction. At 15 per cent, the tax inside a gross bill is 15 divided by 115 of it. So a Rs 115,000 bill holds Rs 15,000 of tax.
Sign up, give notice and keep the paperwork
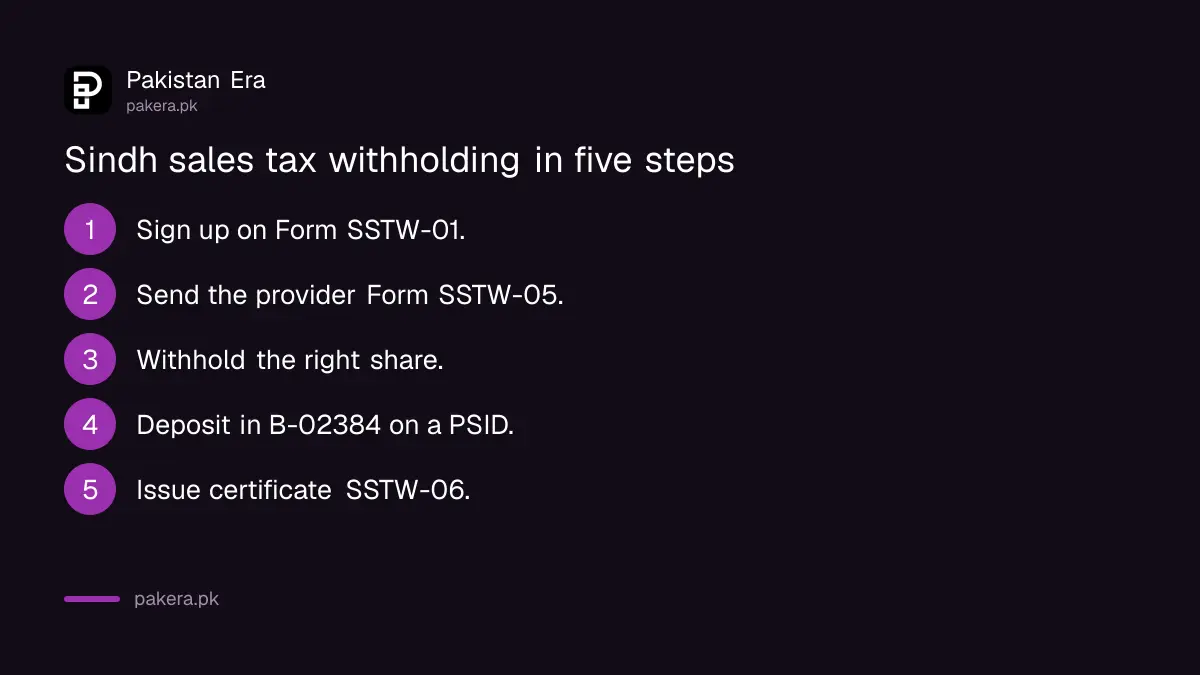
If you are not already registered with SRB as a service provider, sign up as a withholding agent on Form SSTW-01 to get a user ID, password and PIN. Tell each provider in advance, on Form SSTW-05, that you will withhold. After you withhold, give the provider a certificate on Form SSTW-06.
- Check whether you are a withholding agent under rule 1(2), and whether you are in Sindh or have a place of business there.
- If you are not SRB-registered, e-file Form SSTW-01 to sign up as a withholding agent.
- Send the provider a notice on Form SSTW-05 before you receive the service.
- Check the provider's status on SRB's taxpayer search before each payment.
- Work out the share to withhold from the table above and pay the provider the balance.
- Deposit the withheld tax in account B-02384 on a PSID challan, Form SST-04 or SSTW-04.
- Report it in your SST-03 return, or in Form SSTW-03 if you are not SRB-registered.
- Issue the provider a certificate on Form SSTW-06 with its name, number, the service and the tax withheld.
For an unregistered provider, keep a copy of its CNIC if it is an individual, or its NTN certificate if it is a firm or company. Enter its name, CNIC and NTN in your return. The SRB taxpayer search is the quickest way to see if a provider is registered and active.
Deposit dates depend on whether you are SRB-registered
An SRB-registered agent deposits the withheld tax by the due date of the month in which it claims the input tax, or on the day it pays the provider, whichever comes first. Other agents deposit by the 15th of the second month after the invoice month, or on the payment date if that is earlier.
Take an invoice dated in October 2026 and paid in January 2027. A company that is not SRB-registered must deposit by 15 December 2026, because that comes before the payment. If it paid the provider on 20 November, it would deposit on 20 November.
An SRB-registered agent that does not claim the input within four months of the invoice must deposit on the payment date or within four months of the invoice, whichever is earlier. Government accounting offices follow their own route through the AGPR, Accountant General or District Accounts Officer, and the DDO files Form SSTW-03 by the 18th.
Late deposit carries default surcharge under section 44 of the Act, at the inter-bank rate plus 3 per cent a year. If you are also SRB-registered, the withheld tax goes in your own SST-03 return, and you do not file SSTW-03 separately.
Providers must not let the wrong buyer withhold
A registered provider must issue a proper tax invoice to every withholding agent. It should allow withholding only by buyers that are real agents under rule 1(2) and have sent Form SSTW-05. If it lets someone else withhold, the provider pays the tax and default surcharge itself.
The provider then claims credit, in its own SST-03, for the tax its customers withheld. Keep each SSTW-06 certificate on file, because it is your proof. Punjab runs a similar system, and its sales tax withholding statement on PRA's portal works differently, so do not copy one province's practice into the other.
Common questions
How much Sindh sales tax does a company withhold?
One-fifth of the sales tax shown on an SRB-registered provider's invoice, under rule 3(3). On Rs 150 of tax that is Rs 30.
How much does a government department withhold?
Four-fifths of the sales tax on the invoice, under rule 3(4A), for offices and autonomous bodies covered by clauses (a) and (b).
What if the provider is not registered with SRB?
Withhold the whole sales tax at the rate for that service, worked out from the gross amount with the tax fraction. Keep the provider's CNIC or NTN copy.
Which services are not subject to withholding?
Telecom, electric power transmission, banking, financial institutions, insurance companies other than reinsurers, port and airport operators, terminal operators and airport ground services, because the provider collects the tax itself.
Where do I deposit the withheld tax?
In the Sindh Government account B-02384, on a PSID challan in Form SST-04 or SSTW-04.
Which form proves the tax was withheld?
Form SSTW-06, the withholding certificate the agent gives the provider.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 20 October 2026. We read rules 1 to 4 of the Sindh Sales Tax Special Procedure (Withholding) Rules, 2014 (amended up to 1 July 2026) and section 44 of the Sindh Sales Tax on Services Act, 2011 on SRB's site. The Rs 200,000 and Rs 115,000 examples and the October invoice dates are our own arithmetic on those rules. SRB's copy is marked "E&OE" and some clause letters in it are hard to read, so check the exact clause that covers you with SRB on UAN 021-111-778-000 before you rely on it.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.