Withholding Tax Rates 2026-27 in Pakistan: FBR Rate Card for Goods, Services, Contracts and Imports
Withholding tax rates 2026-27 in Pakistan from FBR's rate card: goods 5%, contracts 7.5%, services 4% to 15%, imports 1% to 6%, double for non-ATL. Full list.
FBR's withholding tax rate card for 2026-27 (tax year 2027) sets 5% on payments for goods to a company, 7.5% on contracts with a company and 1% to 6% on imports, for payees on the Active Taxpayers List. For a payee who is not on the list, the rate is usually doubled.
We read the card FBR's Directorate General of Withholding Taxes published, updated to 30 June 2026 under the Finance Act 2026, on 28 October 2026. Below are the rates a business, shop or office is most likely to apply when it pays someone, with a worked example and the order of checks before you deduct.
FBR's rate card for tax year 2027 covers every payment
The withholding tax rate card is FBR's one-page summary of every rate a payer must deduct under the Income Tax Ordinance, 2001. The current card is for tax year 2027, meaning payments from 1 July 2026 to 30 June 2027. Each rate has two columns: ATL, for payees on the Active Taxpayers List, and non-ATL.
FBR says plainly that the card is a help, not the law. Where the card and the Ordinance differ, the Ordinance wins, and the card cannot be produced in court. We checked the rates we use below against the card's own sources.
Supplies, services and contracts are taxed under section 153
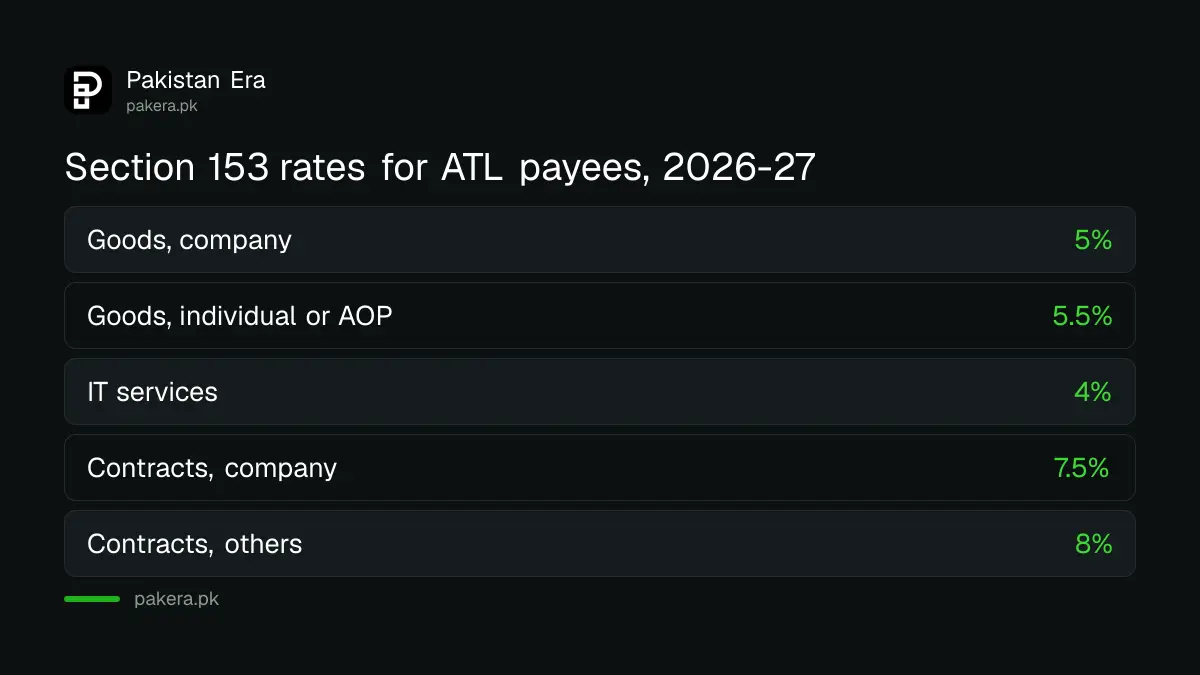
Section 153 covers what most businesses pay out every month. Goods supplied by a company carry 5% (10% non-ATL), and by anyone else 5.5% (11%). Contracts with a company carry 7.5% (15%), and with anyone else 8% (16%). Services range from 4% to 15%.
| Payment under section 153 | ATL | Non-ATL |
|---|---|---|
| Supply of goods by a company | 5% | 10% |
| Supply of goods by an individual or AOP | 5.5% | 11% |
| Sale of rice, cotton seed or edible oils | 1.5% | 3% |
| Toll manufacturing, company / others | 9% / 11% | 18% / 22% |
| IT and IT enabled services | 4% | 8% |
| Certain services listed in the schedule | 7% | 14% |
| Other services | 14% | 28% |
| Doctors, lawyers, architects, accountants, independent developers | 15% | 30% |
| Advertising paid to electronic and print media | 1.5% | 3% |
| Contracts with a company | 7.5% | 15% |
| Contracts with anyone else | 8% | 16% |
| Contracts with sportspersons | 15% | 30% |
| Services to exporters or export houses | 1% | 2% |
Online orders have their own line. When a payment intermediary pays a seller for goods or services ordered online, the rate is 1% (2% non-ATL). When a courier collects cash on delivery, it is 2% (4%).
Imports carry 1% to 6% at the port under section 148
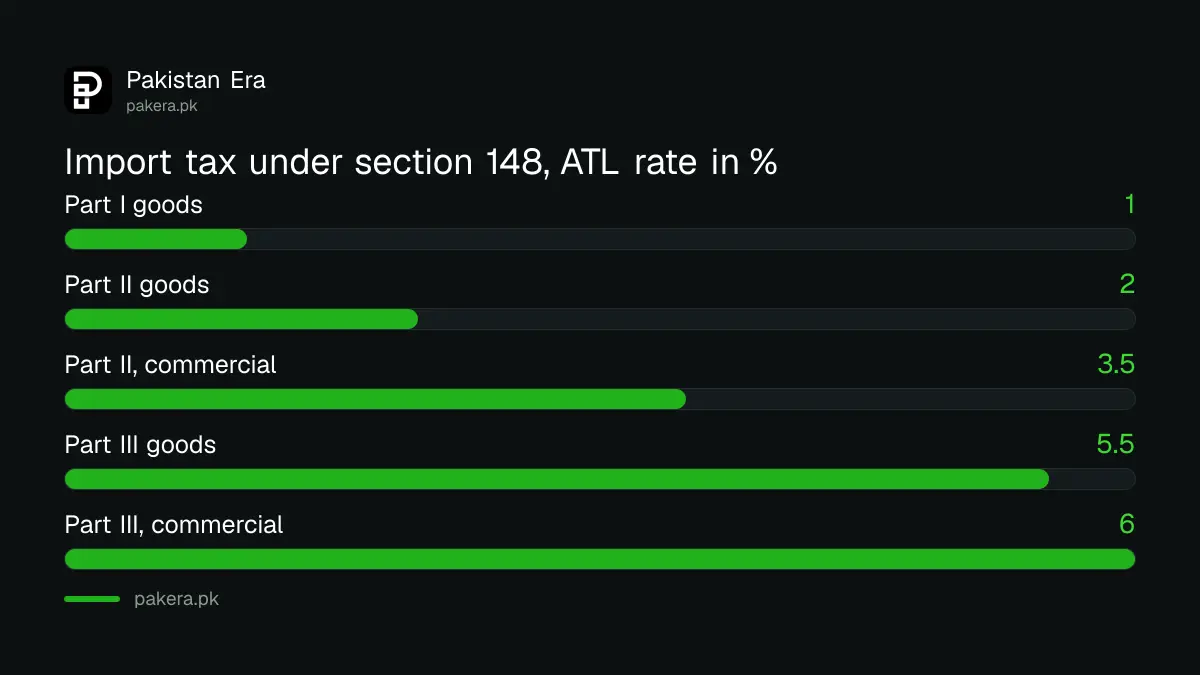
Customs collects section 148 tax on imports by the goods' place in the Twelfth Schedule. Part I goods carry 1% (2% non-ATL), Part II goods 2% (4%), and Part III goods 5.5% (11%). A commercial importer pays more: 3.5% (7%) in Part II and 6% (12%) in Part III.
Three special cases sit lower. Certain manufacturers under SRO 1125(I)/2011 and CKD kits for electric vehicles pay 1% (2%). Pharmaceutical products pay 4% (8%). Mobile phones pay a fixed amount per set instead, Rs 70 to Rs 11,500 for one tariff code on the card.
Distributors, retailers, commission and rent have their own rates
A manufacturer or distributor selling to a distributor, dealer or wholesaler collects 0.1% under section 236G (2% non-ATL), or 0.25% on fertiliser (0.7%). Sales to retailers under section 236H carry 0.5% (2.5%). Commission under section 233 is 12% (24%), 10% for advertising agents.
| Payment | Section | ATL | Non-ATL |
|---|---|---|---|
| Sales to distributors, dealers, wholesalers | 236G | 0.1% (fertiliser 0.25%) | 2% (fertiliser 0.7%) |
| Sales to retailers | 236H | 0.5% | 2.5% |
| Brokerage and commission, general | 233 | 12% | 24% |
| Advertising agents | 233 | 10% | 20% |
| Life insurance agents under Rs 0.5 million a year | 233 | 8% | 16% |
| Rent paid to a company | 155 | 15% | 30% |
| Sale of petroleum products | 156A | 12% | 24% |
| Sale of goods by public auction | 236A | 10% | 20% |
| Exports | 154 | 1.25% | Not listed |
Rent paid to an individual follows slabs instead, from nil up to Rs 300,000 a year to Rs 155,000 plus 25% above Rs 2 million. The tax to deduct from rent in 2026-27 covers those slabs and who must deduct.
Paying a non-resident uses section 152
Section 152 sets the rates when a Pakistani business pays someone abroad. The general rate for royalties and fees for technical services is 15%. For a contract for goods it is 5% for a company or 5.5% for others; for IT services 4%; for other services 8%; all doubled where the payee is not on the ATL.
The card lists more than a dozen sub-sections for non-residents, including capital gains through foreign currency value accounts and sukuk. If the payee claims a lower rate under a tax treaty, the card is not enough on its own; read the treaty or ask a tax adviser.
Paying Rs 1 million to a supplier, worked out
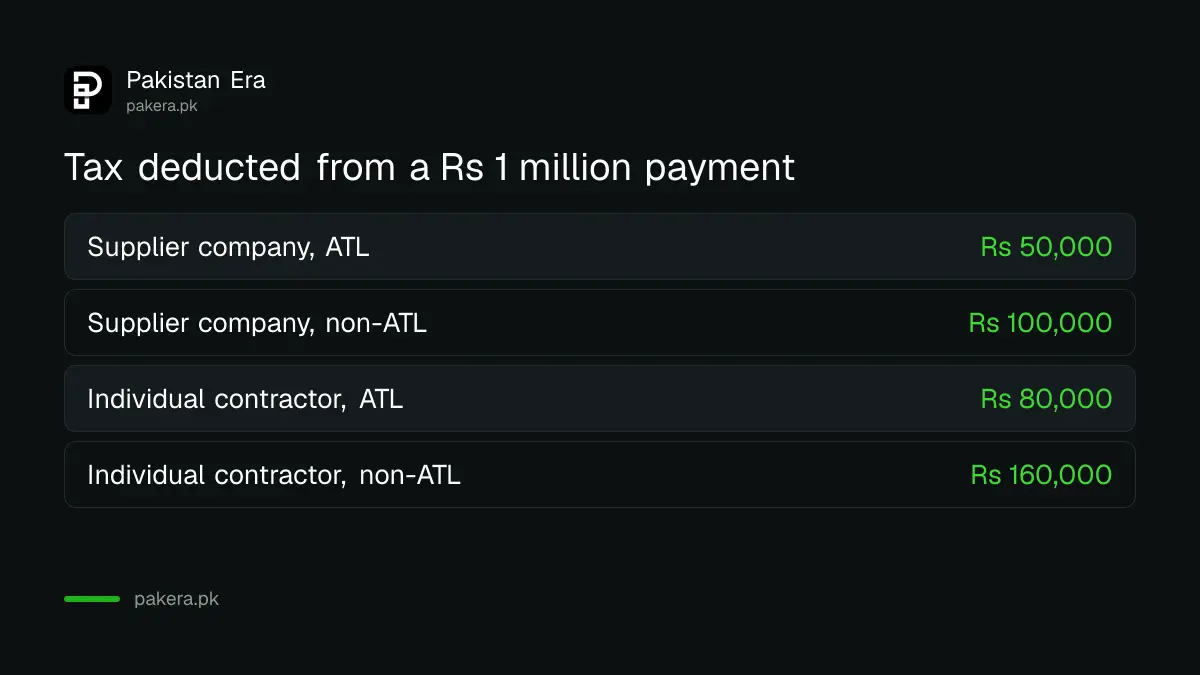
If your business pays a supplier company Rs 1,000,000 for goods, you deduct Rs 50,000 when the supplier is on the ATL and pay it Rs 950,000. If it is not on the ATL, you deduct Rs 100,000. On a Rs 1,000,000 contract with an individual contractor the deductions are Rs 80,000 and Rs 160,000.
Getting the column wrong costs the payer, not just the payee. FBR's penalty for failing to deduct is Rs 40,000 or 10% of the tax, whichever is higher. Do these five checks before every payment.
- Find the section that matches the payment: goods, service, contract, rent, commission or import.
- Check the payee's NTN or CNIC on FBR's Active Taxpayers List on the day you pay.
- Ask whether the payee holds an exemption or reduced rate certificate under section 159.
- Apply the ATL or non-ATL rate to the gross amount, before sales tax unless the law says otherwise.
- Deposit the tax with a PSID and report it in your quarterly withholding statement.
A payee with a section 159 certificate can have a lower rate or none. The quarterly withholding statement is where every deduction ends up.
Common questions
What is the withholding tax on supply of goods in 2026-27?
5% for a company and 5.5% for an individual or AOP on the ATL, and 10% and 11% for those not on it, under section 153(1)(a).
What is the withholding tax on services in 2026-27?
It depends on the service: 4% for IT services, 7% for certain listed services, 14% for other services and 15% for independent professionals, doubled for non-ATL payees.
What is the withholding tax on contracts?
7.5% for a company and 8% for others on the ATL, 15% and 16% if not.
What is the withholding tax on export proceeds?
The card lists 1.25% under section 154 on export proceeds. IT exporters registered with the Pakistan Software Export Board pay 0.25% under section 154A until tax year 2029.
Where do I download the FBR withholding tax rate card?
On FBR's Withholding Tax Rate Cards page, in PDF and Excel, under the Directorate General of Withholding Taxes.
Does the card replace the Income Tax Ordinance?
No. FBR says the Ordinance prevails in any contradiction and the card cannot be used in legal proceedings.
How we verified this
What we checked, where we read it, and what we could not confirm.
We read the FBR Withholding Tax Rate Cards page and the tax year 2027 card in its Excel and PDF forms on 28 October 2026. The worked example is our arithmetic. We did not check each rate against every schedule of the Ordinance, the full list of "certain services" in the schedule, or any SRO issued after 30 June 2026 that may change a rate.
About the author
Tax, Bills and Technology Writer
Ali Akhtar is a young and curious voice here at Pakistan Era. He is currently pursuing his A-Levels and has a growing interest in Pakistan’s changing industrial landscape and educational trends. Ali likes to write in a way that helps him explain and explore the world around him. His writing reflects the perspective of the new generation navigating the evolving trends of Pakistan where technology, youth innovation, and shifting opportunities are reshaping the country’s future.