Advance Tax on Auction Purchases in Pakistan: 10% on Cars and Goods, 5% on Plots, Double for Non-Filers
Section 236A: buyers at customs, government and property auctions in Pakistan pay 10% advance tax, 5% on plots, double for non-filers. How to claim it back.
If you win an auction in Pakistan, the seller must collect advance income tax from you at 10% of the sale price, under section 236A of the Income Tax Ordinance. For immovable property, such as a plot auctioned by a development authority, the rate is 5%. A buyer who is not on FBR's Active Taxpayers List pays double: 20%, or 10% for property. The tax counts as advance tax paid in your return.
The rule covers customs auctions of cars and goods, government vehicle auctions, plot auctions, bank auctions of attached property and leases sold by tender. We read section 236A, the rate in Division VIII of the First Schedule, the exemption clause and the non-filer rule, all as amended up to the Finance Act 2026.
Every public auction carries 10% advance tax
Section 236A applies to any person selling property or goods by public auction or by tender, including confiscated or attached goods. It names government, local government, authorities, companies, the Collector of Customs, the Commissioner Inland Revenue and any other authority. The seller collects the tax from the buyer.
The tax is worked out on the sale price. On a car won at a customs auction for Rs 2,000,000, a filer pays Rs 200,000 in advance tax on top of the bid. A non-filer pays Rs 400,000.
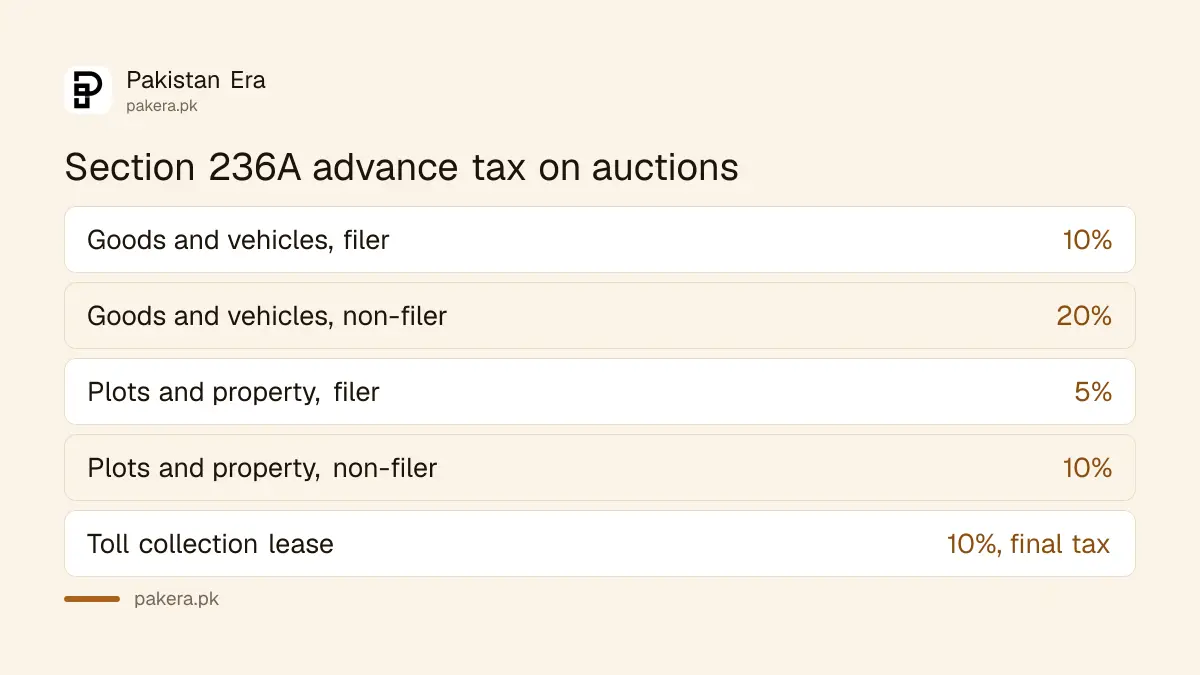
| What is auctioned | Filer on the ATL | Not on the ATL |
|---|---|---|
| Goods, vehicles, scrap, licences, leases | 10% of sale price | 20% of sale price |
| Immovable property (plots, houses, shops) | 5% of sale price | 10% of sale price |
| Train management services by Pakistan Railways | 5% of sale price | 10% of sale price |
| Lease of the right to collect tolls | 10%, final tax | 20%, final tax |
| Sports league team franchise rights | Not collected | Not collected |
Property auctions pay 5%
The proviso to Division VIII sets 5% instead of 10% for immovable property sold by auction, and for auctions of train management services by Pakistan Railways. A plot won from a development authority for Rs 10,000,000 carries Rs 500,000 of advance tax for a filer.
For a buyer not on the ATL, the same plot carries Rs 1,000,000. Property buyers should also check the separate rules on tax on buying and selling property, which apply to ordinary transfers.
Licences, leases and instalments are included
The section's explanation says a sale by auction includes the renewal of a licence first sold by auction, and the award of any lease, including the right to collect tolls, fees or levies. Where the price is paid in instalments, the tax is collected with each instalment.
- Licence renewals: a shop, parking or vending licence first sold by auction attracts the tax again on renewal.
- Leases: a lease awarded by auction or tender, such as a cattle market or parking stand contract, is a sale for this section.
- Tolls: tax on a lease of the right to collect tolls is a final tax, not adjustable.
- Instalments: if you pay the bid in three parts, the seller collects the tax three times, on each part.
Franchise rights for teams in a national or international sports league, run by a board set up by the government, are exempt from section 236A under clause 95A of Part IV of the Second Schedule.
How to pay 10% and not 20%
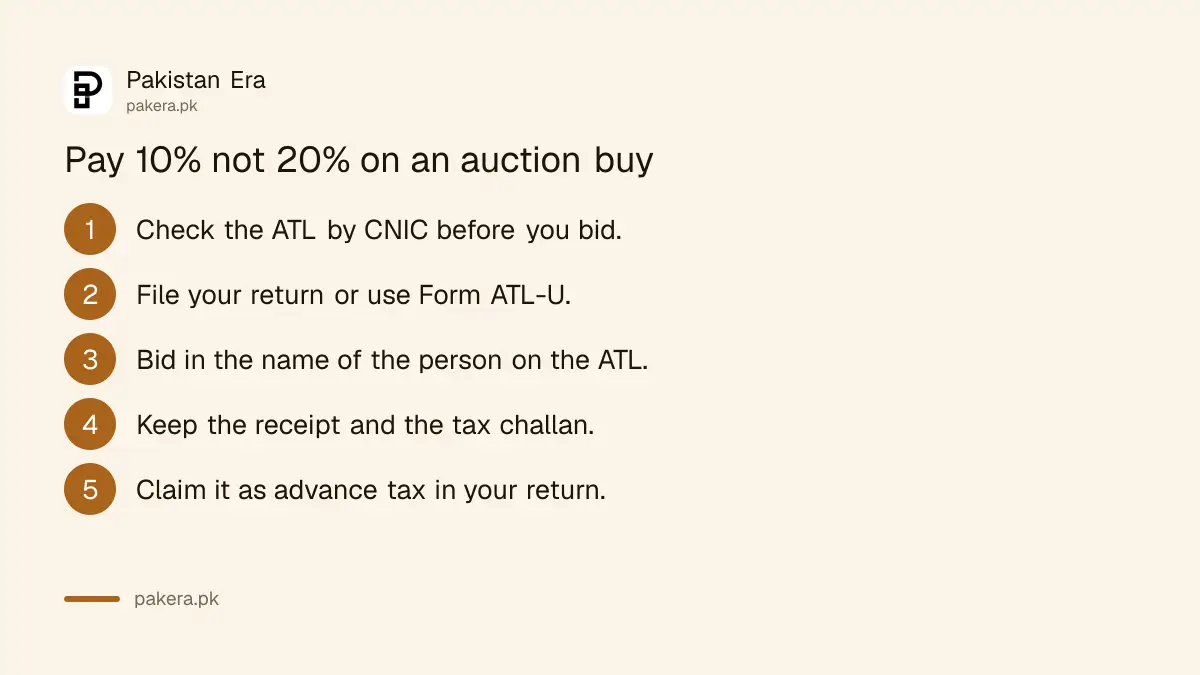
Rule 1 of the Tenth Schedule doubles the rate for anyone not on the Active Taxpayers List. Since the tax is worked out on the whole bid, being on the list before the auction day can save lakhs of rupees on a single car or plot.
- Check your name on the Active Taxpayers List by CNIC before you register to bid.
- If you are missing, file your return. Late filers can use Form ATL-U to join the list.
- Bid in the name of the person on the ATL, with that person's CNIC on the bid form.
- Keep the auction receipt and the advance tax challan from the seller.
- Claim the tax as advance tax in your return for that tax year.
Customs auctions have their own bidding steps, deposit and appeal rules. The process to bid at a customs auction, inspect the goods and sign the undertaking comes before the tax is collected.
Claim the advance tax in your return
Subsection (2) gives the buyer credit for the tax collected, subject to section 147, when working out the tax payable for that tax year. In plain terms, it is advance tax: it reduces your income tax for the year, and any excess can be part of a refund claim.
The credit depends on the seller actually depositing the tax against your CNIC. Under the Finance Act 2026, you get credit only for tax actually deposited. A car bought at auction also needs registration, where the advance tax on vehicle registration is a separate charge under a different section.
Common questions
What is section 236A advance tax?
It is advance income tax that a seller at a public auction or tender collects from the buyer, at 10% of the sale price, or 5% for immovable property.
How much tax do I pay on a customs auction car?
10% of the sale price if you are on the Active Taxpayers List, and 20% if you are not. Vehicle registration charges are separate.
Is the auction tax adjustable?
Yes, except on leases of the right to collect tolls, where it is final. Otherwise it is credited against your income tax for the year.
What is the advance tax on a plot bought at auction?
5% of the sale price for a filer and 10% for a buyer not on the Active Taxpayers List.
Is tax collected on each instalment of an auction price?
Yes. Where payment is made in instalments, the section requires advance tax to be collected with each instalment.
Are sports league franchise auctions taxed under 236A?
No. Clause 95A exempts franchise rights for teams in national or international leagues run by a government-established sports board.
How we verified this
What we checked and where we read it.
Last checked 15 November 2026. Section 236A, Division VIII of Part IV of the First Schedule, clause 95A of Part IV of the Second Schedule and rule 1 of the Tenth Schedule come from the Income Tax Ordinance 2001 as amended up to the Finance Act 2026, published by FBR. Worked examples are our own arithmetic.
About the author
Tax, Bills and Technology Writer
Ali Akhtar is a young and curious voice here at Pakistan Era. He is currently pursuing his A-Levels and has a growing interest in Pakistan’s changing industrial landscape and educational trends. Ali likes to write in a way that helps him explain and explore the world around him. His writing reflects the perspective of the new generation navigating the evolving trends of Pakistan where technology, youth innovation, and shifting opportunities are reshaping the country’s future.