How to Appeal to the Appellate Tribunal Inland Revenue in Pakistan: 30 Days, Rs 20,000 Fee
File an FBR tax appeal at the Appellate Tribunal Inland Revenue within 30 days. Fee is Rs 20,000 for companies, Rs 5,000 for others. Stay lasts 90 days.
If the Commissioner (Appeals) rules against you on an income tax order, you can appeal to the Appellate Tribunal Inland Revenue within 30 days of receiving the order. The fee is Rs 20,000 for a company and Rs 5,000 for anyone else, and the Tribunal must decide the appeal within 90 days of filing.
A salaried person with a rejected refund, a shopkeeper with an amended assessment and a company with a disallowed expense all end up at the same place if the first appeal fails. The deadline there is shorter than many taxpayers remember. It used to be 60 days. The Income Tax Ordinance, 2001 as amended up to 30 June 2026 says 30.
We read sections 130 to 133 of the Ordinance, as published on FBR's Income Tax Ordinance page on 21 October 2026. That page lists the consolidated text amended up to 30 June 2026. The first appeal is covered in the guide on appealing an FBR income tax order to the Commissioner (Appeals).
The deadline is 30 days from service of the order
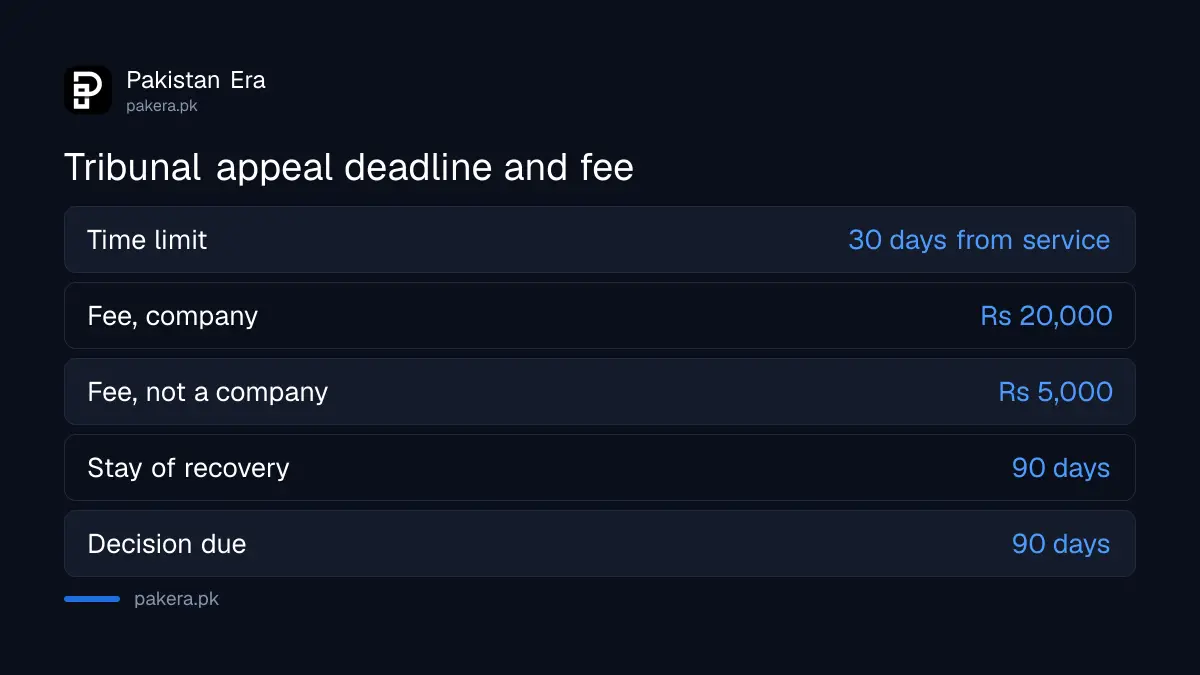
Section 131(2)(d) requires the appeal to be filed within 30 days of service of the order on the taxpayer. The Commissioner can also appeal an order of the Commissioner (Appeals), and has the same limit. The Tribunal may admit a late appeal if you were prevented by sufficient cause, on written application.
The text we read also shows an older version with 60 days. The Tax Laws (Amendment) Act, 2024 and later changes shortened it, and the footnotes record the earlier wording. Count from the day the order was served, then file well before the 30th day.
| Item | What section 131 says |
|---|---|
| Who may appeal | The taxpayer or the Commissioner |
| Time limit | 30 days from service of the order |
| Fee, company | Rs 20,000 |
| Fee, not a company | Rs 5,000 |
| Late appeal | May be admitted for sufficient cause |
| Form | Prescribed form, verified in the prescribed manner |
You can sometimes skip the Commissioner (Appeals)
The proviso to section 131(1) lets a taxpayer appeal directly to the Tribunal against an order of the Officer Inland Revenue or the Commissioner, by using the option in section 127(1). Under that option, you give up your right of appeal before the Commissioner (Appeals) and go to the next forum.
It is a one-way choice. Do not use it just to save time. A direct appeal to the Tribunal costs more at filing and the stay rules are tighter than at the first stage.
Recovery is not paused automatically
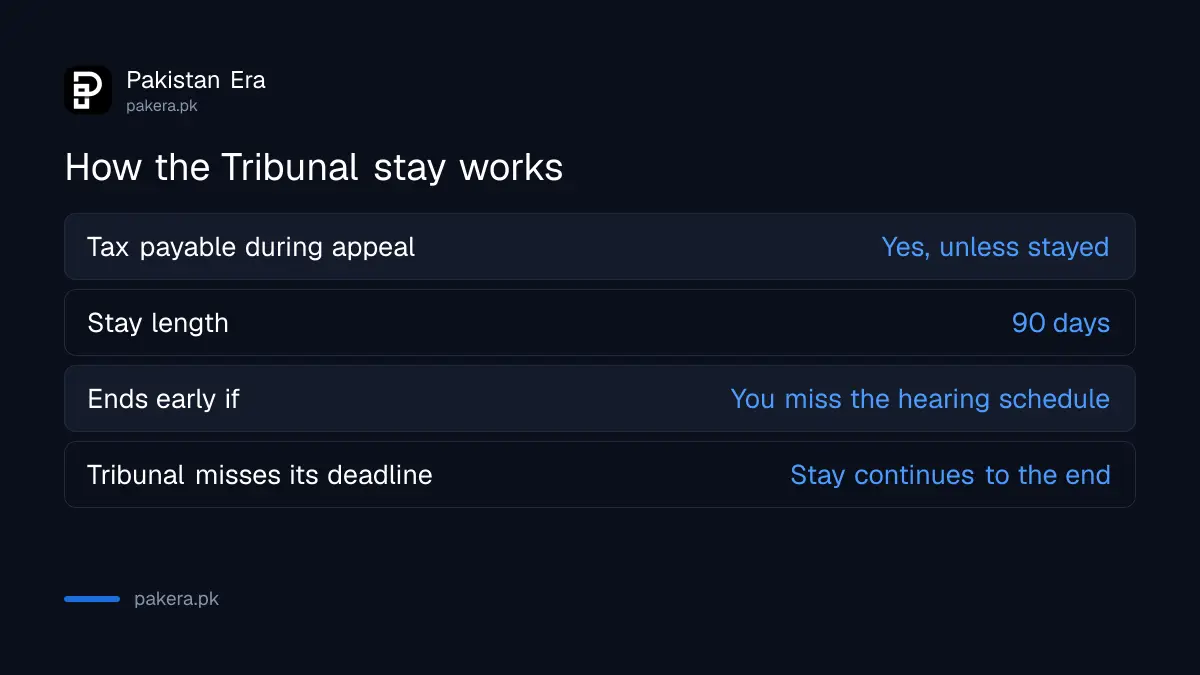
Section 131(5) says tax stays payable under the assessment unless the Tribunal stays recovery. On an application, the Tribunal may stay recovery for 90 days after hearing the Commissioner, for reasons it records.
Two conditions follow. The stay ends if you do not follow the hearing schedule the Tribunal sets. And if the Tribunal fails to decide within its statutory period, the stay does not end until the Tribunal finalises the appeal. That protects a taxpayer who is ready but waiting. Our guide on a section 140 bank recovery notice explains what happens when recovery goes ahead.
The Tribunal must decide in 90 days and offer dispute resolution first
Section 132(1) requires the Tribunal to decide an appeal within 90 days of filing. Appeals that were pending when the 2024 amendment took effect had 180 days. If the Tribunal misses the period, it must seek condonation from the Minister of Law and Justice, and the condonation cannot go beyond 90 days.
At the first hearing, the Tribunal must tell you about alternative dispute resolution under section 134A. If you decline and continue, it fixes the hearing dates with you and the Commissioner, and adjournments are allowed only for compelling reasons. The option itself is covered in the guide to FBR alternative dispute resolution.
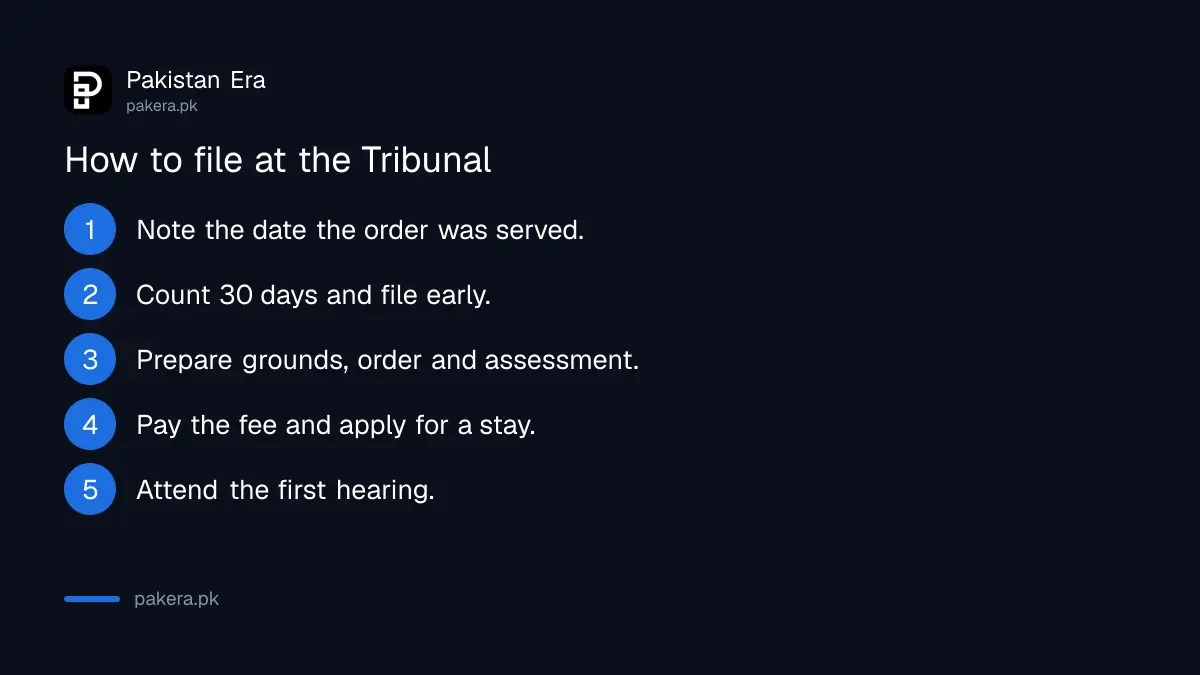
- Note the date the Commissioner (Appeals) order was served.
- Count 30 days and set an earlier internal deadline.
- Prepare the grounds of appeal, the order and the assessment.
- Pay the fee, Rs 20,000 for a company or Rs 5,000 otherwise.
- Apply for a stay if recovery is close.
- Attend the first hearing and decide on dispute resolution.
Common questions about the Appellate Tribunal Inland Revenue
How many days do I have to appeal to the Appellate Tribunal Inland Revenue?
30 days from service of the Commissioner (Appeals) order, under section 131(2)(d) as amended up to 30 June 2026.
What is the fee?
Rs 20,000 for a company and Rs 5,000 for any other taxpayer, under section 131(3).
Do I have to pay the tax while the appeal is pending?
Yes, unless the Tribunal stays recovery. A stay is for 90 days and can end early if you miss the hearing schedule.
Can I file late?
The Tribunal may admit a late appeal if you were prevented by sufficient cause, on written application.
How long does the Tribunal take?
The law says 90 days from filing, extendable only through the condonation route the section describes.
What if the Tribunal order is wrong in law?
A reference to the High Court on a question of law may follow, within the time in section 133.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 21 October 2026. We read sections 130 to 133 of the Income Tax Ordinance, 2001 as consolidated up to 30 June 2026 on FBR's website on that date. The consolidated PDF carries old and new wording side by side, so we read the footnotes to separate them. We could not verify the Tribunal's current hearing rules or how many benches are working. We did not file an appeal. Confirm with a tax adviser before the deadline.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.