Break a Fixed Deposit Early in Pakistan: How HBL and Allied Bank Cut Your Profit
Break a term deposit early in Pakistan and the bank pays a lower rate. See HBL's four rate rule, Allied Bank's two rate rule and a Rs 1,000,000 worked example.
Short answer: You can break a fixed deposit early at most Pakistani banks, but the bank recalculates your profit at a lower rate. HBL pays the lowest of four rates, two of them cut by 1 point. Allied Bank pays the lower of two savings rates. Profit already paid above the new rate comes back out of the money you receive.
A family emergency, a property deal, a fee due next week. Those are the usual reasons people break a term deposit, and the bank's rule is often explained only at the counter. We read the early encashment terms on HBL's and Allied Bank's own product pages on 20 October 2026, along with the State Bank of Pakistan (SBP) rule that leaves term deposits outside the savings minimum. Here is what you lose, and one way to avoid breaking the deposit at all.
HBL pays the lowest of four rates if you break early
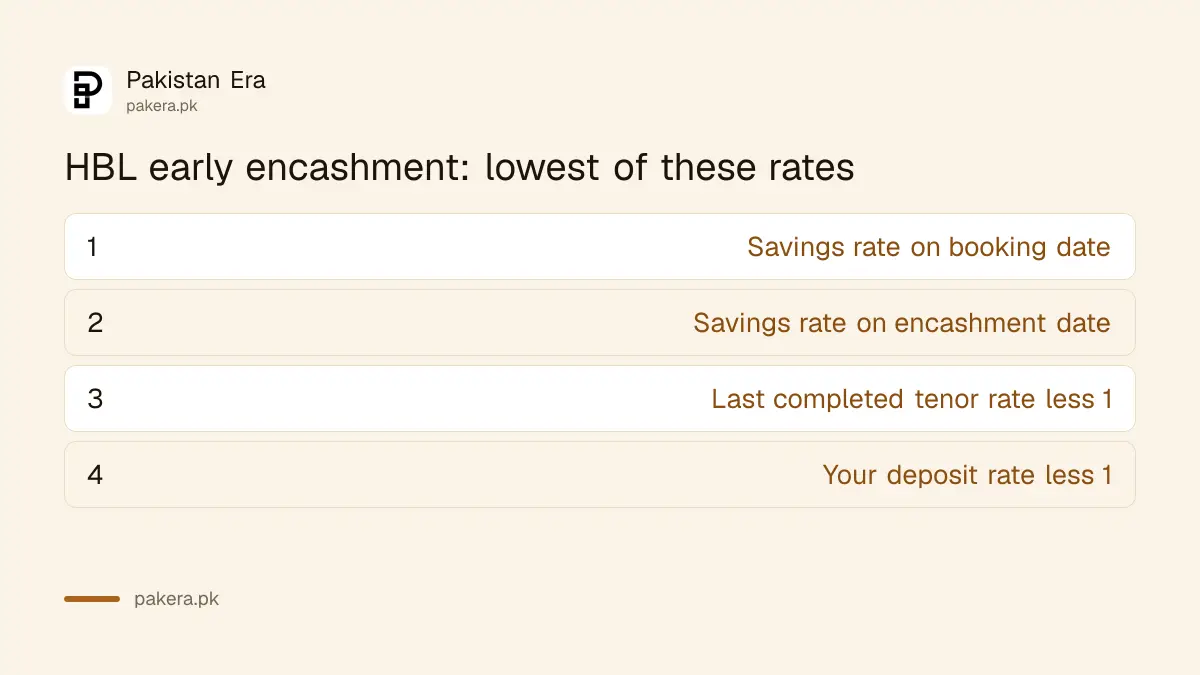
For HBL Advantage, Advantage Plus and Investment Plus deposits, early encashment profit is the lowest of four rates: the savings rate on your booking date, the savings rate on the day you break, the last completed tenor's rate minus 1 point, or your own deposit rate minus 1 point.
HBL's page calls the savings rate the PLS rate, short for profit and loss sharing. The "last completed tenor" is the longest term on HBL's rate sheet that is shorter than the time you actually held the deposit. So if you break a one year deposit after seven months, the last completed tenor is six months.
HBL adds three conditions. You must encash the whole deposit, because partial withdrawal is not allowed. Any adjustment, penalty or charge is recovered from the proceeds. And HBL may refuse early encashment if the deposit is held as collateral for a loan.
Allied Bank pays the lower of two savings rates
Allied Bank's Behtar Munafa Term Deposit page says that on early withdrawal, profit is the lower of the PLS savings rate when you booked or the PLS savings rate when you encash. Its Advance Profit Plus deposit, which pays profit upfront, allows early encashment subject to its terms.
So at Allied Bank you drop to a savings account rate for the whole period, rather than keeping a term rate. Allied's page does not set out how upfront profit is recovered on Advance Profit Plus, so ask for that figure in writing before you sign anything.
| Bank and product | Profit if broken early | Other conditions |
|---|---|---|
| HBL Advantage, Advantage Plus, Investment Plus | Lowest of 4 rates, two of them less 1 point | Whole deposit only, may refuse if used as collateral |
| Allied Bank Behtar Munafa | Lower of savings rate at booking or at encashment | Not stated on the page |
| Allied Bank Advance Profit Plus | Subject to terms and conditions | Profit paid upfront |
| Meezan Monthly Mudarabah Certificate | As per Meezan's approved schedule | Schedule is a separate document |
| National Savings certificates | Scheme by scheme deduction | See the National Savings rules |
Meezan's product page says early withdrawal follows an "approved schedule", but that schedule did not open for us on 20 October 2026, so we do not quote it. For National Savings, see the charges to encash National Savings certificates early.
A worked example shows what seven months can cost
Take an example, not a quote. You place Rs 1,000,000 for one year at 10.60% and break it after seven months. Suppose the savings rate is 10% on both dates and the six month rate on the sheet is 9.40%. Under HBL's rule you get the lowest of 10%, 10%, 8.40% and 9.60%, which is 8.40%.
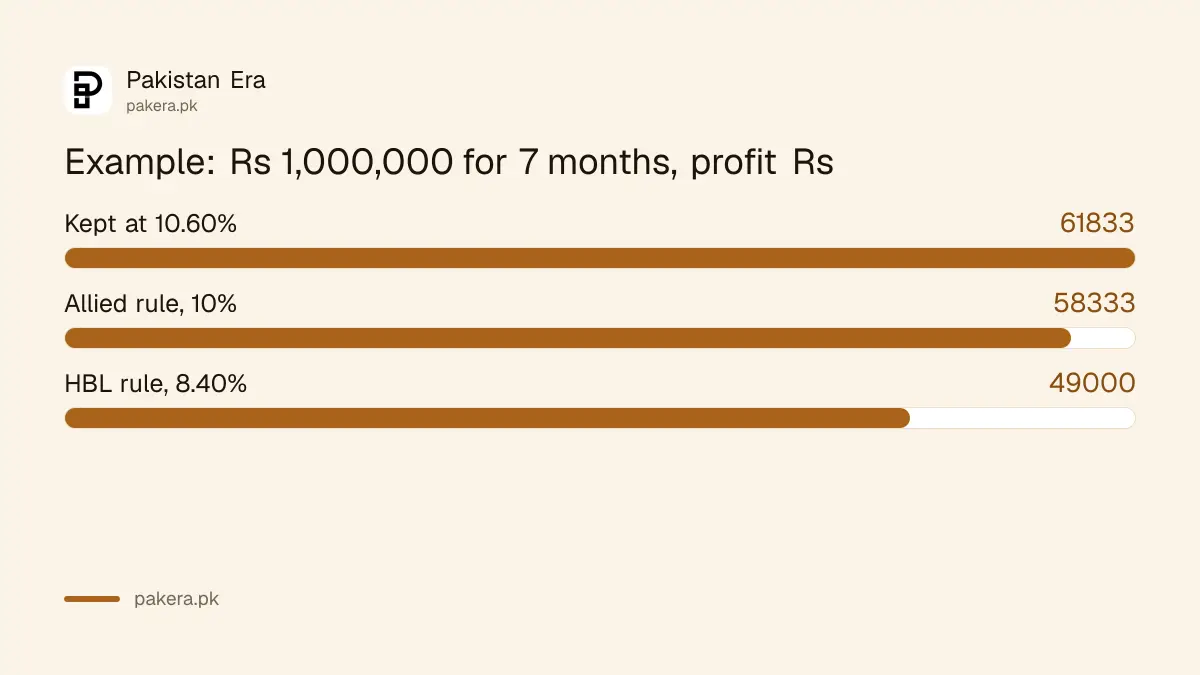
Seven months at 10.60% would have earned about Rs 61,833 before tax. At 8.40% it earns about Rs 49,000. The difference is about Rs 12,833. If you took monthly profit at 10.60% all along, HBL would take that Rs 12,833 back from the amount it pays out. Under Allied's rule with the same savings rates, you would get 10%, or about Rs 58,333.
Rates on real sheets change every month, so use your own bank's numbers. Current term rates are in our comparison of fixed deposit rates by bank.
Borrowing against the deposit can cost less than breaking it
HBL says you can take financing of up to 90% against an Advantage Plus deposit. If you need money for a few weeks, a loan secured on the deposit keeps your full term rate running. Whether that is cheaper depends on the loan rate, so compare the two figures before you choose.
A loan usually costs more than the deposit earns. But if the gap is small and the need is short, you can come out ahead. A deposit held as collateral cannot be broken at HBL until the loan is settled.
- Ask the branch for the early encashment profit in writing, in rupees, for your exact date.
- Ask what a loan against the deposit would cost for the weeks you need.
- Compare the rupee loss from breaking with the rupee cost of the loan.
- If you break it, check the payout against the bank's written figure.
- Keep the encashment advice slip for your tax records.
SBP's 10% savings minimum does not cover term deposits
The SBP minimum profit rule covers savings accounts with no fixed maturity, and term deposits have been excluded since 1 June 2014. So your bank sets both the term rate and the early encashment rule itself. That is why the terms differ so much from bank to bank.
The minimum for ordinary savings accounts is 0.5 points below SBP's floor, which is 10% now. That rule, and what SBP's 26 October 2026 meeting can do to it, is in our explainer on the bank savings minimum rate. Before you lock money away, keep enough in a savings account to cover a month or two of spending. Short term options such as the Easypaisa term deposit are another way to stay flexible.
Common questions
Can I withdraw part of my HBL term deposit?
No. HBL's terms allow encashment of the full deposit only. Partial withdrawal is not allowed.
Do I lose my principal if I break a fixed deposit?
Usually you lose part of the profit, not the principal. If profit was paid monthly at the higher rate, the bank takes the excess back from the payout, so the amount you get back can be smaller than your original deposit.
Can the bank refuse early encashment?
HBL says it may refuse if the deposit is held as collateral. Settle or release the loan first.
Is there a fixed penalty in rupees?
HBL and Allied Bank work through a lower profit rate rather than a fixed fee. HBL also says penalties, costs or charges can be recovered from the proceeds.
Does SBP set early withdrawal rules for fixed deposits?
Not on rates. SBP's savings minimum excludes term deposits, so each bank sets its own early encashment terms.
Is tax charged on the reduced profit?
Yes. Withholding tax is deducted from whatever profit the bank finally pays, after its recalculation.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 20 October 2026. We read the early encashment terms on HBL's Advantage Plus page, including the four rate rule, the full encashment condition and 90% financing, and on Allied Bank's Behtar Munafa page and its Advance Profit Plus page, all on 20 October 2026. Meezan's Monthly Mudarabah Certificate page was read the same day, but its premature encashment schedule did not load. The term deposit exclusion comes from SBP's BPRD Circular No. 5 of 2014. The worked example uses illustrative rates, not any bank's sheet, and the sums are our arithmetic before tax.
About the author
Public Services and Education Journalist
Fajr Riaz is a journalist and content writer at Pakistan Era, based in Lahore. She covers the questions people meet in everyday life in Pakistan: how a public service works, what a change in the rules means, and where to find a reliable answer.