How to Claim a Digital Fraud Refund From Your Bank or Wallet in Pakistan
Lost money to digital fraud? SBP rules give your bank 30 minutes to raise a dispute and 10 days to investigate. See who pays and how to report it right now.
Short answer: Report the fraud to your bank or wallet provider at once and keep the complaint number. Under State Bank of Pakistan (SBP) rules, your provider must raise your dispute on the interbank dispute system within 30 minutes, finish its investigation within 10 days, and return the money within 3 days once fraud is proven.
Most people lose a fraud case in the first hour, not in the investigation. They wait for a morning branch visit, or they argue with the caller, while the money moves on to the next account. The State Bank wrote the clocks into a circular so that your provider cannot wait either.
We read the circular and its two annexes on the SBP website on 11 October 2026. This guide explains the clocks, what you must do to start them, and who pays when a deadline is missed.
The dispute clock starts when you report the fraud
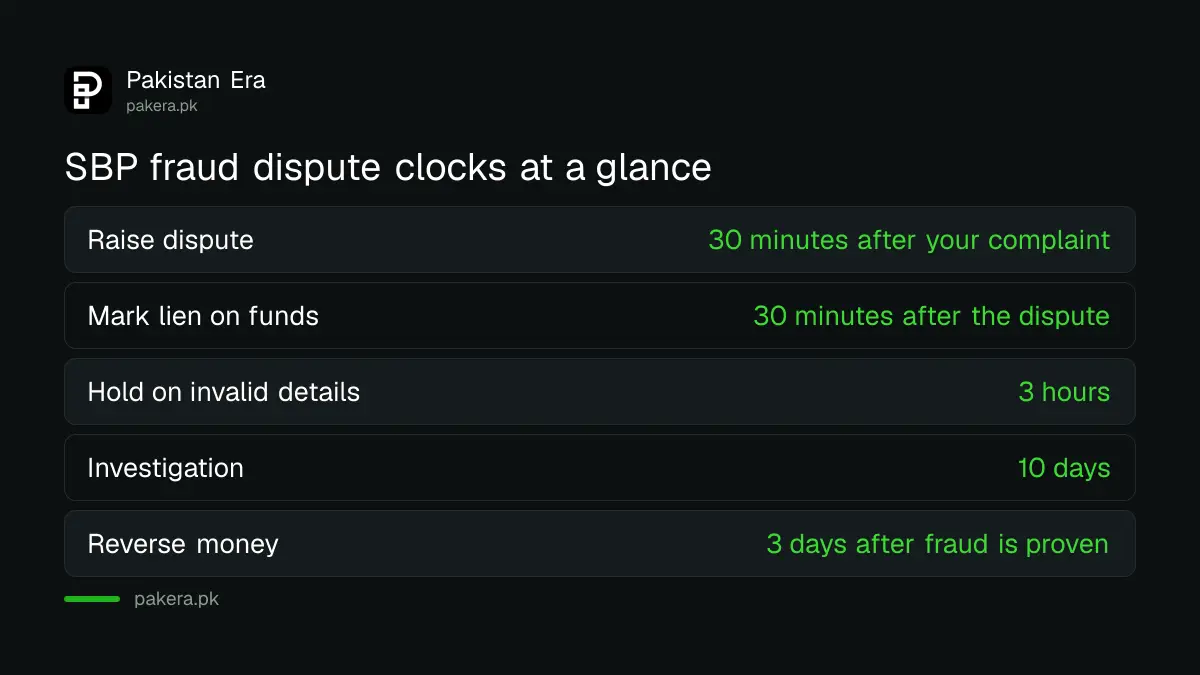
The SBP rules work from the moment you complain. Your bank must raise the dispute within 30 minutes, the receiving bank must freeze the disputed funds within 30 minutes of that, and both must finish investigating within 10 days. Proven fraud money goes back within 3 days.
The circular is BPRD Circular No. 04 of 2023. It covers retail customers of banks and microfinance banks, including branchless banking wallets. It does not cover corporate accounts. The dispute system it uses is called FTDH, short for Fraudulent Transaction Dispute Handling, and it connects the banks to each other.
| Step | Who acts | Time limit in the SBP rules |
|---|---|---|
| Raise your dispute on the interbank system | Your own bank or wallet provider | Not more than 30 minutes after your complaint |
| Mark a lien on the disputed money | The receiving bank | Not more than 30 minutes after it receives the dispute |
| Hold funds if dispute details are invalid | The receiving bank | 3 hours, while your bank corrects the details |
| Finish the investigation | Each bank in the chain | 10 days from receiving the dispute |
| Reverse the money to you | The banks, after fraud is established | 3 days |
A lien means the receiving bank marks the disputed amount as untouchable. The account holder can still use the rest of the balance. The bank must not put a full debit block on the account for this, according to the SBP FAQ.
Report in a way that starts the clock
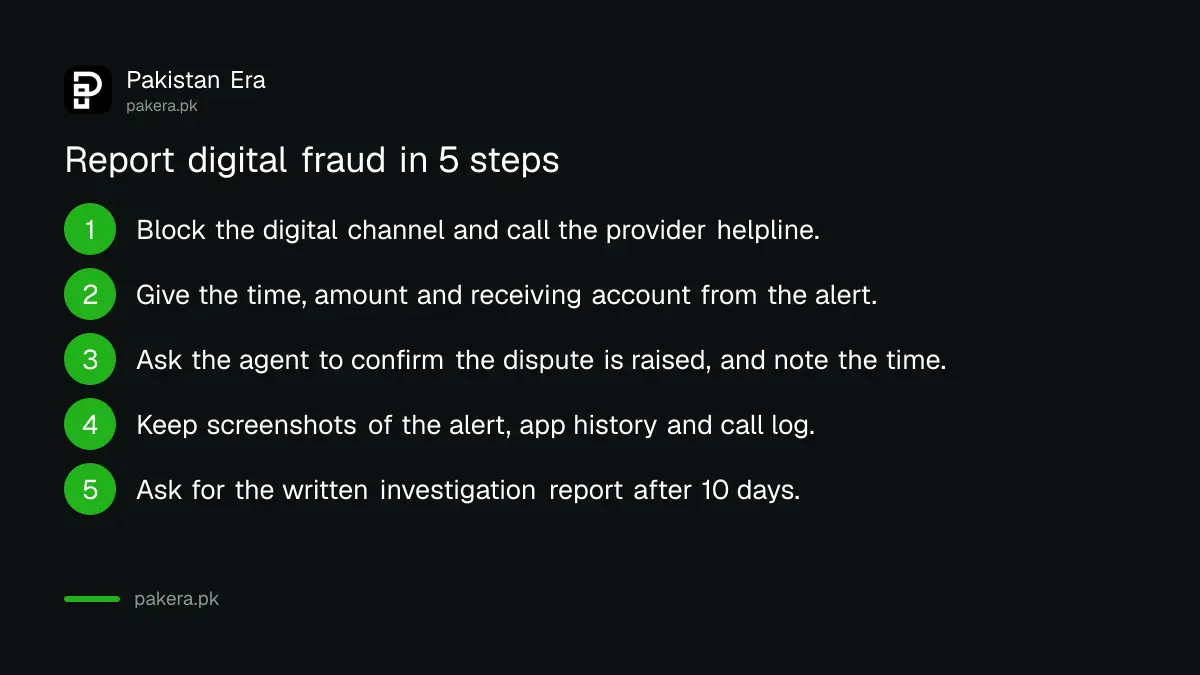
Call your provider's helpline, name the transaction, and ask for a complaint number and the time of your report. The clock runs from your complaint, so the time matters. Follow up in writing the same day by app, email or the complaint form.
- Block the digital channel first if you can. The SBP rules ask providers to answer a block request on the phone within one minute and to offer a self-service phone menu for blocking.
- Give the date, time, amount and the receiving account or number shown in the alert.
- Ask the agent to confirm that the dispute is raised on the interbank system, and note the name and time.
- Keep screenshots of the alert, the app history and the call log.
- Ask for the investigation report in writing after 10 days.
Helpline numbers differ by bank, so use the number printed on your card or app, or look up bank helpline numbers in Pakistan. Inside your own app, the first minutes matter most when you report fraud on your bank's mobile app.
Your own bank pays when it misses a deadline
The circular sets a liability framework. If your bank does not lodge the dispute in time, or gives you no way to lodge one, it carries the whole loss. A receiving bank that lets money leave before it marks a lien carries the loss for that amount.
| What went wrong | Who carries the loss under the SBP framework |
|---|---|
| Dispute not lodged within the time limit | The sending bank, in full |
| You could not lodge a complaint because no channel worked | The sending bank, in full |
| Funds withdrawn before a lien was marked in time | The receiving bank, in full |
| Several receiving banks missed the lien deadline | Those banks, in proportion |
| Bank cannot show the transaction came from your registered device | Your bank compensates you |
| Transaction alert reached you late because of a bank delay | Your bank, in full |
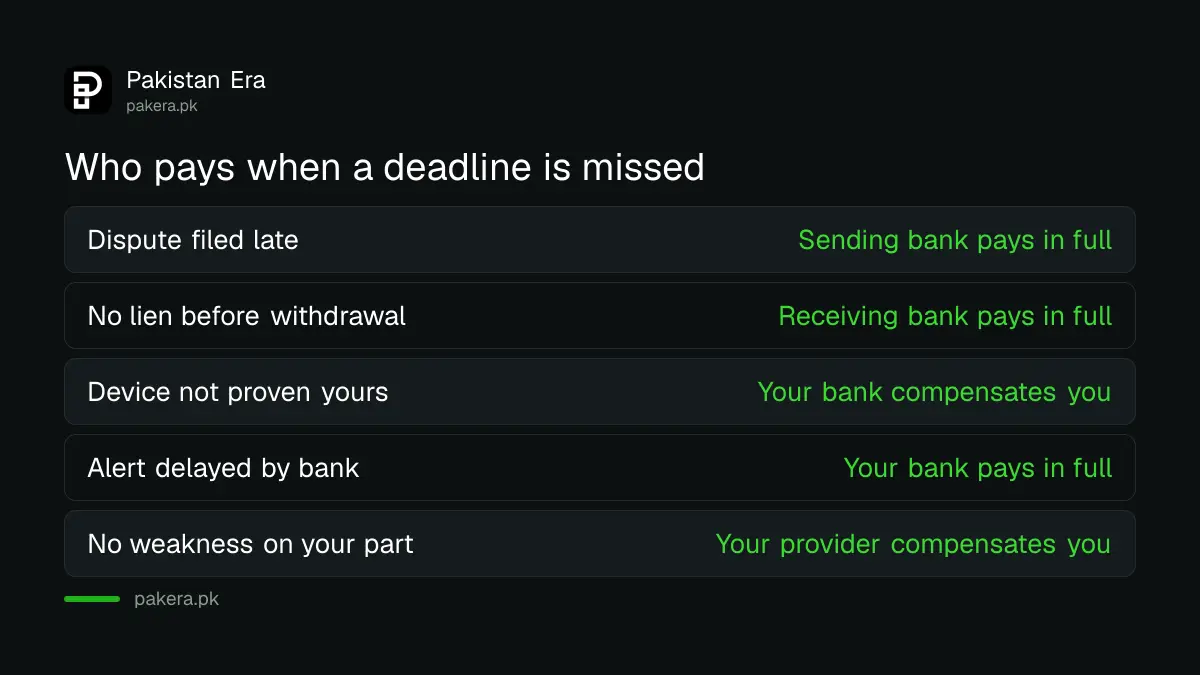
The SBP FAQ adds a plain rule. If you did not share any credential or device and did not perform the transaction, you are not liable, and your provider must compensate you. Providing safe digital services is the provider's job.
The same rules reach wallet frauds in a special way
For branchless banking wallets, a credit that arrives by transfer can stay in an "in-progress" state for 2 hours before it can be cashed out or spent. If a dispute comes from that hold, the circular puts the liability on the beneficiary bank.
That hold is the reason a fast report matters so much for a wallet transfer, and it is the reason received wallet money shows in progress for 2 hours.
Your part: never give a code or PIN
The SBP rules also tell banks that their staff must not ask you to say an OTP aloud. If a caller asks for your OTP, PIN or app password, the call is a fraud attempt. A customer who shares credentials weakens a claim, because the "no weakness on your part" test then fails.
If you already shared a code, still report at once. The bank has to investigate end to end, including its own systems, its agents and its staff. The State Bank states that scope in the circular, and you are entitled to hear the findings.
Escalate when the clocks pass
If the 10 days pass without an answer, write to your bank's complaint unit and quote the circular. Then use the SBP complaint portal. After that, the Banking Mohtasib hears bank complaints for free. Keep every reference number.
The general complaint deadlines, such as the bank's 30 day fraud reply rule, run separately. A wrong transfer is a different case, and you can get a wrong JazzCash or Easypaisa transfer back by another route. Complaints to the State Bank go through the SBP Sunwai complaint portal.
Common questions
How fast must my bank raise a fraud dispute in Pakistan?
Within 30 minutes of receiving your complaint. The SBP circular requires the bank to log the dispute on the interbank dispute system in that time.
How long does a bank have to return money lost to digital fraud?
Investigation must finish within 10 days of the dispute, and funds must be reversed to the victim within 3 days after fraud is established.
Does this cover JazzCash and Easypaisa wallets?
The circular covers branchless banking wallets run by banks and microfinance banks, and the SBP FAQ says the controls apply to them. It does not state the position for e-money institution wallets, so ask your provider in writing.
Can my bank refuse a refund if I shared my OTP?
It can argue that you carry some weakness. The SBP FAQ clears customers only where there was no weakness on their side, so never share a code with anyone.
Does the rule apply to Raast transfers?
Yes. The annex tells banks to use the same dispute system for all fraudulent transactions, including those made through Raast.
What if my bank ignores the clocks?
Complain in writing, then use the SBP complaint portal and the Banking Mohtasib. Quote BPRD Circular No. 04 of 2023 and your complaint number.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on Sunday 11 October 2026. We read the SBP page for BPRD Circular No. 04 of 2023 and its Annexure A (measures and liability framework) and Annexure B (FAQs). We did not test any provider's app or helpline, so we cannot say how fast each one responds in practice. The circular may be amended, so check the SBP page before you rely on a clock.
About the author
Technology Journalist & Multimedia Producer
Ahmad Ali is a technology journalist and multimedia producer at Pakistan Era, joining the team in October 2026. He covers consumer technology and digital life for Pakistani readers, combining research with hands-on product testing.