How to Report Fraud on Your Bank's Mobile App in Pakistan
Fraud on your bank's own app, not a wallet. Freeze the app first, then report it, and how the free Banking Mohtasib ombudsman route works if the bank stalls.
The first thing to do when you spot a transaction you never made in your bank's own mobile app is open that same app and freeze the card or account, before you call anyone. A fraud session can still be live, and every minute spent dialling a helpline is a minute the app itself could have shut the door.
This is about your bank's own app, HBL, Meezan, UBL and the rest, not a wallet like JazzCash or Easypaisa. We read the State Bank's own complaint channels at source on 5 October 2026 to lay out what actually works, in order.
Freeze the app before you do anything else
Almost every bank app now has a card freeze or temporary block option sitting inside its settings menu. Use it immediately. It does not cancel the card permanently, and it costs you nothing to reverse once things are safe.
While you are in there, check for any session you did not start and log it out. A fraudster who is still inside your account can keep acting while you are busy making phone calls.
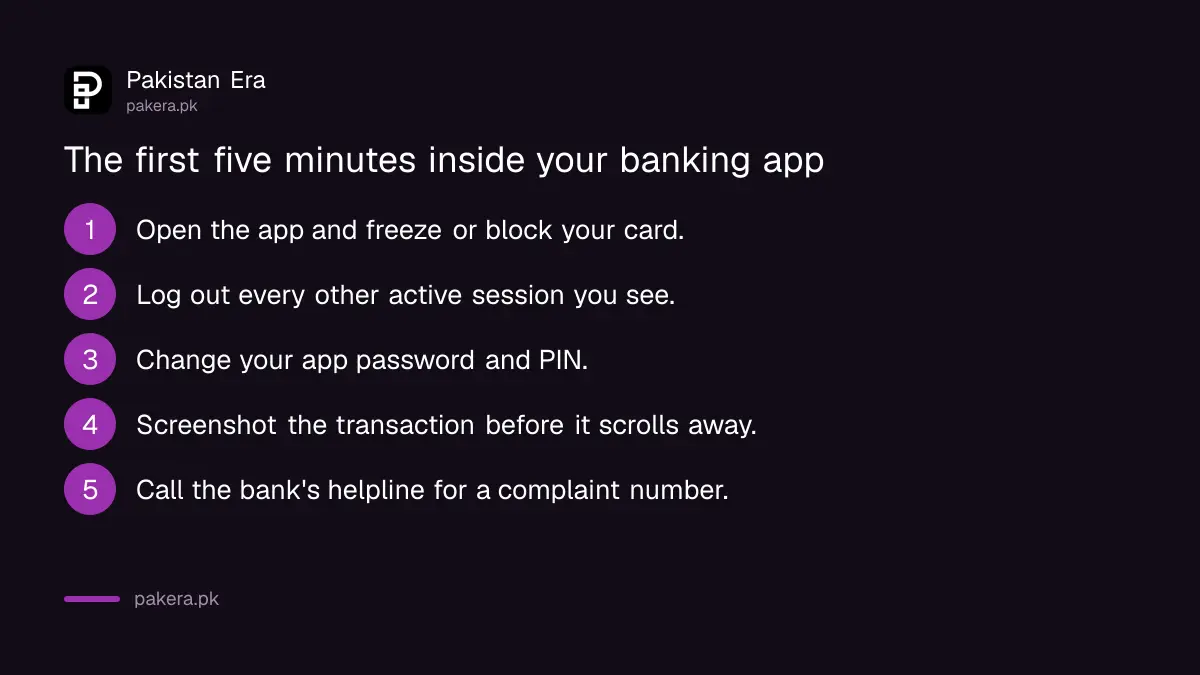
- Open the app and freeze or block the card tied to the fraud.
- Log out any active session you do not recognise.
- Change your app password and transaction PIN right away.
- Screenshot the fraudulent transaction before anything refreshes it away.
- Call the bank's helpline and get a complaint reference number.
Report it through three channels, not just one
Your bank is always the first stop, and it has to be in writing, not just a phone call that leaves no trail. But if the bank is slow, unresponsive or unconvincing, you are not stuck waiting.
Your bank's complaint desk
Every bank must run a dedicated complaint unit reachable through the app, a helpline or email, and must give you a reference number the same day you report it.
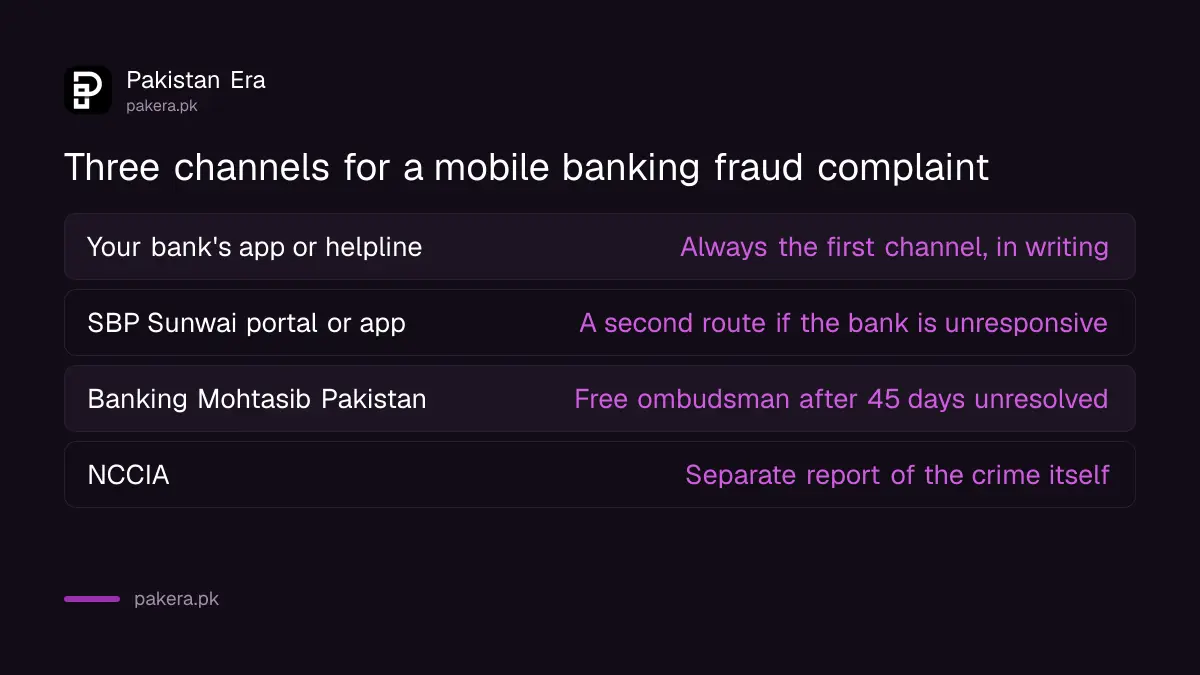
The SBP Sunwai portal and app
State Bank runs its own complaint channel, Sunwai, as a portal and a mobile app, separate from your own bank's app. It exists so a complaint against any bank has one place to be lodged and tracked if the bank itself is not moving.
The Banking Mohtasib
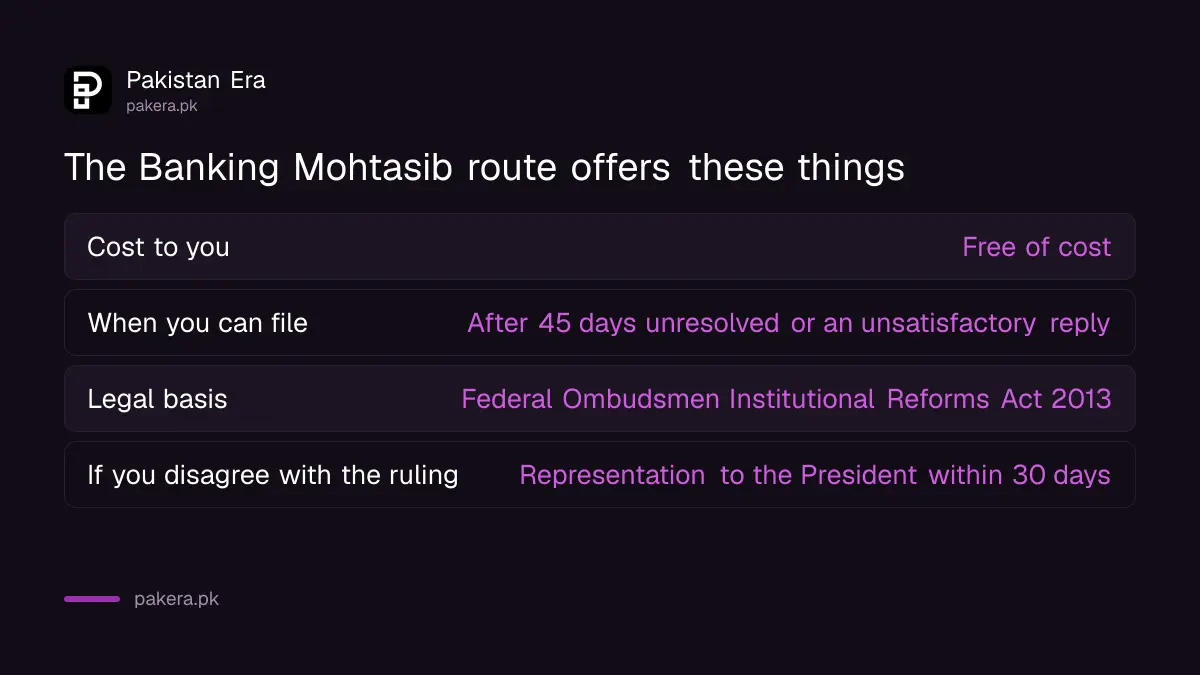
If 45 days pass with no reply, or the reply does not satisfy you, the Banking Mohtasib is the next step, and it costs nothing.
A SIM you do not control is often the real weak point
A banking app rarely gets broken into directly. More often, someone takes over the phone number behind it, through a fraudulent SIM swap, and simply receives the one time codes the app already trusts.
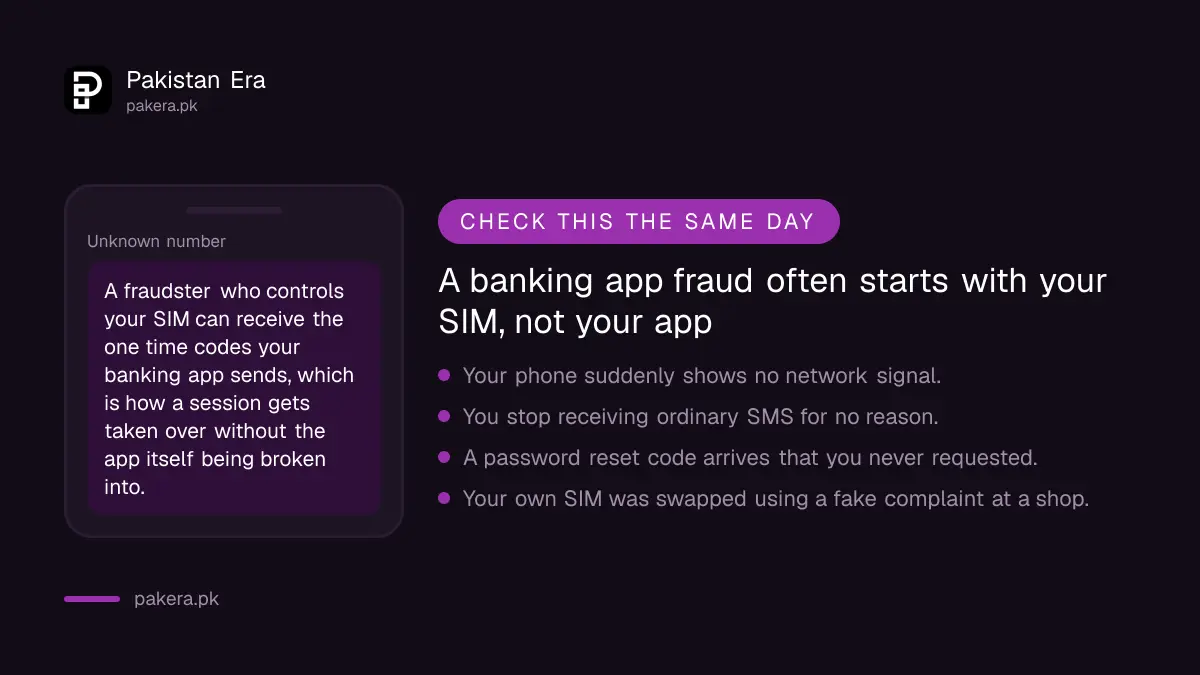
- Your phone suddenly loses signal with no obvious cause.
- Ordinary SMS stop arriving, even from people you know.
- A password reset code shows up that you never asked for.
- Your own number has been reissued on a new SIM you did not request.
Checking which SIMs are registered on your CNIC the same day is worth doing alongside the bank complaint, not after it, because the two problems often share one root cause.
The Banking Mohtasib is free and binding if you do not reply
The office works under the Banking Companies Ordinance 1962 and the Federal Ombudsmen Institutional Reforms Act 2013. It exists specifically so a bank customer is not left with no recourse once their own bank has had its chance.
| Detail | What applies |
|---|---|
| Cost to you | Free of cost |
| Earliest you can file | After 45 days with no reply, or an unsatisfactory one |
| Who runs it | An independent statutory ombudsman, a four year term |
| If a decision goes against the bank | Binding unless the bank appeals within 30 days |
Microfinance bank customers follow a slightly different path. The Mohtasib does not cover microfinance banks, so a complaint against one goes to State Bank directly as the second forum instead.
What your bank actually owes you for the fraud itself
Reporting the fraud through the right channel is only half the job. Whether the bank has to refund the stolen amount, and how fast, is governed by a separate, more specific rule on unauthorised transfers.
We cover that refund formula, and exactly when it applies, in our guide to getting a refund after online banking fraud. The general complaint clock your bank already works to, including the 48 hour acknowledgement and 30 day fraud deadline, sits in our bank fraud complaint deadlines guide, and the actual phone numbers to call are in our bank helpline numbers list.
Reporting the crime itself to law enforcement is a separate, parallel step, covered in how to report a cybercrime in Pakistan, and it does not replace the bank complaint or wait for it to finish.
Frequently asked questions
Should I freeze my card before calling the bank?
Yes. Freezing the card or account inside the app takes seconds and can stop an active session, while a phone call can take minutes just to get through.
What is the SBP Sunwai portal for?
It is State Bank's own complaint channel, separate from any individual bank's app, used to lodge and track a banking complaint if your bank is not responding.
Is the Banking Mohtasib the same as my bank's complaint desk?
No. It is an independent, free ombudsman you can approach only after your bank has had 45 days to reply, or has replied unsatisfactorily.
Can a SIM swap really affect my banking app?
Yes. If someone controls your phone number, they can receive the one time codes your banking app sends, which lets them act as if they were you.
Does the Banking Mohtasib cover every bank account?
It covers banks and development finance institutions. Microfinance bank accounts go to State Bank directly instead, as the second forum.
Do I still need to report the fraud to NCCIA?
Yes, separately. The bank complaint is about getting your money back; reporting to NCCIA puts the crime itself on record with law enforcement.
About the author
Technology Journalist & Multimedia Producer
Ahmad Ali is a technology journalist and multimedia producer at Pakistan Era, joining the team in October 2026. He covers consumer technology and digital life for Pakistani readers, combining research with hands-on product testing.