How to Close a Business With FBR in Pakistan: Section 117 Notice and Sales Tax Deregistration
Closing a business in Pakistan takes a section 117 notice to FBR within 15 days, a part year return and sales tax deregistration on Form STR-3. See each step.
To close a business with FBR you do three things: give the Commissioner written notice within 15 days of stopping, under section 117 of the Income Tax Ordinance; file a return for the part-year up to the closing date; and, if you are sales tax registered, apply online for de-registration on Form STR-3 and file a final return. The sales tax order must come within 60 days of the application or of clearing your dues, whichever is later, and your monthly return duty is suspended while the application is pending.
Walking away without these steps leaves the registration alive, and the penalties for missed returns keep running on a business that no longer exists. We read section 117, section 21 and section 28 of the Sales Tax Act, 1990 and rule 11 of the Sales Tax Rules, 2006 on the FBR website on 19 October 2026.
Section 117 wants a written notice within 15 days and a part-year return
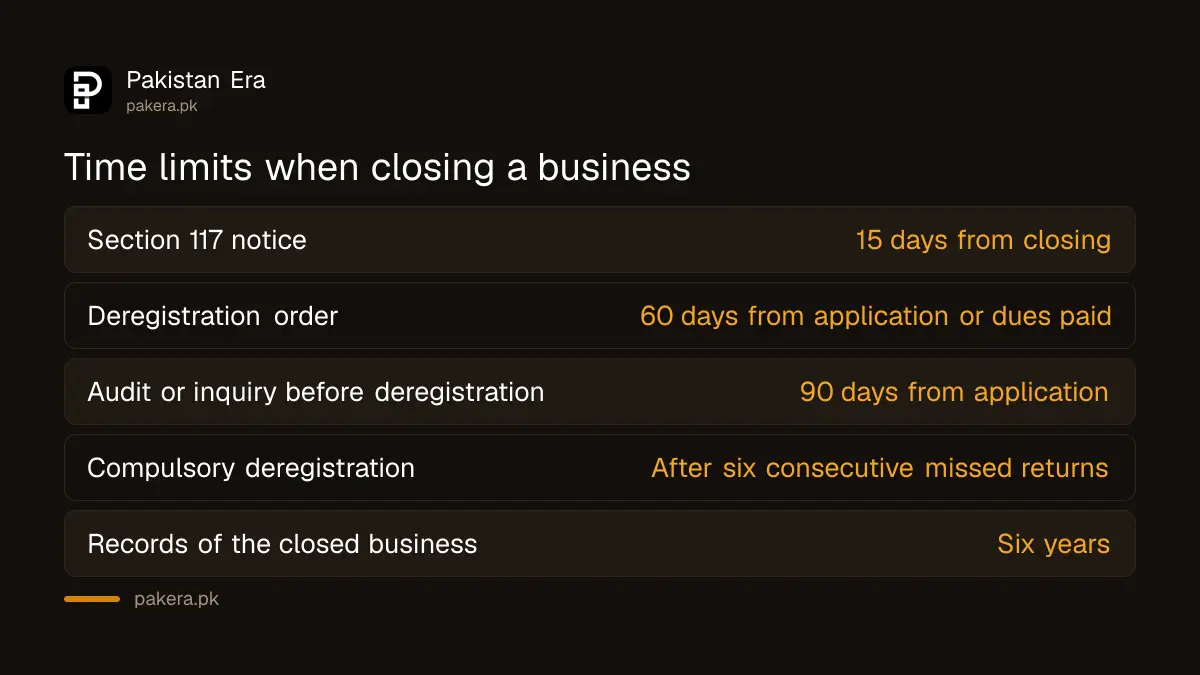
Sub-section (1) of section 117 says any person discontinuing a business "shall give the Commissioner a notice in writing to that effect within fifteen days of the discontinuance". Sub-section (2) then requires a return of income for the period from the first day of the tax year to the date of discontinuance, and that period is treated as a separate tax year.
If you give no notice, sub-section (3) lets the Commissioner serve one on you when he has reasonable grounds to believe the business has stopped or is about to, demanding a return for the period he names. A return under this section counts as a full return of income, including for the deemed assessment under section 120.
| Step | Law | Time limit | Who acts |
|---|---|---|---|
| Notice of discontinued business | Section 117(1), Income Tax Ordinance | 15 days from closing | You, in writing to the Commissioner |
| Return for the part year | Section 117(2) | As required, or on the Commissioner's notice | You, on IRIS |
| Sales tax de-registration application | Rule 11(1), Sales Tax Rules | Online, Form STR-3 | You, on the computerised system |
| Final sales tax return | Section 28, Sales Tax Act | Before de-registration, as directed | You |
| De-registration order | Rule 11(1) | Within 60 days of application or of paying dues | Commissioner |
| Cancellation of income tax registration | Rule 82(5), Income Tax Rules | After all liabilities are discharged | Commissioner, by order |
Sales tax de-registration is applied for online on Form STR-3
Rule 11(1) says every registered person who ceases to carry on business, or whose supplies become exempt, and who intends to be de-registered "shall apply online on the computerized system" in Form STR-3. That online route replaced the old application to the Commissioner through S.R.O. 608(I)/2025 of 17 April 2025, which also cut the decision period from 90 to 60 days.
STR-3 asks for the NTN, the category of registered person, the registered address and the principal activity, then the reason: ceased to carry on business, supplies became exempt, taxable turnover in the last 12 months fell below the threshold, transfer or sale of the business, merger, or other. Transfer, sale and merger need proof attached. A stocks declaration on Form STR-4 goes with it, because tax on stock in hand at closing has to be settled.
The Commissioner may order de-registration from a date he specifies, "but not later than sixty days from the date of such application or the date all the dues outstanding against such person are deposited by him, whichever is later". So unpaid arrears hold the clock.
While the application is pending, returns stop but so does your input tax
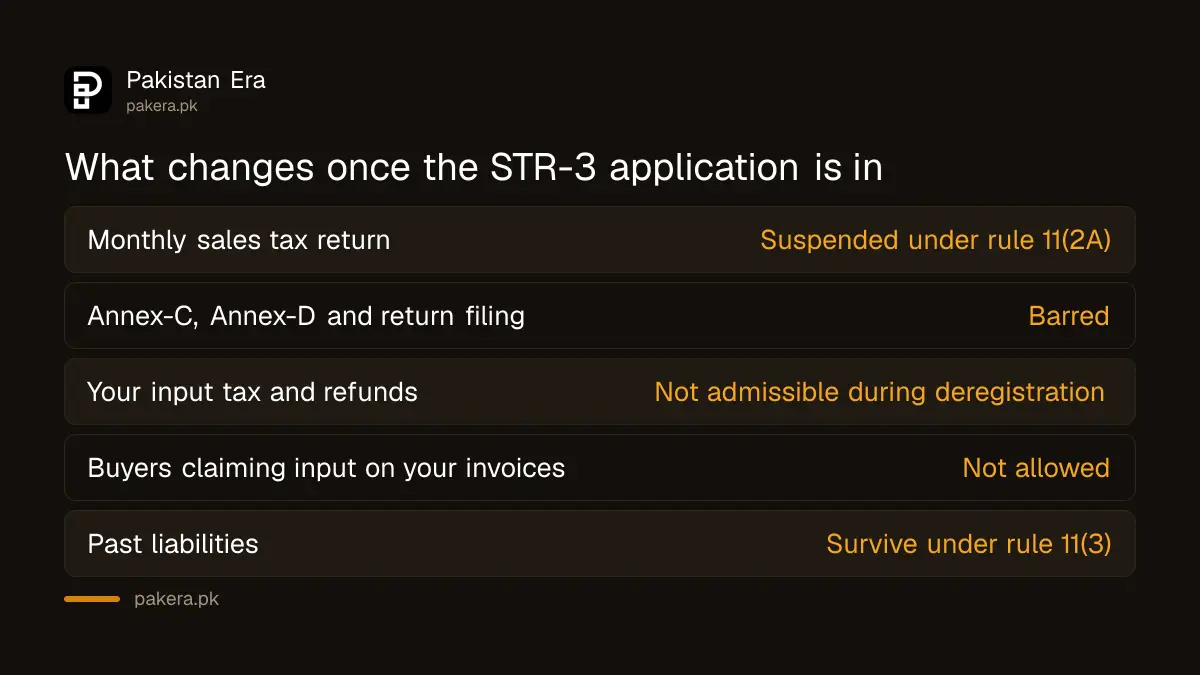
Rule 11(2A) suspends the obligation to file the monthly sales tax return under section 26 from the day the application is received until you are de-registered or the application is rejected. That is the relief. The proviso to rule 11(1) is the cost: after online submission you are barred from filing Annex-C, Annex-D and the return, no input tax adjustment or refund is admissible to you during the process, and nobody else can claim input tax on invoices you issue in that period.
If the Commissioner wants an audit or inquiry first, rule 11(2) says he asks for records in writing, must complete the inquiry within 90 days of the application, and directs you to pay any liability found by filing the final return under section 28. Once that return is filed and paid, the system de-registers you automatically on the expiry of 90 days.
Past liabilities survive, and silence gets you de-registered the hard way
Rule 11(3) says the obligations and liabilities for the period you traded as a registered person "shall not be affected" by cancellation of the registration. De-registration closes the future, not the past, and the six-year record rule still applies to the closed business, as set out in our guide on keeping sales tax records for six years.
There is also a compulsory route. Where a registered person fails to file returns for six consecutive months, the Commissioner, after a written notice and a hearing, orders de-registration. That order comes with the arrears, penalties and default surcharge for the missed months, which are set out in our guide to the late sales tax return penalty. Applying first is cheaper than being removed later. Suspension and blacklisting under section 21(2) are a different process, used for fake invoices and tax fraud, not for closures.
Your NTN stays unless the Commissioner cancels it
There is no closing form for an NTN. Rule 82(5) of the Income Tax Rules lets the Commissioner cancel a taxpayer's registration by written order, after all outstanding liabilities are discharged and after a hearing. Rule 82(1) lets you file a form of modification when your particulars change, which is how a sole proprietor records that the business activity has ended while the individual NTN continues.
An individual who closes a shop still has an NTN as a person and still files a return if any of the section 114 conditions apply. A company or AOP that closes needs the registration cancelled and, for a company, SECP's own winding-up steps. The CNIC-based NTN itself does not disappear, and the Form 181 changes on IRIS are where the business address and bank account are removed.
The closing checklist in order
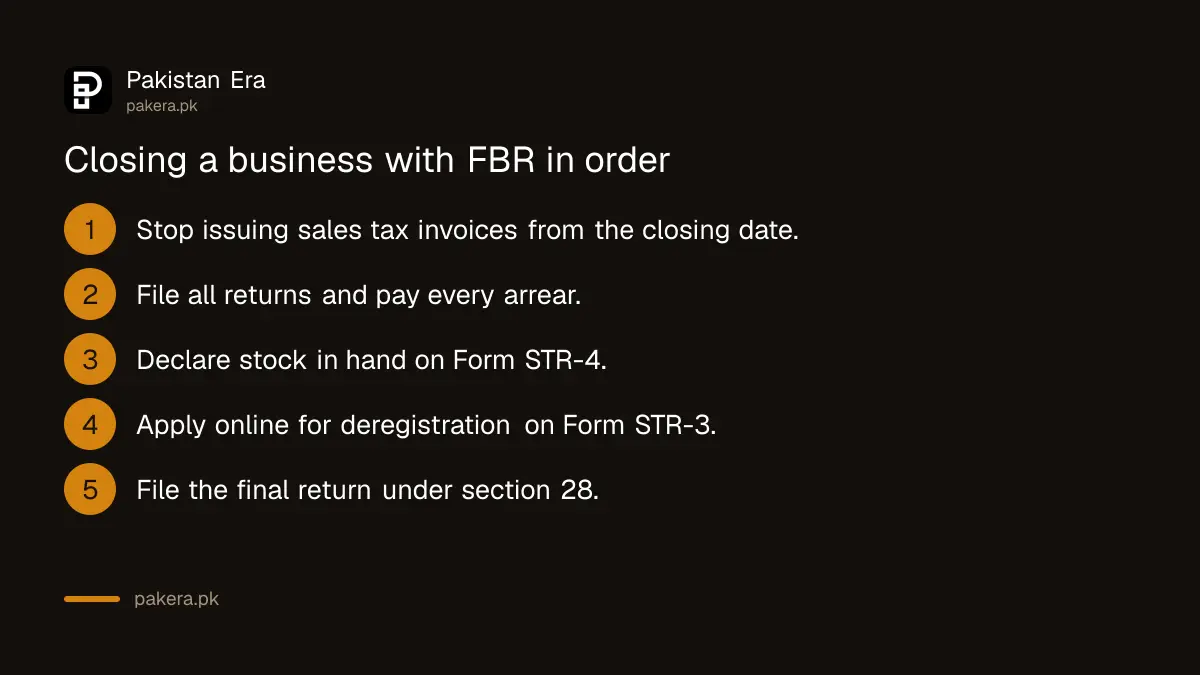
Do the sales tax steps before the income tax notice if you are registered for both, because the final sales tax return feeds the closing accounts.
- Pick the closing date and stop issuing sales tax invoices from that day.
- File all monthly returns up to the closing month and pay every arrear, because the 60-day clock runs from the later of application or payment.
- Prepare the stock in hand and settle the tax on it with Form STR-4.
- Apply online on the computerised system in Form STR-3 with the reason and proof.
- Answer any records request within the Commissioner's 90-day inquiry window and file the final return under section 28.
- Give the Commissioner Inland Revenue the section 117 notice in writing within 15 days of closing.
- File the part-year income tax return on IRIS and, once all liabilities are clear, ask for cancellation of registration under rule 82(5).
Provincial services tax is separate: a Punjab, Sindh or KP services registration has its own de-registration with PRA, SRB or KPRA, and FBR's order does not close it.
Common questions
How many days do I have to tell FBR I closed my business?
Fifteen days from the discontinuance, in writing to the Commissioner, under section 117(1) of the Income Tax Ordinance.
How long does sales tax de-registration take?
The Commissioner must order it within 60 days of the application or of your paying all outstanding dues, whichever is later. An audit or inquiry has 90 days.
Do I keep filing monthly sales tax returns after applying?
No. Rule 11(2A) suspends the monthly return obligation from receipt of the application until you are de-registered or refused.
Can I claim input tax while the application is pending?
No. The proviso to rule 11(1) bars input tax adjustment and refunds during de-registration, and bars others from claiming input tax on your invoices.
What if I just stop filing?
After six consecutive missed months the Commissioner can de-register you after a notice and hearing, and the penalties for those months remain due.
Does closing the business cancel my NTN?
Not by itself. The Commissioner cancels registration by order under rule 82(5) after liabilities are cleared. An individual keeps a personal NTN.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 19 October 2026. We read section 117 in FBR's consolidated Income Tax Ordinance, 2001 amended up to 30 June 2026, sections 21 and 28 of the Sales Tax Act, 1990 amended up to 30 June 2026, rules 11 and 12 and Form STR-3 in the Sales Tax Rules, 2006 updated to 31 July 2026, and rule 82 of the Income Tax Rules, 2002 amended up to 15 September 2026, all on the FBR website. We could not verify how the de-registration application appears on the IRIS screen or how long orders take in practice, because we did not file one.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.