FBR Makes Rule 38B Final (SRO 2098): IRIS Will Flag Tax Return Errors First, 7 Days to Reply
FBR's SRO 2098 of 10 November 2026 makes rule 38B final: IRIS flags tax return errors before any penalty, with at least 7 days to reply and a 7 day reminder.
یہ صفحہ اردو میں پڑھیں
FBR has made rule 38B final. Under S.R.O. 2098(I)/2026, dated 10 November 2026, FBR's automated system can flag mistakes in your income tax return and warn you on IRIS before any legal or penal action starts. The warning must give you at least seven days to reply, and a reminder with at least seven more days follows if you stay silent.
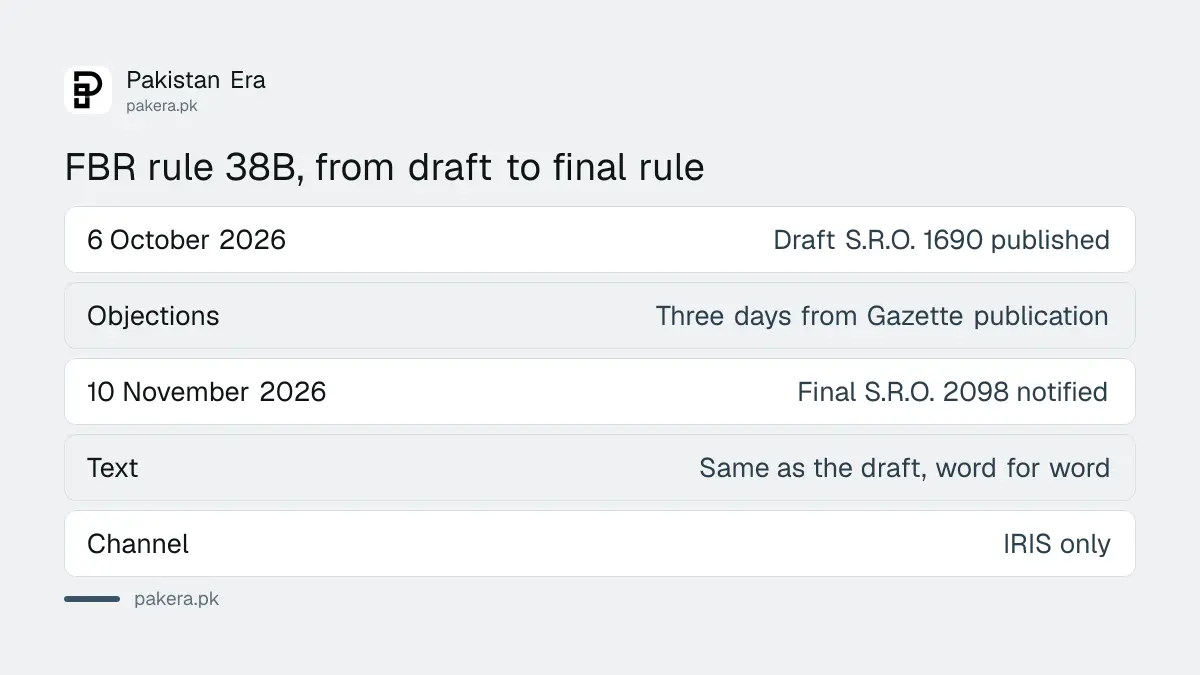
The text is word for word the draft that FBR put out on 6 October 2026. We read both notifications on FBR's own SRO page on 12 November 2026 and compared them line by line. Nothing in the nine sub-rules changed.
So the rule is now part of the Income Tax Rules, 2002. Below is what it says, what it leaves open, and what a filer should do this week.
S.R.O. 2098 makes rule 38B part of the Income Tax Rules
FBR notified S.R.O. 2098(I)/2026 on 10 November 2026 under section 120(2A) read with section 237(1) of the Income Tax Ordinance, 2001. It inserts a new rule 38B after rule 38A, for electronic scrutiny of returns and advance intimation of issues found by the system.
The notification says the rule "having been previously published" as S.R.O. 1690(I)/2026 of 6 October 2026. That is the legal step section 237(3) requires: a draft first, objections, then the final rule. FBR's Income Tax SRO list shows it under the title "Notification of Final Amendment to the Income Tax Rules, 2002, for Insertion of Rule 38B".
The rule's title is "Procedure for electronic scrutiny and intimation of issues detected by the automated system". The file number printed at the foot is F. No. 1(53)S(ITP)/2026.
The final rule matches the October draft word for word
We placed the two texts side by side. Sub-rules (1) to (9) are identical, including both seven day minimums and the role of the local officer. Anyone who read our report on the draft already knows the content.
That matters for one reason. Objections were invited within three days of the draft's Gazette publication. If any came in, they did not change a word. The table shows what each sub-rule now says, in plain terms.
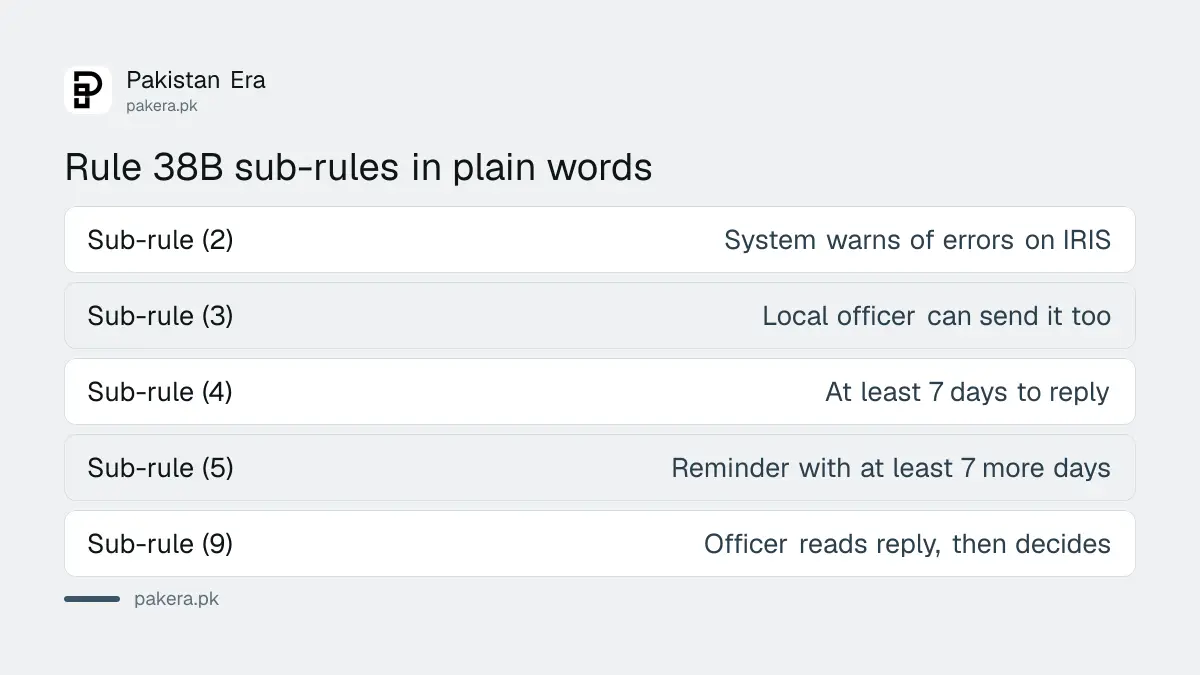
| Sub-rule | What it says |
|---|---|
| (1) | An automated system, including CRM, processes returns under section 120(2A) |
| (2) | The system may send an online advice or advance intimation on IRIS about factual or legal mistakes or discrepancies |
| (3) | The Officer of Inland Revenue with jurisdiction can also send the same system-generated intimation |
| (4) | The intimation states a reply period of not less than seven days |
| (5) | No reply in time means a reminder, again of not less than seven days |
| (6) and (7) | The issue, the intimation and your reply go to the officer and onto a system dashboard |
| (8) | The procedure runs through a Change Request Form inside the system |
| (9) | The officer reads your reply, or notes there was none, and acts under the Ordinance if needed |
You get at least 7 days to reply, then a reminder with 7 more
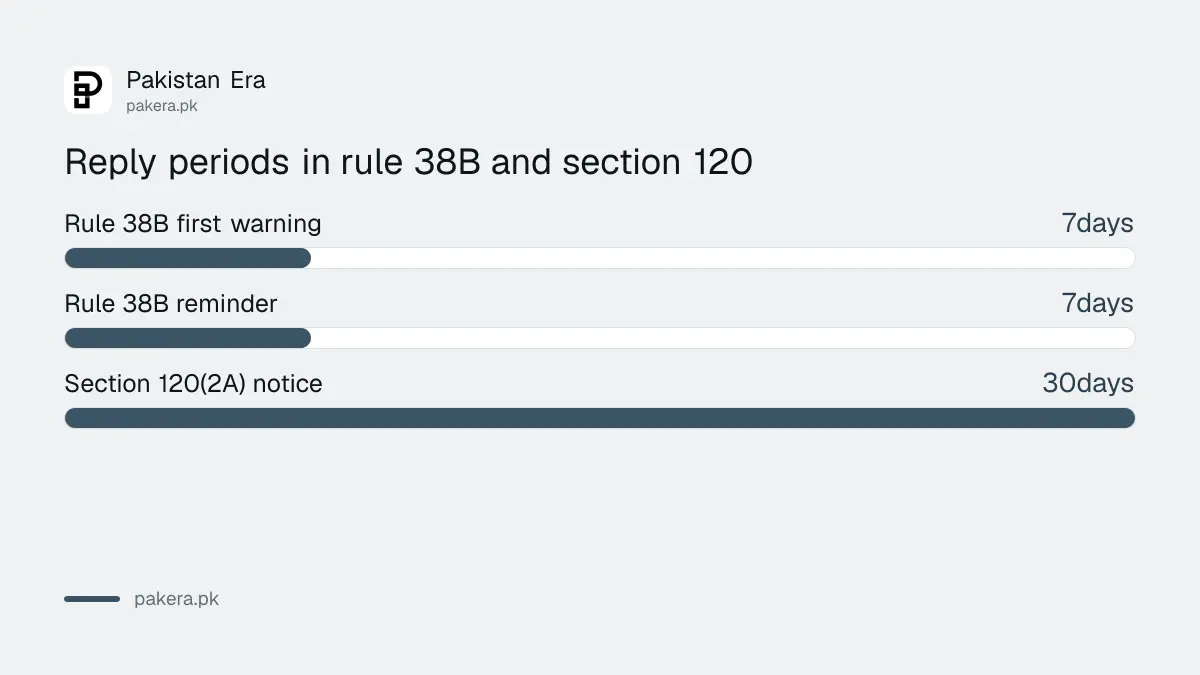
The intimation must name its own reply period, and the period cannot be shorter than seven days. If you do not answer, the system sends a reminder with at least another seven days. So the shortest path is about 14 days from the first warning.
Both figures are minimums. The notice on your screen is what counts, and it may give longer. Read the date on the intimation itself rather than counting from the day you happen to log in.
The warning is meant to come first. Sub-rule (2) says it lets you clarify, correct the error or take other corrective action "before any legal or penal action is initiated". In plain words, a flag is a chance to fix things, not a penalty.
The 30 day rule in section 120(2A) still sits alongside it
Section 120(2A) of the Ordinance, which we read in FBR's consolidated copy amended up to 30 June 2026, already sets its own safeguard. No adjustment can be made unless a system-generated notice names the intended adjustments. If no reply arrives within thirty days of that notice, the adjustments are made.
The same section says that if no adjustment is made within six months of filing, the return is taken as declared. It also says the sub-section applies from a date FBR notifies in the official Gazette.
Rule 38B does not explain how its seven days fit with the thirty days in the law. Our reading is that the rule covers an earlier, informal warning, while the thirty day notice is the formal step before an adjustment. That is our reading, not FBR's. We also did not find the Gazette date that switches section 120(2A) on, so treat that link as open.
What a filer should do now that the rule is final
Make sure an IRIS warning can reach you, and answer it quickly. The rule names IRIS as the channel. It does not mention post, SMS or email, so an unread inbox is the main risk.
- Log in to IRIS and open the inbox once a week. If you cannot log in, follow the steps to reset your IRIS password or PIN first.
- Check that your mobile number and email in the IRIS profile are current.
- Confirm your tax year 2026 return shows as completed, using the steps to check an income tax return was filed on IRIS.
- Match your return with the tax already deducted against your CNIC, such as bank, salary and phone deductions. Gaps are what an automated check catches.
- If you spot your own mistake, revise the return under section 114(6) before anyone asks.
- When an intimation arrives, note its reply date, gather the papers for each point, and reply on IRIS before that date.
A real FBR notice sits in your IRIS inbox. A message that only arrives by email or WhatsApp, with a link and a payment demand, is a warning sign. Our guide on how to tell a real FBR notice from a fake one covers the checks.
Rule 38B is separate from faceless audits and assessments
Rule 38B is about the first, automatic check of a return. Audits and assessments now run through FBR's faceless system, which has its own rules and notices.
The final faceless assessment rules came on 5 November 2026, explained in our report on S.R.O. 2062 and faceless income tax assessment. A 38B warning may come before any of that, or it may be the end of the matter if your reply settles the point.
FBR's other final rule of 10 November, Form ATL-U for late filers, is covered in our report on S.R.O. 2097.
Common questions
Is rule 38B in force now?
FBR notified the final rule as S.R.O. 2098(I)/2026 on 10 November 2026. The notification does not print a separate start date. The automated adjustment power in section 120(2A) applies from a date FBR notifies in the Gazette, which we did not find.
Did anything change from the draft?
No. We compared the final text with draft S.R.O. 1690(I)/2026 of 6 October 2026, and all nine sub-rules are the same.
How long do I have to reply to an IRIS intimation?
At least seven days, as stated on the intimation. If you do not reply, a reminder follows with at least seven more days.
Will a flagged return mean a penalty?
Not by itself. The rule says the intimation comes before any legal or penal action. The officer with jurisdiction reads your reply and decides whether action is needed under the Ordinance.
Who can send me a rule 38B intimation?
The automated system, or the Officer of Inland Revenue who has jurisdiction over you, under sub-rule (3).
Will I get the intimation by post?
The rule names IRIS only. It does not mention post, SMS or email, so keep checking your IRIS inbox.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 12 November 2026. We read S.R.O. 2098(I)/2026 from FBR's Income Tax SRO list, where it is dated 10 November 2026, and compared it with the draft S.R.O. 1690(I)/2026. We read section 120 of the Income Tax Ordinance, 2001 in FBR's consolidated copy, amended up to 30 June 2026. We could not open IRIS, so we have not seen a live 38B intimation, and we did not find the Gazette date for section 120(2A). Nothing here is tax advice. Our earlier report on the rule 38B draft has the background.
About the author
Tax, Bills and Technology Writer
Ali Akhtar is a young and curious voice here at Pakistan Era. He is currently pursuing his A-Levels and has a growing interest in Pakistan’s changing industrial landscape and educational trends. Ali likes to write in a way that helps him explain and explore the world around him. His writing reflects the perspective of the new generation navigating the evolving trends of Pakistan where technology, youth innovation, and shifting opportunities are reshaping the country’s future.