Is a Gift of Money or Property Taxable in Pakistan? Rules for Relatives and Bank Transfers
A gift from a relative is outside Pakistan's gift tax rule, but a gift from anyone else is taxable income. See who counts as a relative and how to prove a gift.
A gift of money or property from a relative is outside the gift tax rule in Pakistan's Income Tax Ordinance. A gift from anyone else is taxable income in your hands. The safest way to receive any gift is a bank transfer, because section 39(3) treats some gifts that do not come through a bank as income.
A father pays for a son's shop, an uncle sends Rs 2 million before a wedding, a friend returns a favour with a plot. Each is a gift, and each can reach an FBR notice if you cannot show how it arrived. We read section 39 and section 85 of the Ordinance, and the rule on gifts of property, on FBR's own PDF on 15 October 2026.
A gift from a relative is outside the gift tax rule
Section 39(1)(Ia) taxes any amount or property received without payment, or as a gift, "other than gift received from relative". So a gift from a relative is excluded from that clause. The exclusion depends on the giver being a relative as the Ordinance defines the word.
The rule was added by the Finance Act, 2019 and the relative test was widened by the Finance Act, 2021. The word is defined in section 85(5), which the next section sets out. Everything else on this page depends on who is and is not a relative.
The Ordinance defines a relative more widely than "close family"
Section 85(5) says a relative of an individual is an ancestor, a descendant of any of the grandparents, or an adopted child, of the individual or of the individual's spouse. It also includes the spouse of the individual or of any such person.
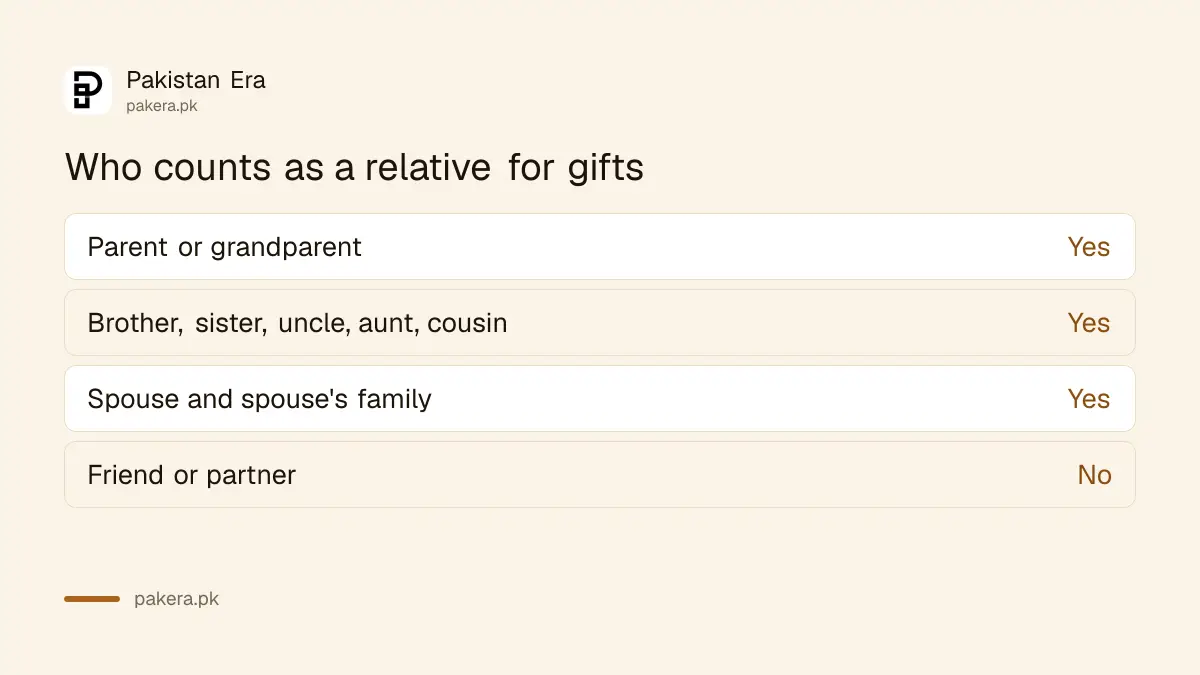
Reading the words plainly, that covers parents, grandparents, children, brothers, sisters, uncles, aunts and cousins, and the same relations on your spouse's side. That is our reading, not an FBR list. A family friend, a business partner or a neighbour is not a relative.
| Giver | Relative under section 85(5)? |
|---|---|
| Parent or grandparent | Yes, an ancestor |
| Brother, sister, uncle, aunt, cousin | Yes, a descendant of a grandparent (our reading) |
| Spouse and your spouse's close family | Yes |
| Friend, employer, business partner | No |
A gift from anyone else is taxable income
If the giver is not a relative, the amount or the market value of the property is income under the head "Income from Other Sources". That means it is added to your income for the year and taxed at the normal rates that apply to you.
Market value means the price the property would ordinarily fetch in an open sale. A plot given by a friend is taxed on what it would sell for, not on what the friend paid. The Ordinance also says an asset acquired in this way takes that value as its cost.
Check your own position first. The filer status SMS check takes one minute, and the steps to file an income tax return show where other income goes.
A cash gift has its own rule in section 39(3)
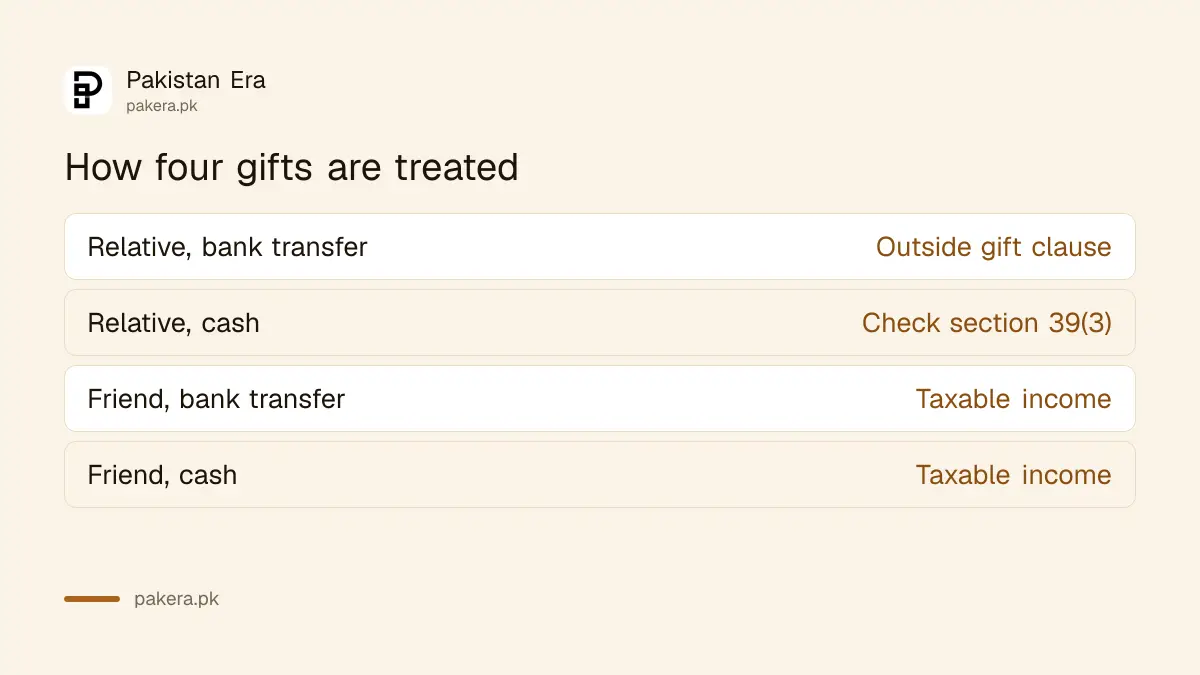
Section 39(3) is separate from the relative rule. It says any loan, advance, deposit for shares or gift received from a person who is not a bank, other than by a crossed cheque, a banking channel or digital means from a person holding a National Tax Number, is income.
Later amendments removed some words from the printed text of the section, shown as a gap, so read the exact text before you rely on it. What is clear is that the section does not carve out relatives. A large cash gift handed over in a bag has no trail, and that is the situation the section is aimed at.
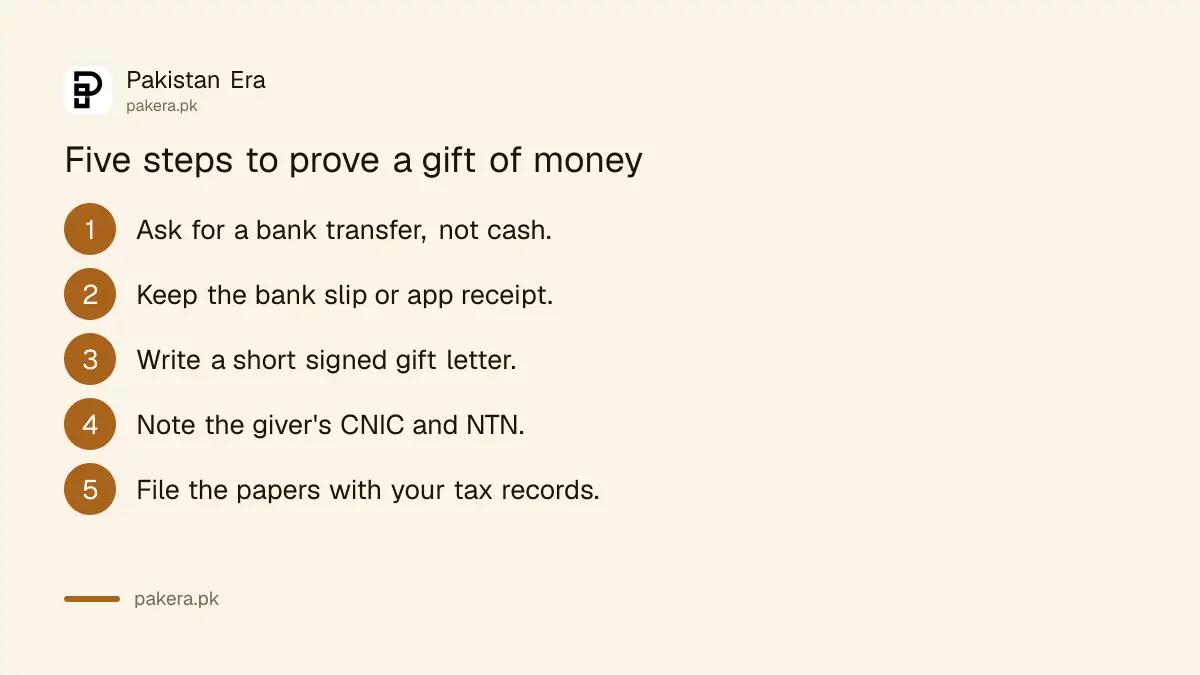
- Ask the giver to send the money by bank transfer, not in cash.
- Keep the bank slip or the app receipt showing the date, amount and both names.
- Write a short gift letter that names the giver, the amount and the relationship.
- Ask the giver for a copy of their CNIC and NTN, if they have one.
- Keep these papers with your tax records, so you can produce them if FBR asks.
A gift of property to a relative has no gain for the giver, but check the transfer taxes
Section 79(1)(c) says no gain or loss arises when someone gives an asset to a relative. The giver does not pay capital gains tax on the gift. A gift to a non-relative is different: section 78 treats the giver as if they had sold at market value.
Registering the gift is a provincial matter, as the steps to register a hiba gift of property in Punjab show. We did not find an exemption for a gift deed in sections 236C or 236K, which cover advance tax when property is sold or bought. Ask the registrar what they will collect before you sign.
Common questions about gift tax in Pakistan
Is there a gift tax in Pakistan?
There is no separate gift tax. A gift from a non-relative is taxed as income under section 39, and a gift from a relative is outside that clause.
Do I pay tax if my brother sends me money?
A brother is a relative under section 85(5), so the gift is outside section 39(1)(Ia). Send it by bank transfer so section 39(3) cannot be raised.
Is a gift from a friend taxable?
Yes. A friend is not a relative, so the amount counts as income from other sources and is taxed at your normal rates.
Can I accept a cash gift from my father?
The relative rule covers him, but section 39(3) also looks at how the money arrives. A bank transfer is safer than cash.
Does the giver pay tax on a gift of property?
Not on a gift to a relative: section 79(1)(c) says no gain or loss arises. A gift to a non-relative is treated as a sale at market value.
Do I need a gift letter?
The Ordinance does not name one. A short signed letter is still the cheapest proof if FBR asks how the money reached you.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 15 October 2026. The text of sections 39, 78, 79 and 85 comes from the Income Tax Ordinance, 2001 on FBR's site, in the version dated 24 July 2026. The Ordinance prints some words of section 39(3) as removed by amendments, so the exact wording needs a lawyer's check for large sums. We did not consult FBR on any case. This page explains the law and is not tax advice.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.