Which Car Can I Afford on My Salary in Pakistan? Rs 100,000 to Rs 300,000 Worked Out
Which car can you afford on your salary in Pakistan? The SBP 40% rule, 30% down and Rs 3m cap worked out for Rs 100,000 to Rs 300,000, with cars that fit.
On a net salary of Rs 150,000, a bank in Pakistan will let you pay up to Rs 60,000 a month on a car loan. Over 5 years that is enough for a Suzuki Alto or Every. On Rs 100,000 no new car on the makers' lists fits, and on Rs 300,000 you hit the Rs 3 million loan cap first.
Those limits come from the State Bank of Pakistan's consumer loan rules, not from any one bank. We worked out the numbers below on 6 October 2026, using today's KIBOR and Bank Alfalah's published spread.
The car you can afford on each salary
A bank caps your car instalment at 40% of your net monthly income, minus any loans you already pay. With 30% down, that gives the maximum car price below. Only cars up to 1000cc can be financed over 5 years.
| Net salary (Rs) | Max instalment (Rs) | Max car price, 3 years (Rs) | Max car price, 5 years, up to 1000cc (Rs) | New cars that fit |
|---|---|---|---|---|
| 100,000 | 40,000 | 1,609,945 | 2,290,344 | None on the makers' lists |
| 150,000 | 60,000 | 2,414,917 | 3,435,516 | Suzuki Every, Alto (all 3 variants) on 5 years |
| 200,000 | 80,000 | 3,219,890 | 4,285,714 (cap) | Every, Alto VXR and VXR AGS on 3 years; any Cultus on 5 years |
| 300,000 | 120,000 | 4,285,714 (cap) | 4,285,714 (cap) | Any car, if you pay everything above Rs 3m in cash |
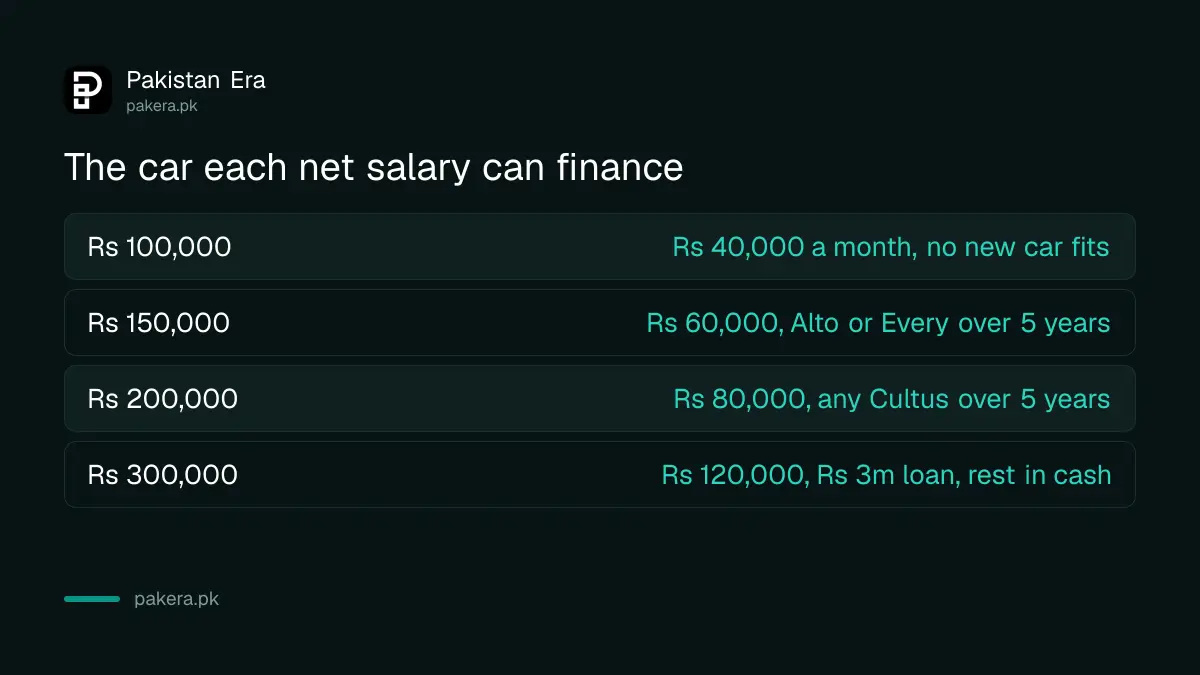
These figures assume you have no other loans or card instalments. If you already pay Rs 15,000 a month on a personal loan, take that off your maximum instalment first. At Rs 200,000, the Cultus VXL and VXL AGS need more than 30% down, because the loan stops at Rs 3 million.
SBP caps your total loan payments at 40% of net income
The 40% rule is in the State Bank's Prudential Regulations for Consumer Financing, Regulation R-3.
- 40% debt burden. All your monthly loan payments together cannot be more than 40% of your net disposable income. This came in with BPRD Circular Letter 29 of 23 September 2021, which cut it from 50%.
- 30% minimum down payment. Also from the 2021 circular.
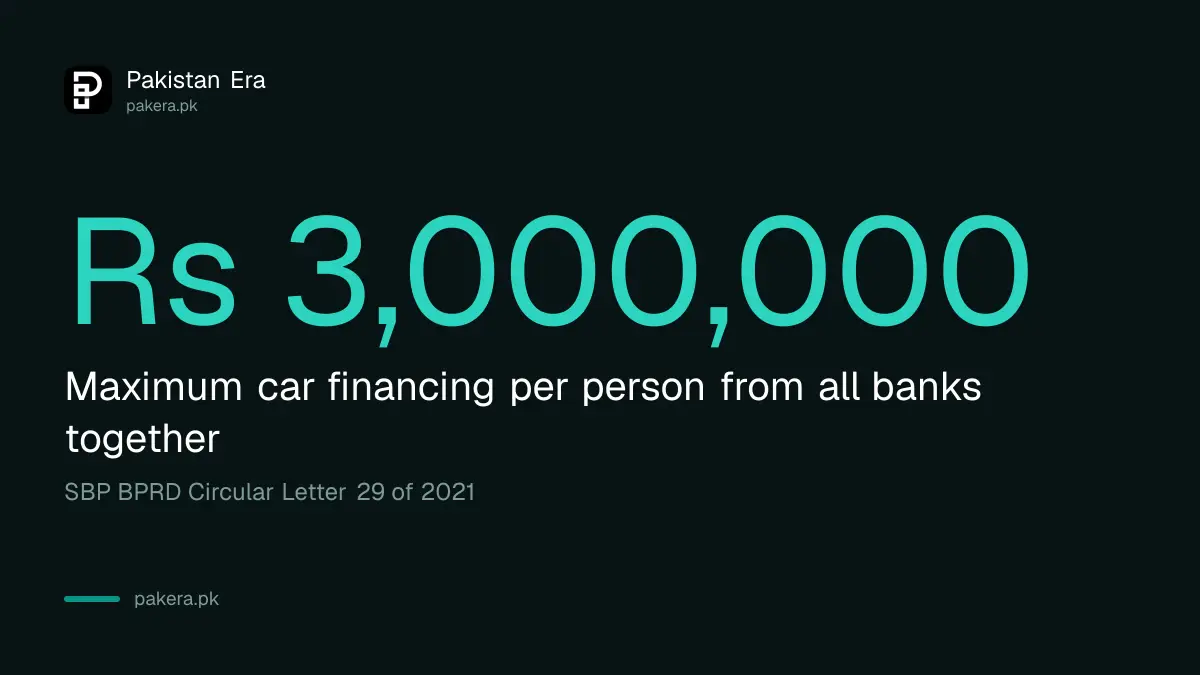
- Rs 3 million cap. One person's car loans from all banks together cannot be more than Rs 3,000,000 at any time.
- Tenure. BPRD Circular Letter 19 of 2022 set the maximum at 5 years for cars up to 1000cc and 3 years above 1000cc.
The 1000cc question: some bank pages still show older terms
In 2021, cars up to 1000cc were left out of the tighter rules. The 2022 circular brought them in: its paragraph 3 says the 2021 changes now apply to all locally made vehicles, including those up to 1000cc and electric cars. We found no later SBP circular that reverses this.
Two bank pages still show the older terms. Bank AL Habib's Islamic Apni Car page lists a 15% down payment for new cars up to 1000cc. Meezan Bank allows a debt burden of up to 50% for cars up to 1000cc. Both match the pre-2022 exemption. They may be old text or Roshan Apni Car terms.
Our working uses 30% down and 40% for every car. If a bank offers you looser terms, ask for them in writing on the offer letter before you count on them.
How we worked out the numbers
We used one verified bank rate so the figures are consistent. Bank Alfalah's Auto Loan page lists 1-year KIBOR plus 4% for 3 years and plus 4.5% for 4 to 5 years. With 1-year KIBOR at 12.68% on the State Bank's home page (as on 5 October), that is 16.68% for 3 years and 17.18% for 5 years.
Our calculation for a Rs 150,000 salary:
- 40% of Rs 150,000 is Rs 60,000, the most you can pay each month.
- At 17.18% a year over 60 months, Rs 60,000 a month repays a loan of Rs 2,404,861. This uses the standard instalment formula, worked backwards.
- That loan is 70% of the car's price, because you pay 30% down. Rs 2,404,861 divided by 0.7 is Rs 3,435,516.
- The Suzuki Alto VXL AGS costs Rs 3,326,446 on Suzuki's list, so it fits. The Cultus VXR at Rs 4,089,490 does not.
- Over 3 years at 16.68%, the same Rs 60,000 repays only Rs 1,690,442, so the most you can buy is a Rs 2,414,917 car.
Meezan Bank's fixed Car Ijarah rate of 13.42% for 5 years would let the same salary borrow Rs 2,612,256. If you want to compare the two types, Islamic and conventional car financing are set side by side with the same numbers.
Minimum net salary for popular new cars
We used the cheapest variant at today's list price, 30% down or more, and the longest tenure allowed.
| Car (price, Rs) | Loan (Rs) | Down payment (Rs) | Monthly (Rs) | Minimum net salary (Rs) |
|---|---|---|---|---|
| Suzuki Every VXR (2,965,200) | 2,075,640 | 889,560 | 51,786 (5 yrs) | 129,465 |
| Suzuki Alto VXR (2,994,861) | 2,096,403 | 898,458 | 52,304 (5 yrs) | 130,760 |
| Suzuki Cultus VXR (4,089,490) | 2,862,643 | 1,226,847 | 71,421 (5 yrs) | 178,554 |
| Suzuki Swift GL (4,460,160) | 3,000,000 | 1,460,160 | 106,481 (3 yrs) | 266,203 |
| Toyota Yaris 1.3 GLi MT (4,649,000) | 3,000,000 | 1,649,000 | 106,481 (3 yrs) | 266,203 |
| Honda City 1.2 LS (4,737,000) | 3,000,000 | 1,737,000 | 106,481 (3 yrs) | 266,203 |
| Toyota Corolla 1.6 MT (6,099,000) | 3,000,000 | 3,099,000 | 106,481 (3 yrs) | 266,203 |
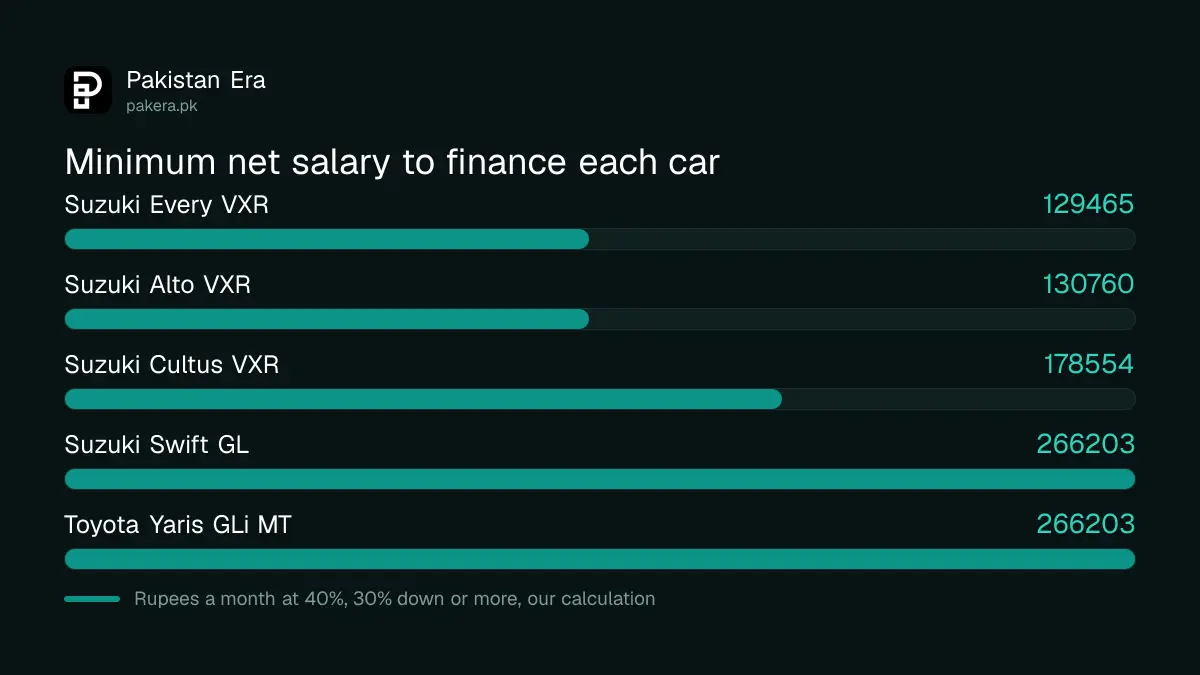
Every car above 1000cc is limited to 3 years, and the Rs 3 million cap applies to anything over Rs 4,285,714. So a Swift, Yaris, City and Corolla all need the same Rs 266,203 salary, and only the cash down payment changes. Prices are from the makers' own lists, given model by model in car prices in Pakistan for October 2026. Honda's were last read on 30 September.
Insurance comes on top. Banks charge it yearly on the car's value, from 1.4% at HBL to 1.99% at Meezan. On an Alto VXR at 1.99%, that is Rs 59,598 for the first year, about Rs 4,966 a month. Meezan also wants your net income to be at least twice the monthly rental including takaful.
How to apply for a car loan on your salary
The checks that fail most applicants are the debt burden and the credit report.
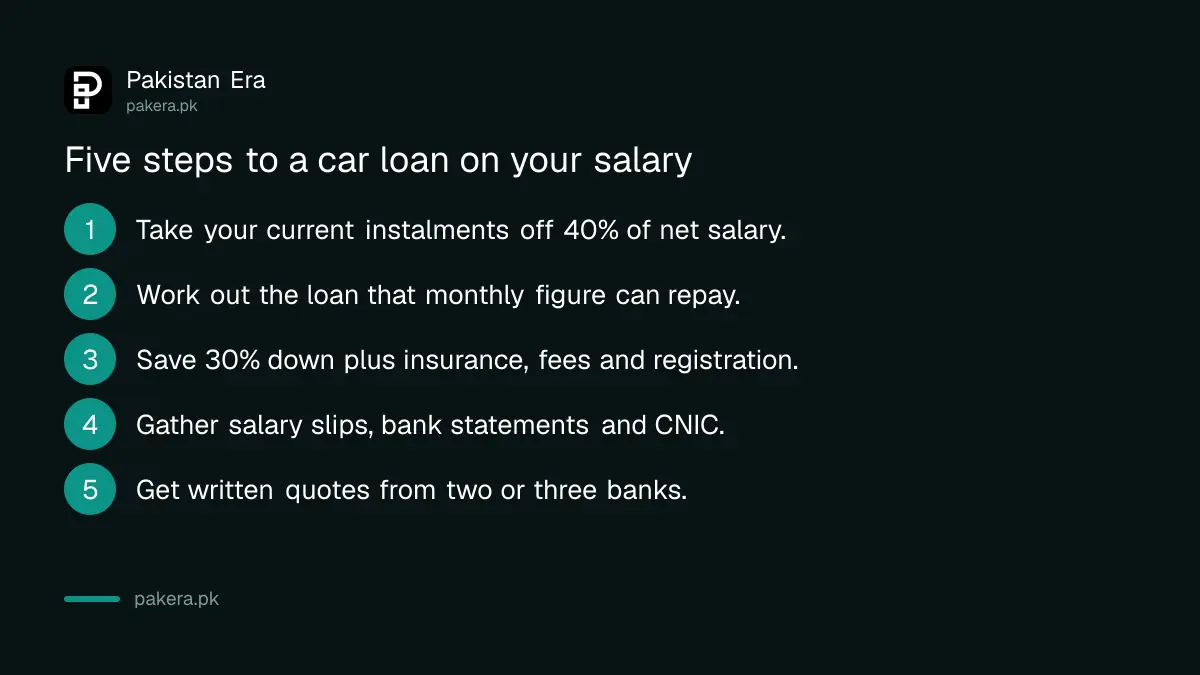
- Add up every loan and card instalment you pay now, and take it off 40% of your net salary.
- Put that figure into the car loan calculator to see the price range you can borrow for.
- Save the 30% down payment, plus first-year insurance, the processing fee and registration.
- Get your salary slips, bank statements and CNIC ready. Meezan, for example, asks salaried applicants for 3 months in the current job and 2 years of continuous work.
- Ask two or three banks for a written quote showing KIBOR, spread, tenure, insurance and total cost.
Rates, fees and processing times for each bank are in what a car loan in Pakistan costs.
Common questions
Can I get a car loan on a Rs 100,000 salary in Pakistan?
Yes, up to about Rs 1.6 million over 5 years at today's rates. That is not enough for any new car on the makers' lists, so you would need a used car or a much larger down payment.
What is the maximum car loan in Pakistan?
Rs 3,000,000 per person across all banks together, under the State Bank's consumer financing rules.
How much down payment do I need for a car loan?
At least 30% of the price. For a car above Rs 4,285,714 you need more, because the loan cannot pass Rs 3 million.
Can I finance a car for 7 years?
No. The limit is 5 years for cars up to 1000cc and 3 years above 1000cc, except under Roshan Apni Car for overseas Pakistanis.
Does my spouse's income count?
Some banks allow it. Meezan's Car Ijarah page says spouse income can be "clubbed up to 50%". Ask your bank exactly how it counts before you apply.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on 6 October 2026. The debt burden, down payment and Rs 3 million cap were read in SBP BPRD Circular Letter 29 of 2021, and the tenure rule in BPRD Circular Letter 19 of 2022. KIBOR was read on the State Bank's home page. Spreads, insurance rates and eligibility were read on Bank Alfalah, Meezan Bank, HBL and Bank AL Habib pages. Car prices are from Suzuki, Toyota and Honda's own websites. All instalments are our calculations.
About the author
Public Services and Education Journalist
Fajr Riaz is a journalist and content writer at Pakistan Era, based in Lahore. She covers the questions people meet in everyday life in Pakistan: how a public service works, what a change in the rules means, and where to find a reliable answer.