Get a Business Loan as a Woman in Pakistan: What the New SBP Guarantee Means
The State Bank has launched a guarantee to back microfinance loans of Rs 25,000 to Rs 3 million for women-led businesses. See how it works and what to ask.
The State Bank of Pakistan (SBP) has started a guarantee that should help microfinance companies lend Rs 25,000 to Rs 3 million to women-led small businesses, for up to 36 months. You cannot apply to SBP for it. You ask a microfinance company, and the guarantee works behind the loan.
We read SBP's ACFID Circular No. 01 of 2026 dated 4 September 2026 and its first annexure, the terms and conditions, on 8 October 2026. The circular is addressed to banks, not to borrowers, so this guide explains what it means for a woman who wants a business loan.
Understand what the guarantee is and is not
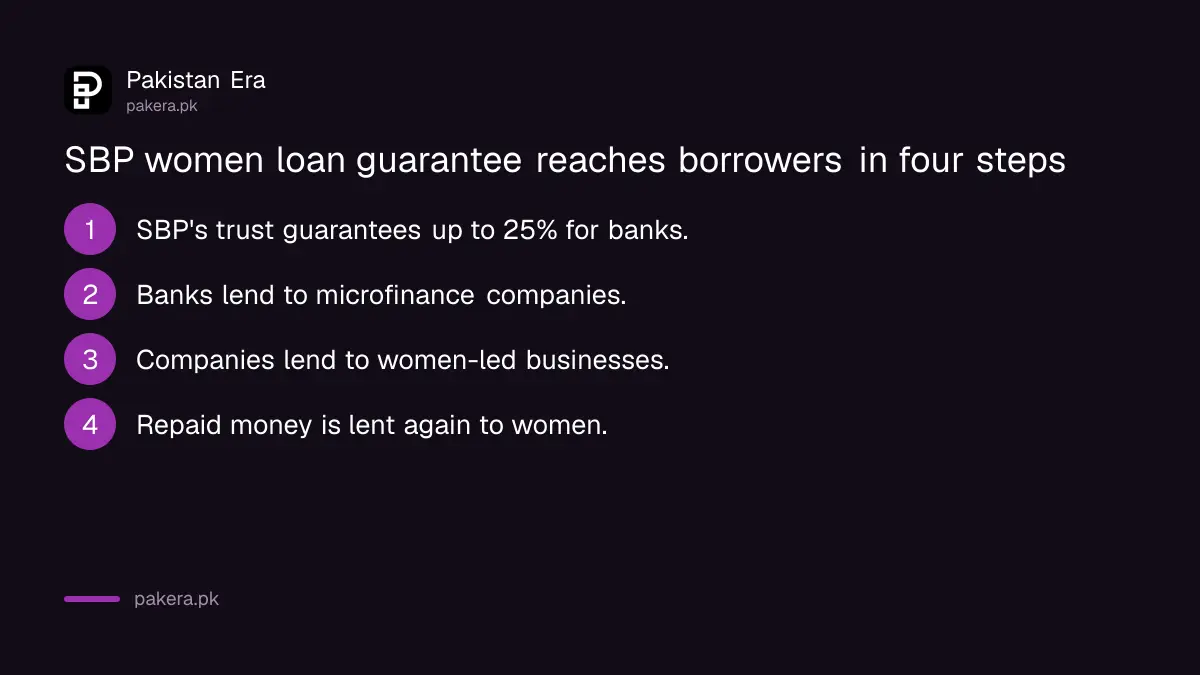
It is a safety net for lenders, not a grant or a loan from SBP. Banks lend to microfinance companies, and SBP's trust promises to cover up to 25% of that portfolio if loans go bad. That should make banks more willing to lend.
The federal government set up the Women Inclusive Finance Support Fund Trust, with SBP as trustee, to run it. The facility is called the Women Microfinance Credit Guarantee Facility, or WMCGF. It is part of the Women Inclusive Finance Sector Development Program.
The annexure says banks get the guarantee without any fee. It covers financing to non-bank microfinance companies and non-bank finance companies, which then lend to women-led micro businesses.
Check the loan size and term you can expect
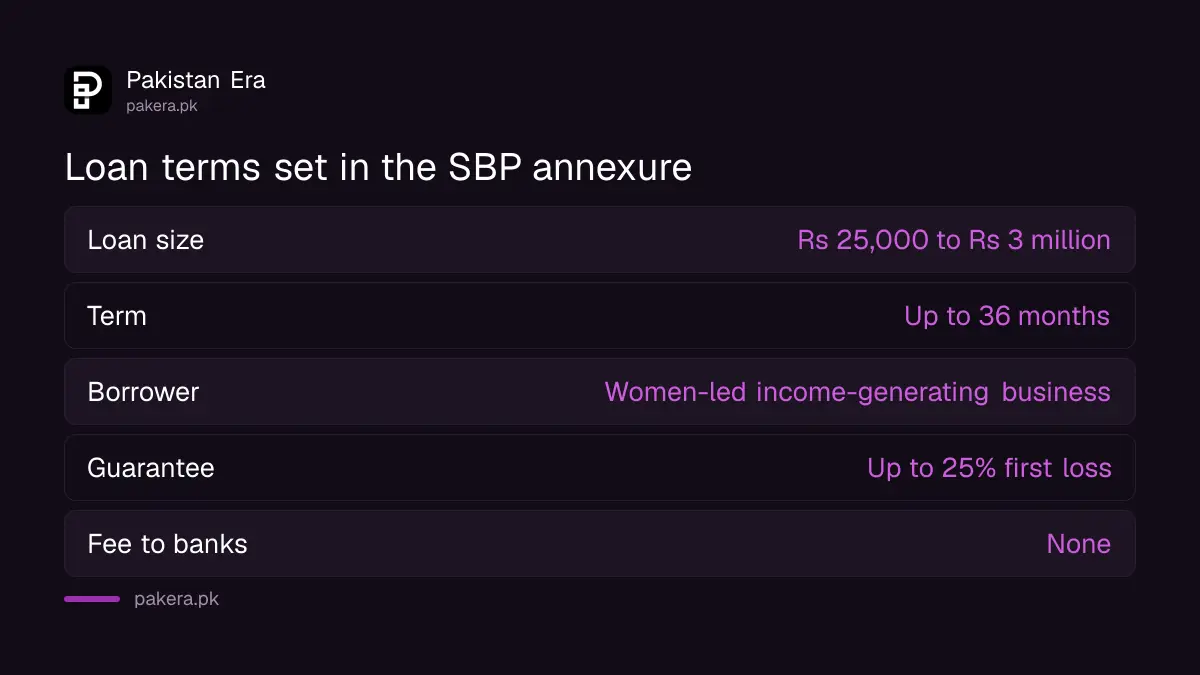
Under the facility, microfinance companies lend between Rs 25,000 and Rs 3 million, for up to 36 months. The loan must go to women-led, income-generating households and businesses only. Other terms such as the mark-up rate are not set in the annexure.
| Feature | What the SBP annexure says |
|---|---|
| Loan size | Rs 25,000 to Rs 3 million |
| Loan term | Up to 36 months |
| Who borrows | Women-led income-generating households and businesses |
| Guarantee cover | Up to 25% of the lender's portfolio, first loss |
| Fee to banks | None |
The rate you pay is not fixed by this scheme, so ask each company for the full rate and fees in writing. Our guide to interest free microfinance loans from Akhuwat shows a lender with no mark-up for comparison.
Ask the lender the right questions
No list of participating microfinance companies has been published yet that we could find. Banks had 30 days from 4 September to apply for guarantee limits, so loans under the facility may only start flowing later.
When you visit a microfinance company, ask these questions:
- Is this loan funded under the SBP women guarantee facility?
- What is the total repayment, including fees, in rupees?
- What is the term, and what is the monthly instalment?
- What happens if I am late by a month?
- Can I get the terms in writing in a language I read?
The annexure tells banks to make sure women borrowers fully understand the terms, to protect them from too much debt. Use that. If a lender hurries you to sign, walk away.
Know what the lender must check before it lends
The annexure sets rules for the lenders, and they protect you. A bank may lend only to a microfinance company that has a plan for women's finance, healthy profits and good governance. The company must also use the money only for women-led businesses.
Loans must also have no or only minor environmental and social impact, which fits a small shop, tailoring unit or home kitchen, and not a polluting factory. When a woman repays a loan, the company must lend that money again to women.
These checks apply to the lender, so you do not need to prove them, but you can ask the company about them. A company that cannot say whether it is part of the scheme probably is not.
Avoid fake lenders using the news
Any new scheme brings scammers. Do not pay anyone a fee to "register" for this guarantee. SBP's circular describes no borrower fee, and there is no application to SBP from borrowers.
Check that the lender is licensed. Our guide to checking whether a lending app is licensed by SECP shows how, and the guide to reporting loan app harassment helps if a lender threatens you. For other routes, see the SheCreates portal for women entrepreneurs and our guide to SME loans from banks.
Common questions about the SBP women guarantee
Can I apply to SBP directly for this loan?
No. The circular is addressed to banks and development finance institutions. Borrowers deal with a microfinance company or bank.
Is the loan interest free?
Not necessarily. The annexure does not set a rate. Ask the lender for the rate and every fee in writing.
Who counts as a woman-led business?
The annexure says loans go to women-led, income-generating households and businesses. It does not give a longer definition in the pages we read, so ask the lender.
When will loans start?
We could not find a start date for loans. Banks were asked to apply for guarantee limits within 30 days of 4 September 2026, and SBP allocates limits after that.
Who do I contact with a complaint?
Complain to the lender first. For a bank, you can then use SBP's complaint route. The annexure lists an email for the Trust Secretariat, but it is for lenders.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 8 October 2026. The loan size, 36 month term, 25% first-loss cover, no fee to banks, 30 day application window, women-led requirement and low impact rule come from SBP's ACFID Circular No. 01 of 2026 and its Annexure-I on sbp.org.pk. We did not read Annexures II and III, and we found no list of participating lenders or a borrower application route. Mark-up rates are not stated, so we state none.
About the author
Public Services and Education Journalist
Fajr Riaz is a journalist and content writer at Pakistan Era, based in Lahore. She covers the questions people meet in everyday life in Pakistan: how a public service works, what a change in the rules means, and where to find a reliable answer.