FBR Drafts Form ATL-U: Late Filers Can Skip the Rs 25,000 ATL Surcharge With a Property Pledge
FBR has drafted Form ATL-U. A late filer would join the ATL without the Rs 25,000 surcharge by pledging no property purchase for six months. Read the draft.
FBR has drafted the form that late filers would use to stay on the Active Taxpayers List without paying the Rs 25,000 surcharge. Form ATL-U is a pledge, filed on IRIS, not to buy or acquire any property for six months. It is a draft and cannot be used yet.
When we reported on the Rs 25,000 surcharge, one question had no answer: where is the form for the undertaking that the law allows? The law was there. The form was not. On 6 October 2026 FBR published a draft of it, nine days before the new 15 October return deadline.
We read the draft, S.R.O. 1691(I)/2026, on FBR's website on 8 October 2026, along with section 182A of the Income Tax Ordinance, 2001. Here is how the draft works, and where it is still unclear.
The draft lets a late filer join the list without the surcharge
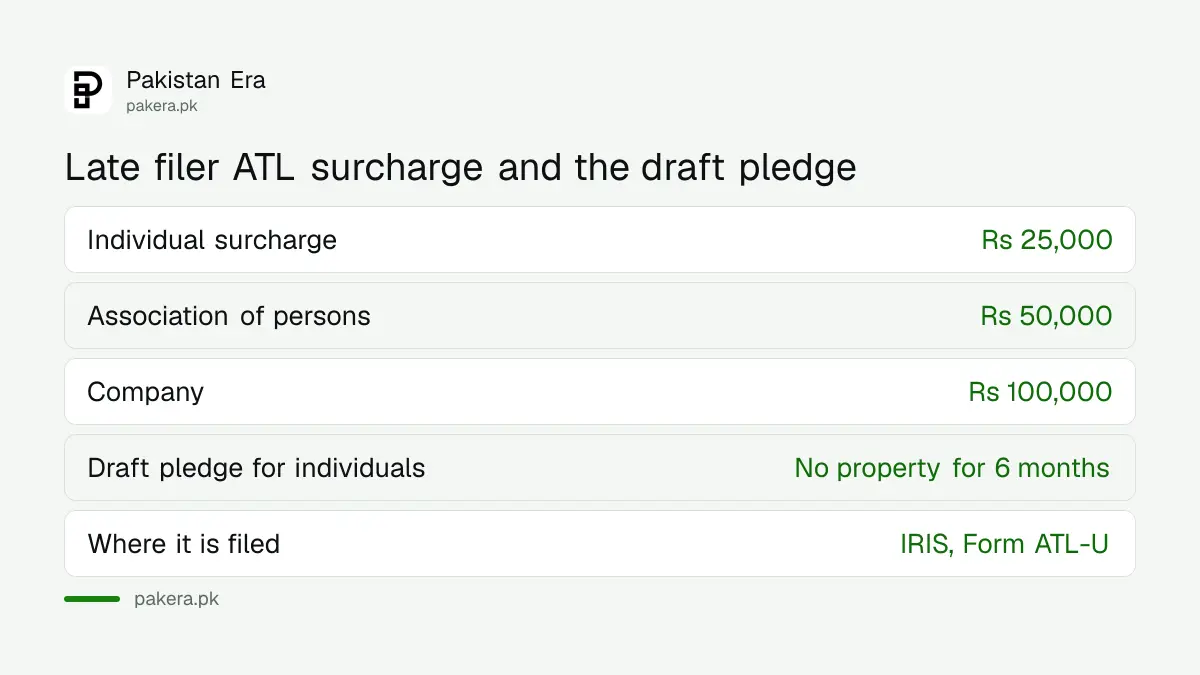
Section 182A bars a person who misses the due date from the Active Taxpayers List, or ATL, unless the person pays a surcharge. For an individual that surcharge is now Rs 25,000, as we explained in the report on the Rs 25,000 ATL surcharge.
Sub-section (3) of that section gives an exit. The surcharge does not apply to an individual who gives an undertaking not to buy, acquire or obtain ownership or beneficial interest in any property for six months. The law said the form would be "as may be prescribed". The draft is that form.
Under the draft new sub-rule (2B) of rule 81B of the Income Tax Rules, an individual who files late and submits Form ATL-U through IRIS is included in the ATL without paying the surcharge.
It is a draft dated 6 October 2026 and not yet usable
The notification is S.R.O. 1691(I)/2026, dated 6 October 2026. It is a draft under section 237 of the Ordinance. FBR asks for objections and suggestions within seven days of publication in the official Gazette. We did not find the Gazette date, so we cannot name the closing day.
Until FBR notifies a final rule, IRIS will not carry the form. If you miss the deadline today, the only option on the page is to pay the surcharge. Do not expect a counter or a tax office to accept a hand-written pledge in the meantime.
The six months start from your IRIS acknowledgement
The draft is specific about timing. Under sub-rule (2C), the six-month period begins on the date shown on the electronic acknowledgement IRIS issues when you successfully submit Form ATL-U. The date you file the return does not start it.
| Part of the draft | What it says |
|---|---|
| Who | An individual who files the return for the latest tax year after the due date or extended due date |
| How | Submit Form ATL-U through IRIS, verified under rule 73 |
| Benefit | Included in the ATL without the surcharge in section 182A(1)(a) |
| Pledge | No purchase, acquisition or beneficial interest in any property for six months |
| Start date | The date on the IRIS acknowledgement |
| Form details | Name, CNIC or NTN, tax year, return filing date, IRIS reference number and date of the undertaking |
The draft form says the filer declares the information is true and complete, and that the benefit depends on keeping the pledge.
FBR may check the pledge and withdraw the benefit
Sub-rule (2D) lets FBR verify compliance from information under the Ordinance or from any authority, agency, registry, financial institution or other lawful source. If that information shows you bought or acquired property during the six months, you get an electronic chance to be heard.
If the breach is established, the benefit is withdrawn from the date of the breach. Your place on the ATL then follows the ordinary rule for late filers. The draft does not spell out what that means in rupees, so we cannot say whether the Rs 25,000 would then fall due. We would read it as likely, but that is our reading, not the text.
The pledge covers "any property". The law and the draft do not narrow it to land or houses. Whether a car, a plot file or other assets count is not stated. Ask a tax adviser before you rely on a narrower meaning.
Who should wait, and who should file by 15 October
The best way to avoid the surcharge and the pledge is to file on time. The deadline is 15 October 2026, set by the circular in our report on the tax return deadline extension.
- File by 15 October if you can. No surcharge, no pledge.
- If you miss it, count your property plans. A pledge costs nothing if you will not buy anything for six months.
- Do not use the pledge in the middle of a purchase. A plot or house you are buying could be a breach. Paying the Rs 25,000 may be simpler.
- Wait for the final form. Check IRIS and FBR's SRO page for the notified rule before you plan around the draft.
- Check your status after filing. Use the steps to check your filer status in Pakistan.
Common questions
Can I use Form ATL-U now?
No. S.R.O. 1691(I)/2026 is a draft published on 6 October 2026. FBR must notify the final rule before IRIS can carry the form.
Does the pledge apply to companies?
No. Section 182A(3) and the draft are for individuals. Companies and associations of persons still pay their surcharges, Rs 100,000 and Rs 50,000.
What property is covered?
The law says "any property" and the draft repeats it. Neither names land, houses or vehicles, so ask an adviser before a purchase.
When do the six months begin?
On the date shown on the IRIS acknowledgement after you submit the form, under draft sub-rule (2C).
What if I buy property during the six months?
FBR would give you an electronic hearing. If it proves the breach, the benefit is withdrawn from the date of the breach.
Does the pledge cancel the late filing penalty?
No. It covers the surcharge for inclusion in the ATL only. Section 182A itself says the surcharge is without prejudice to any other liability under the Ordinance.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on 8 October 2026. We read the draft notification S.R.O. 1691(I)/2026, dated 6 October 2026, from FBR's SRO page, and section 182A of the Income Tax Ordinance, 2001 in FBR's consolidated copy, amended up to 30 June 2026. We did not read the existing text of rule 81B, and we found no Gazette date for the draft. What happens to the surcharge after a breach is our reading, not the text. Nothing here is tax advice.
About the author
Tax, Bills and Technology Writer
Ali Akhtar is a young and curious voice here at Pakistan Era. He is currently pursuing his A-Levels and has a growing interest in Pakistan’s changing industrial landscape and educational trends. Ali likes to write in a way that helps him explain and explore the world around him. His writing reflects the perspective of the new generation navigating the evolving trends of Pakistan where technology, youth innovation, and shifting opportunities are reshaping the country’s future.