Prepare for an FBR Order to Re-Audit Your Accounts: Panel Accountant Rules in Pakistan
The Finance Act 2026 lets an FBR Commissioner order a re-audit by a panel accountant after a hearing. See the safeguards, the 15 day objection and steps.
Short answer: The Finance Act 2026 lets an FBR Commissioner direct you to get your accounts re-audited by an accountant that FBR nominates from its panel. The Commissioner needs the Chief Commissioner's prior approval and must hear you first. Under income tax you can object to the nominee within 15 days of the nomination.
Until now, an audit meant FBR officers reading your papers. The Finance Act 2026 adds another route for complex cases. FBR can ask an outside accountant to re-audit your books, and you must furnish the report.
We read the new provisions in the Act on FBR's own download site on 13 October 2026. They sit in section 177 of the Income Tax Ordinance and section 25 of the Sales Tax Act. This page explains who can be affected and how to prepare.
The Commissioner can order a re-audit in complex cases
Under new sub-section (6B) of section 177, the Commissioner can act at any stage of the proceedings. The Act lists five reasons. The Commissioner must also think the step is necessary.
- The nature and complexity of the accounts.
- The volume of the accounts.
- Doubts about the correctness of the accounts.
- Many separate transactions in the accounts.
- The specialised nature of the taxpayer's business.
The Commissioner may then direct the taxpayer to get the accounts re-audited by an accountant, and to give a report signed and verified by that accountant. The report must answer the specific queries the Commissioner sets.
Three safeguards come before the order
The Act sets conditions on the power. The Commissioner must first give the taxpayer a reasonable opportunity of being heard. The Commissioner also needs the previous approval of the Chief Commissioner.
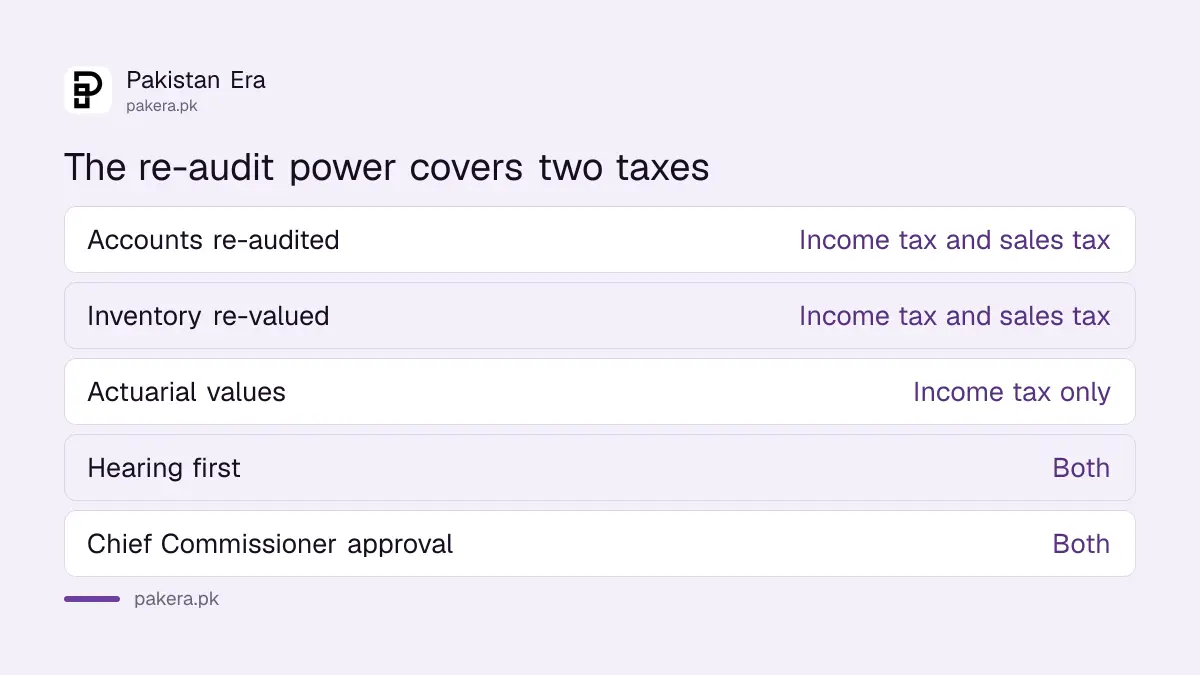
| What FBR can direct | Income tax, section 177(6B) | Sales tax, section 25(8A) |
|---|---|---|
| Accounts re-audited by an accountant | Yes | Yes |
| Inventory re-valued by a cost accountant | Yes | Yes |
| Actuarial values set by an actuary | Yes | Not listed |
| Hearing before the order | Required | Required |
| Chief Commissioner's prior approval | Required | Required |
The income tax rule covers the accountant, the cost accountant and the actuary. The sales tax rule covers the first two. A taxpayer who is both an income tax payer and a sales tax registered person could face both.
FBR picks the accountant from its own panel
You do not choose your own auditor. The Commissioner nominates the accountant, cost accountant or actuary from a panel set by the Board. The word nominated means FBR names the person.
The income tax text gives you one chance to object. If you object to the nomination within fifteen days, the Commissioner may change the accountant or cost accountant for another one, if he agrees with your objection. The text does not make a change automatic. The sales tax text we read has no objection step.
Prepare before any order arrives
The Act does not say who pays the re-auditor. We did not find a cost rule in the text we read. Ask for that detail in writing when you attend the hearing.
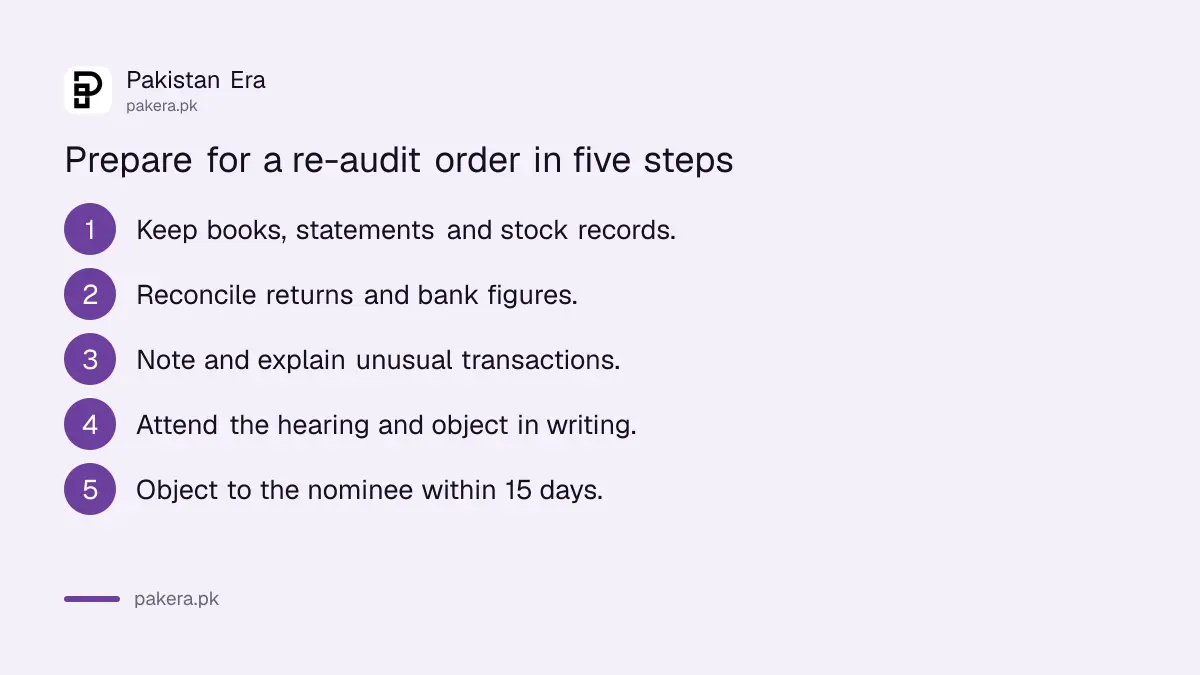
- Keep full books, bank statements, invoices and stock records for the years in question.
- Reconcile your sales tax returns, income tax return and bank figures now.
- List the large or unusual transactions and keep a note explaining each one.
- Attend the hearing and put objections to the order in writing.
- If a nominee is named, check for any conflict and object within fifteen days under income tax.
Record keeping is the foundation. See our guide on keeping sales tax records for six years. For the audit notice itself, read how to reply to a section 177 audit notice.
Audit reports follow a set order in sales tax
The Act also adds section 25(8B). After completion of the audit, the officer must obtain the registered person's explanation on all the issues raised, and then issue an audit report with observations and findings.
The Act also changes sub-section (9), so that a time reference there now counts from issuing the audit report instead of completing the audit. We did not read what that time reference governs. The change gives the report a clear place in the process. FBR is also moving audits to a faceless system. See FBR's National Faceless Centre for that side.
Common questions
Can FBR make me hire an auditor?
Under the new provisions the Commissioner can direct a re-audit of your accounts by an accountant nominated from FBR's panel, after a hearing and with the Chief Commissioner's approval.
Can I choose the accountant?
No. The Commissioner nominates from the Board's panel. Under income tax you can object within fifteen days of the nomination.
Does it apply to sales tax as well?
Yes. Section 25(8A) of the Sales Tax Act has a similar power for accounts and inventory.
Who pays for the re-audit?
The text we read does not say. Ask at the hearing and get the answer in writing.
Is a hearing required?
Yes. The Commissioner must give a reasonable opportunity of being heard before directing a re-audit.
When does this apply from?
The Finance Act 2026 came into force on 1 July 2026 unless it says otherwise. We found no later start for these provisions.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on 13 October 2026, Pakistan time. We read section 177(6B) of the Income Tax Ordinance and section 25(8A) and (8B) of the Sales Tax Act as inserted by the Finance Act 2026 on FBR's download site. We did not find FBR rules on the panel, the fee or the process, so these points are unconfirmed.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.