Joint Bank Account in Pakistan: 5 Things Your Bank Must Explain Before You Sign
Before you open a joint bank account in Pakistan, SBP guidelines say the bank must explain five things, from the signing rule to set-off. See what to ask.
Before you open a joint bank account in Pakistan, the State Bank's conduct guidelines say the bank must explain five things: how the account works, each holder's rights and duties, what the signing rule means, any right of set-off, and your possible liability for debts on the account. Ask for each in writing and keep the copy.
Two people share one account and one of them signs a cheque. The other holder may be bound by it, even if they never saw it. That is the first of the surprises the State Bank of Pakistan (SBP) wants banks to warn you about. We read SBP's Guidelines of Business Conduct for Banks on 15 October 2026. The version on SBP's site cites circulars up to 2015, and we found no newer replacement.
Section 4.7 lists what the bank must tell you before you open a joint account
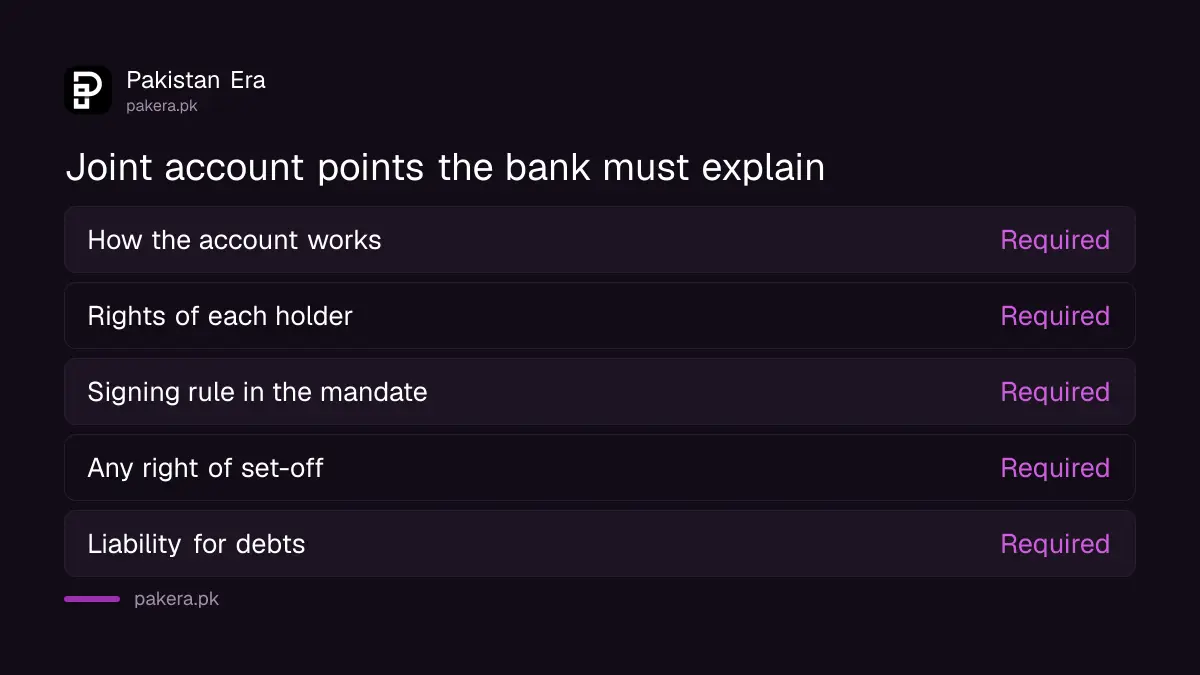
SBP's guidelines, in section 4.7.1, name five things a bank must tell customers before it opens a joint account. They are a general description of how the account works, each customer's rights and responsibilities, the signing rule, set-off and the liability for debts.
| What the bank must explain | Why it matters to you |
|---|---|
| How a joint account is operated | Who can deposit, withdraw and close it |
| Rights and responsibilities of each holder | What each person can and cannot do alone |
| Signing arrangement in the mandate | A transaction by an authorised signatory binds all holders |
| Bank's right of set-off | The bank may take money from the account to settle a debt |
| Liability for debts on the account | You may be liable for a debt another holder runs up |
The signing rule decides who can spend the money
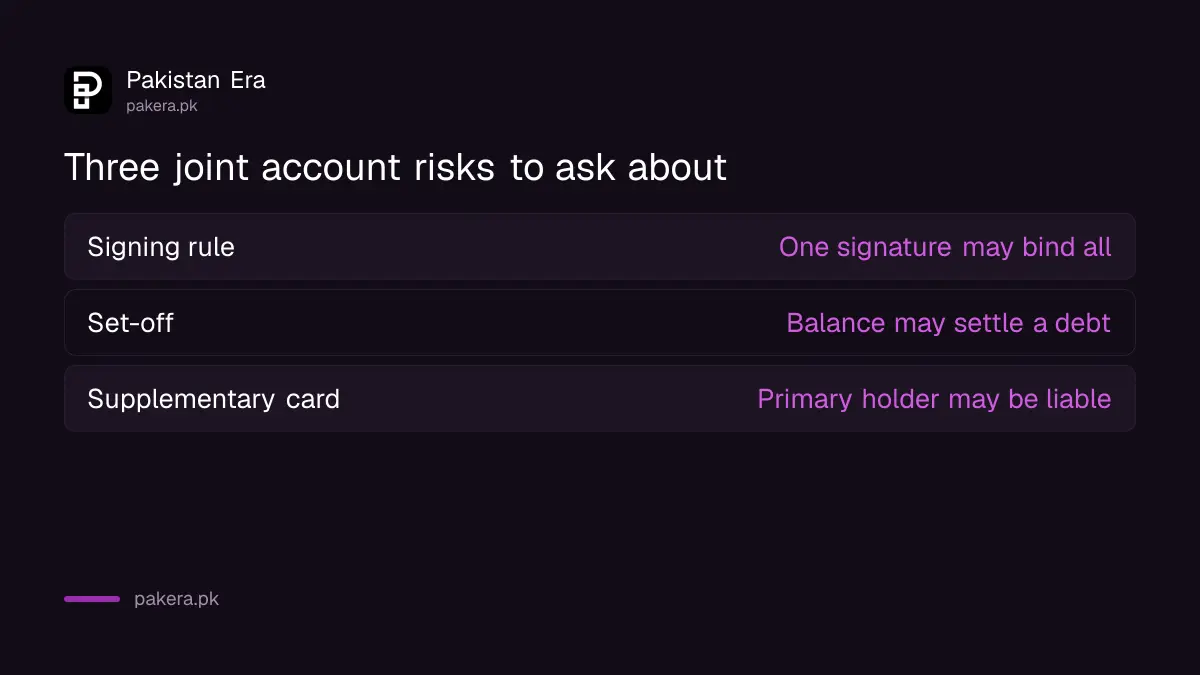
The mandate is the signed instruction that says who may operate the account. SBP says any transaction by the authorised signatory, or signatories, is binding on all account holders. A mandate that lets either person sign gives each holder full power over the whole balance.
A mandate that needs both signatures is slower but safer. Banks use different words for these arrangements, so ask the officer to write the rule in plain language on the form. Choose it before you sign.
Set-off means the bank can use the balance to settle a debt
SBP's glossary describes set-off as a clause that lets a bank use a customer's deposits when they default on a loan. In section 4.9.2(h) the guidelines say a bank must tell a borrower about its right to set off credit balances in other accounts, including a joint account of the borrower.
So if your co-holder has a loan, ask the bank whether it claims set-off on the joint balance. The guidelines require the bank to disclose the right. They do not say whether a court would allow it in a given case. Our reading is limited to what must be disclosed.
Check the account type and who can open it before you ask for the form
The steps to open a bank account in Pakistan show the documents every holder must bring. If a child is involved, the rules are in opening a minor bank account.
Bring the CNIC of every holder and ask for the schedule of charges. Section 3.4.2 of the guidelines also requires the bank to tell you how profit is paid after tax, when Zakat may be deducted, and how and when a cheque may be stopped.
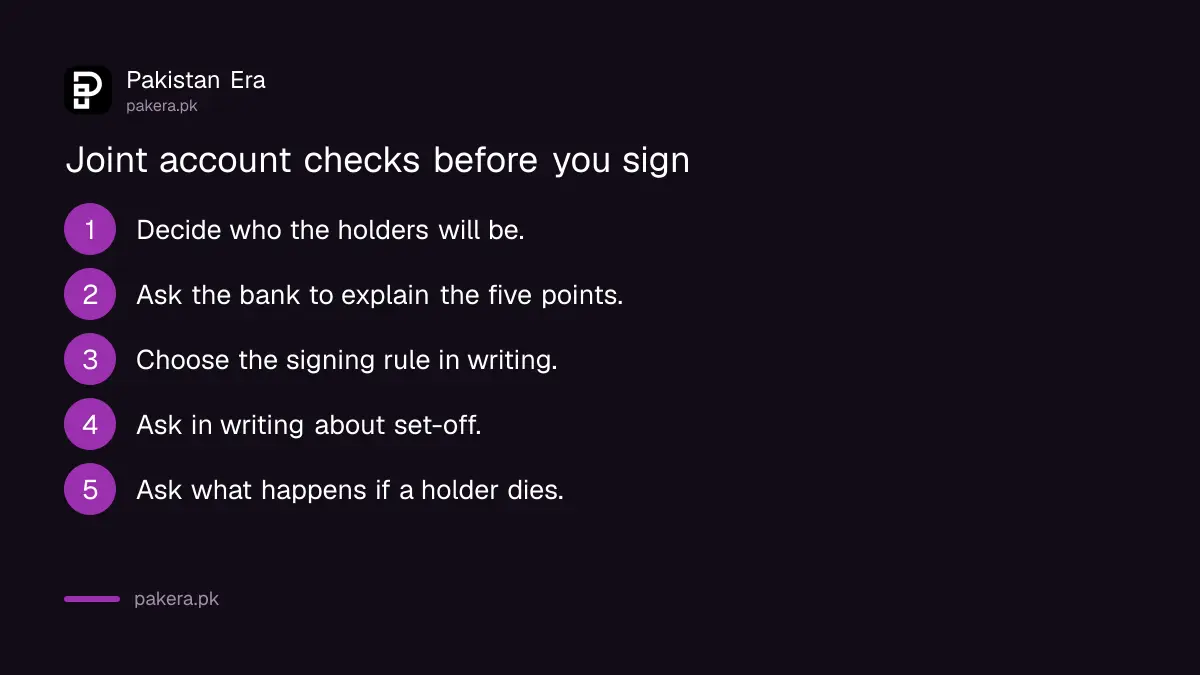
- Decide who will be holders and why each person needs access.
- Ask the bank to explain the five points in section 4.7.1 in plain words.
- Choose the signing rule and have it written on the mandate.
- Ask in writing whether set-off applies to the joint balance.
- Ask what happens if one holder dies, and note the answer.
- Keep a copy of the signed form and the fee schedule.
Step five matters because the guidelines are silent on it. They do not describe what happens to a joint account when a holder dies. Get the bank's answer in writing before you rely on it.
Supplementary cards carry their own liability
Section 4.7.2 covers a supplementary debit or credit card, the second card issued on your account. The bank must tell the primary cardholder that they may be liable for debts the supplementary cardholder runs up, and how the card can be cancelled.
The guidelines add that you are not liable for continued use of a supplementary card from the date you ask the bank to cancel it and return the card. Return the card and keep the receipt, because the date on it protects you. If you want to close the account, see how to close a bank account in Pakistan.
If the bank will not explain, complain in writing first
SBP's complaints portal explains the order: first complain to the bank's own complaint management unit. If it does not answer within 45 days, or you are unhappy with the result, you can go to the Banking Mohtasib Pakistan.
Details of both steps are in the guide to the Banking Mohtasib complaint and the page on SBP's Sunwai portal. Send the first complaint by email or a signed letter and keep the proof of delivery.
Common questions about joint bank accounts in Pakistan
Can one holder withdraw all the money from a joint account?
It depends on the signing rule in the mandate. If either holder may sign, yes. SBP says a transaction by an authorised signatory binds all holders.
Can a bank take money from a joint account for one holder's loan?
SBP requires the bank to tell the borrower of any right of set-off against a joint account. Ask the bank whether it claims that right.
Do all holders have to be at the branch to open the account?
The guidelines do not say. Each bank sets its own rule, so ask before you travel and bring every holder's CNIC.
What happens to a joint account when one holder dies?
SBP's guidelines do not say. Ask the bank for its written rule before you open the account.
Am I liable for my co-holder's overdraft?
SBP says the bank must warn you of potential liability for debts incurred on the joint account. Treat that warning as real and ask for the terms.
Are these guidelines still current?
The version on SBP's site cites circulars up to January 2015. We found no newer replacement, but SBP may have issued narrower rules since.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 15 October 2026. Sections 3.4, 4.7 and 4.9 and the definitions come from SBP's Guidelines of Business Conduct for Banks. The complaint order comes from the FAQ of SBP's Sunwai portal. We did not open a joint account to test a bank's disclosure. Banks may add rules beyond the guidelines, and this page explains them and is not legal advice.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.