Claim a Sales Tax Refund From FBR: Who Can Claim, Papers and the 45 Day Rule
Claim a sales tax refund from FBR: the six situations that qualify, papers due within 60 days of the return and the 45 day payment rule. Read before you file.
Short answer: A registered person can claim a sales tax refund from FBR when input tax exceeds output tax on zero rated supplies or exports. FBR's page says the refund is due not later than 45 days after the claim is filed. You must submit the supporting documents on the prescribed software within 60 days of filing the return.
A small exporter pays sales tax on his inputs: yarn, packaging, freight. He then sells abroad at zero rate and collects nothing. The tax he paid sits with FBR as a credit. If he does not claim it correctly, it stays there. This guide covers the sales tax refund, which is a different thing from an income tax refund.
We read the FBR sales tax refund pages on 12 October 2026. They are written for registered persons, so we keep their wording close and explain each term.
You can claim when input tax is more than output tax on zero rated sales
FBR says that if the input tax a registered person paid on taxable purchases in a tax period exceeds the output tax on zero rated local supplies or exports in that period, the excess is refunded. The refund is due not later than 45 days after the claim is filed.
"Input tax" is the sales tax you paid on what you bought for your business. "Output tax" is the sales tax you charged your customers. "Zero rated" means sold at 0 per cent tax, so you charge nothing but can still recover what you paid.
FBR adds that the refund is paid in the manner and subject to the conditions the Board notifies in the official Gazette. The page does not say what happens to the 45 days if FBR asks for more papers.
Six situations in which FBR lets you claim
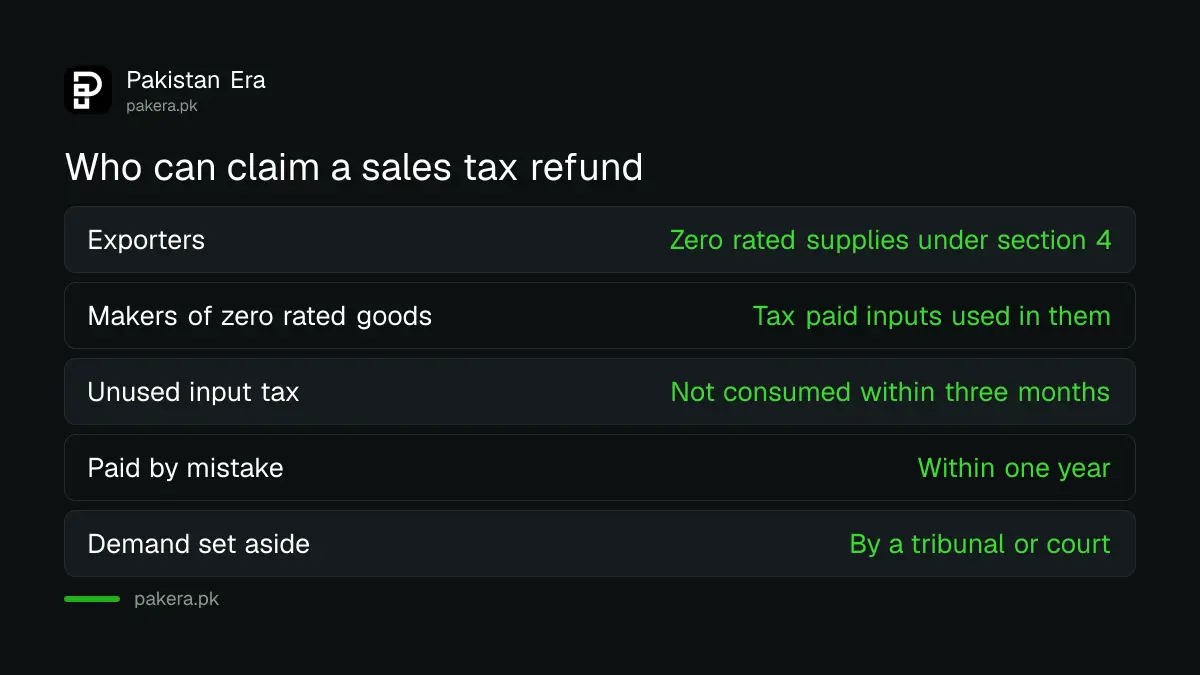
FBR lists six kinds of claimant: exporters, makers of zero rated goods, persons with input tax not consumed in three months, makers who export goods whose local supply is exempt, persons who paid by mistake, and persons whose paid demand was later set aside by a tribunal or court.
| Who can claim | Situation, in FBR's words made plain |
|---|---|
| Manufacturer-cum-exporters and commercial exporters | They zero rate all or part of their supplies under section 4 |
| Makers of zero rated goods | They buy tax paid inputs to make goods taxed at zero per cent |
| Persons with unused input tax | Excess input tax could not be consumed within three months |
| Exporters of goods exempt locally | They buy tax paid inputs for goods whose local supply is exempt |
| Anyone who paid by mistake | Tax was paid inadvertently or in error |
| Anyone whose paid demand was set aside | A tribunal, court or other competent authority cancelled the demand |
How the claim is filed and the 60 day limit
FBR says your monthly sales tax return is treated as a refund claim once all supporting documents and the data in the prescribed format or software are received. No claim is entertained if you fail to furnish it on the prescribed software with the documents within 60 days of filing the return.
Our guide to filing a monthly sales tax return covers the return itself. The refund claim then sits on top of it.
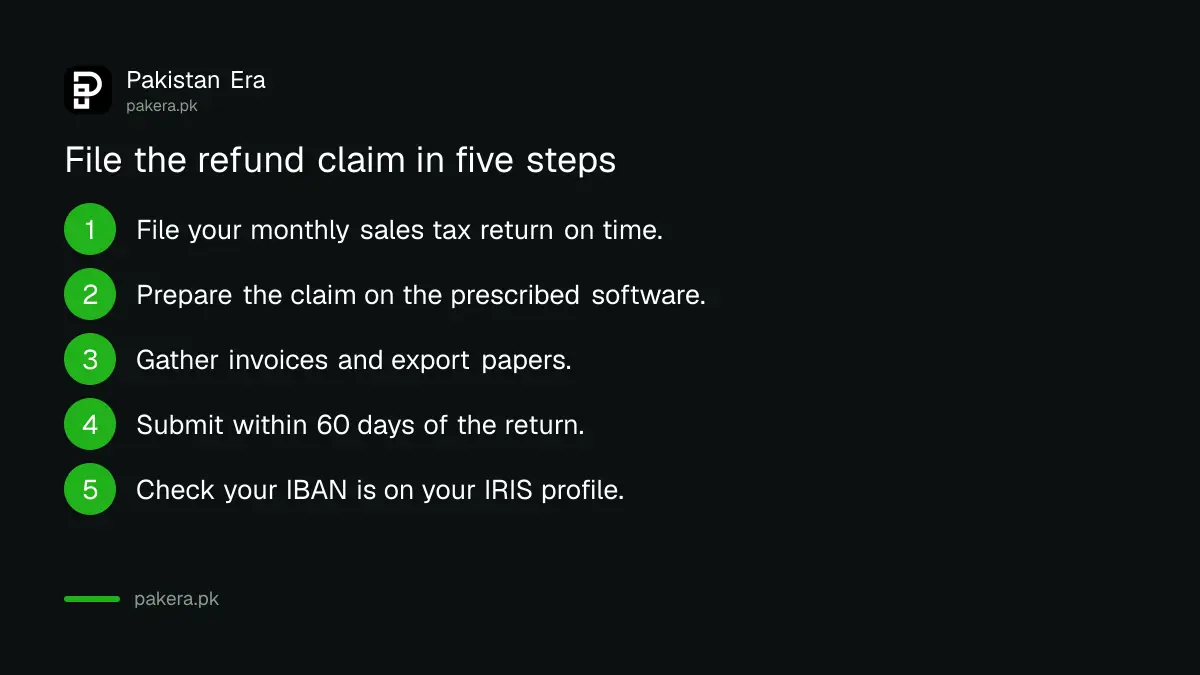
- File your monthly sales tax return on time.
- Prepare the claim on the prescribed software, which FBR describes for the FASTER system under Annex H.
- Gather the supporting documents listed below.
- Submit the claim and documents to the Refund Division of your Collectorate, RTO or Large Taxpayer Unit within 60 days of the return.
- Check that your IBAN is on your IRIS profile so the money can be paid electronically.
Documents FBR asks for
The documents include input tax invoices or import declarations, output tax invoices for local zero rated goods, export declarations and bills of lading or airway bills, and a statement of the tax paid inputs. Commercial exporters add a bank credit advice and any duty drawback order.
For goods processed through WeBOC, FBR says submission of a goods declaration is not required. Cases are cross-matched with data in the system. WeBOC is the customs system.
A claim under section 66 of the Act, for tax paid by mistake or a demand set aside, needs an application and different papers: the input tax invoices, proof of payment of the input tax and a copy of the order on which the refund is based. FBR says the refund is sanctioned after verifying that nothing was claimed earlier and that the invoices are validated by the CREST system.
Registration is the first step to any of this. If you are not registered, read our guide on sales tax registration documents.
Put your IBAN on IRIS or the payment may not reach you
FBR says a centralized system now pays sales tax and federal excise duty refunds online. Taxpayers are asked to update their IRIS profile and add the full IBAN of the same bank account already recorded there. FBR links a document called "Steps to add new Bank Account".
If the account on file is closed or belongs to someone else, a refund cheque can be held up. FBR points to its own step by step document for adding a bank account to IRIS.
An amount overpaid by error has a time limit. FBR says a registered person may ask for it within one year after the payment, or after the order that causes the refund, from the end of the period for which the claim is made.
When a refund is late or refused
If 45 days pass and nothing arrives, first check that your documents were accepted on the prescribed software. Then write to the Refund Division. If that fails, you can complain to the tax ombudsman, as explained in our guide to the Federal Tax Ombudsman.
FBR's pages do not describe what happens after a refusal. Appeal rights for a refused sales tax claim are not set out there, so take advice from a tax professional. For comparison, our note on appealing an income tax order shows the income tax route, which is different.
Common questions
How long does FBR take to pay a sales tax refund?
FBR's page says not later than 45 days after the refund claim is filed. The page does not say what happens if the documents are incomplete.
Who can claim a sales tax refund in Pakistan?
Registered persons in six situations, mainly exporters and makers of zero rated goods, but also those who paid by mistake or whose paid demand was set aside.
Is there a deadline to file the refund documents?
Yes. FBR says no claim is entertained if the claim and documents are not furnished on the prescribed software within 60 days of filing the return.
Can I claim a refund of sales tax paid by mistake?
Yes. FBR says a registered person may ask within one year of the payment, or of the order causing the refund, as described on its page.
Do I need an IBAN for the refund?
FBR asks taxpayers to add the full IBAN of the bank account already on the IRIS profile, so refunds can be paid electronically.
Is this the same as an income tax refund?
No. This refund is for sales tax and federal excise duty. For income tax, see our guide to claiming an income tax refund.
How we verified this
What we checked, where we read it, and what we could not confirm.
We read FBR's Sales Tax Refund pages, including who can claim, filing of the claim, the FASTER system, the centralized payment system and refund of amounts overpaid, on 12 October 2026. We did not read the Sales Tax Act text or the FASTER Annex H document. Check the FBR pages before you file.
About the author
Public Services and Education Journalist
Fajr Riaz is a journalist and content writer at Pakistan Era, based in Lahore. She covers the questions people meet in everyday life in Pakistan: how a public service works, what a change in the rules means, and where to find a reliable answer.