Wrong Details in Your Tax Return: FBR Penalty Is Rs 25,000 or the Full Tax Shortfall
FBR's penalty table sets Rs 25,000 or 100% of the tax shortfall for false statements in a return. See when it applies, the safeguards and how to fix a mistake.

Short answer: If you give FBR false or misleading information, the penalty on FBR's own penalty table is Rs 25,000 or 100% of the tax shortfall, whichever is higher. Hiding income in a proceeding carries Rs 100,000 or the tax you tried to avoid. A penalty needs a written order and a hearing first.
Many people file their return in a hurry before the deadline. Some copy a figure from a friend. Some leave out a small side income. Reports on 12 October said FBR plans to act on false returns. We did not find a new FBR notice for that, so this guide explains the penalty rules already in the law, and how to fix a mistake before it becomes a penalty.
We read the penalty table in section 182 of the Income Tax Ordinance on FBR's website on 13 October 2026. All figures below come from that page.
The penalty for a false statement is Rs 25,000 or the full shortfall
Item 10 of the table covers a false or misleading statement to an Inland Revenue authority. This includes a return, a declaration, an objection or books of account. The penalty is Rs 25,000 or 100% of the tax shortfall, whichever is higher.
The shortfall is the tax you should have paid minus the tax you did pay. Take two examples. If the shortfall is Rs 10,000, the penalty is Rs 25,000, because that is higher. If the shortfall is Rs 80,000, the penalty is Rs 80,000. You would also owe the Rs 80,000 of tax itself.
The same item covers leaving something out. If you omit a fact and the statement becomes false or misleading because of it, that is also covered.
Hiding income carries a second, separate penalty
Item 12 applies when a person has concealed income or given inaccurate particulars of income during a proceeding. Examples on the page include suppressing income and claiming an expense that was never spent. The penalty is Rs 100,000 or the tax you tried to evade, whichever is higher.
The page also gives a safeguard. No penalty is payable on the mere disallowance of a claim for exemption or a deduction, unless it is proved that you made the claim knowing it was wrong. An honest dispute about a rule is not the same as a lie.
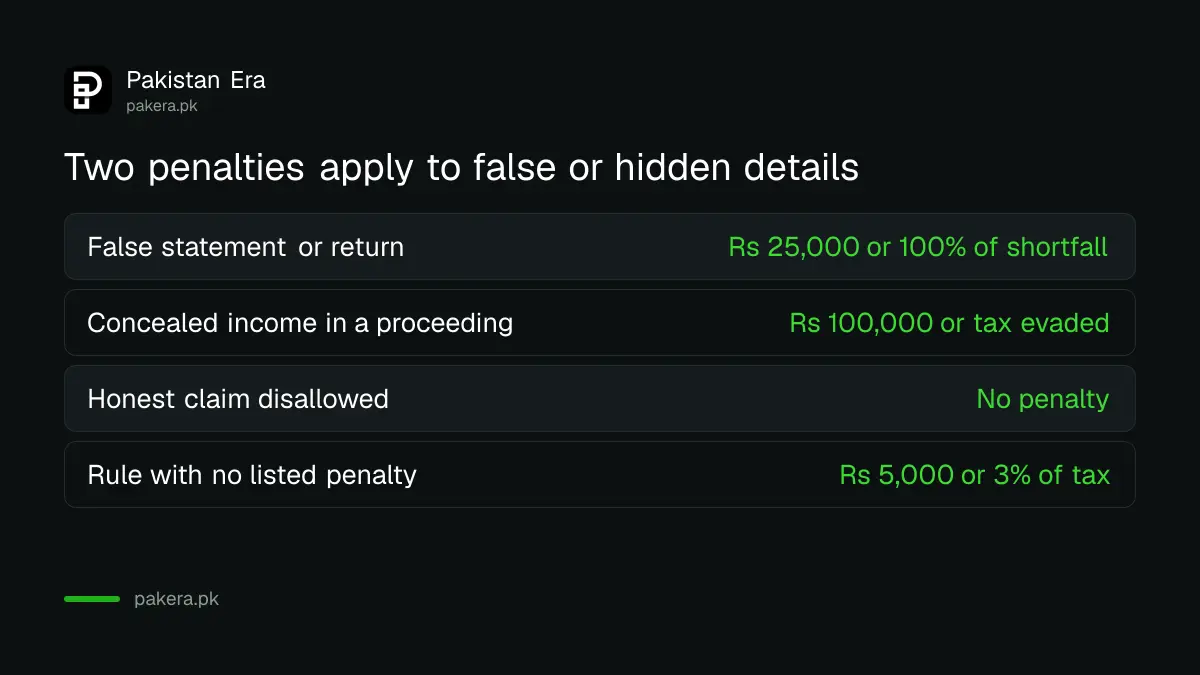
| Situation | Penalty on FBR's page |
|---|---|
| False or misleading statement or return | Rs 25,000 or 100% of tax shortfall, whichever is higher |
| Concealed income or inaccurate particulars in a proceeding | Rs 100,000 or the tax sought to be evaded, whichever is higher |
| Deduction disallowed, but claimed honestly | No penalty unless you knew the claim was wrong |
| Any rule with no listed penalty | Rs 5,000 or 3% of the tax involved, whichever is higher |
No penalty can be imposed without a written order and a hearing
Section 182(2) says no penalty is payable unless the Commissioner, the Commissioner (Appeals) or the Appellate Tribunal passes a written order. The person must be given an opportunity to be heard first. A message or a phone call is not a penalty order.
The same subsection lets you pay voluntarily if you admit the default. If a penalty is later reduced because the tax behind it was reduced, the penalty falls with it.
If a notice arrives, read the date and the section number first. Then follow the steps in the guide to replying to a show cause notice. If an order is already passed, the route is explained in appealing to the Commissioner (Appeals).
Fix a mistake before FBR finds it
The safest step is to correct your own return. You can revise a return that you have already filed, as explained in the guide to revising an income tax return. Do this before any notice reaches you.
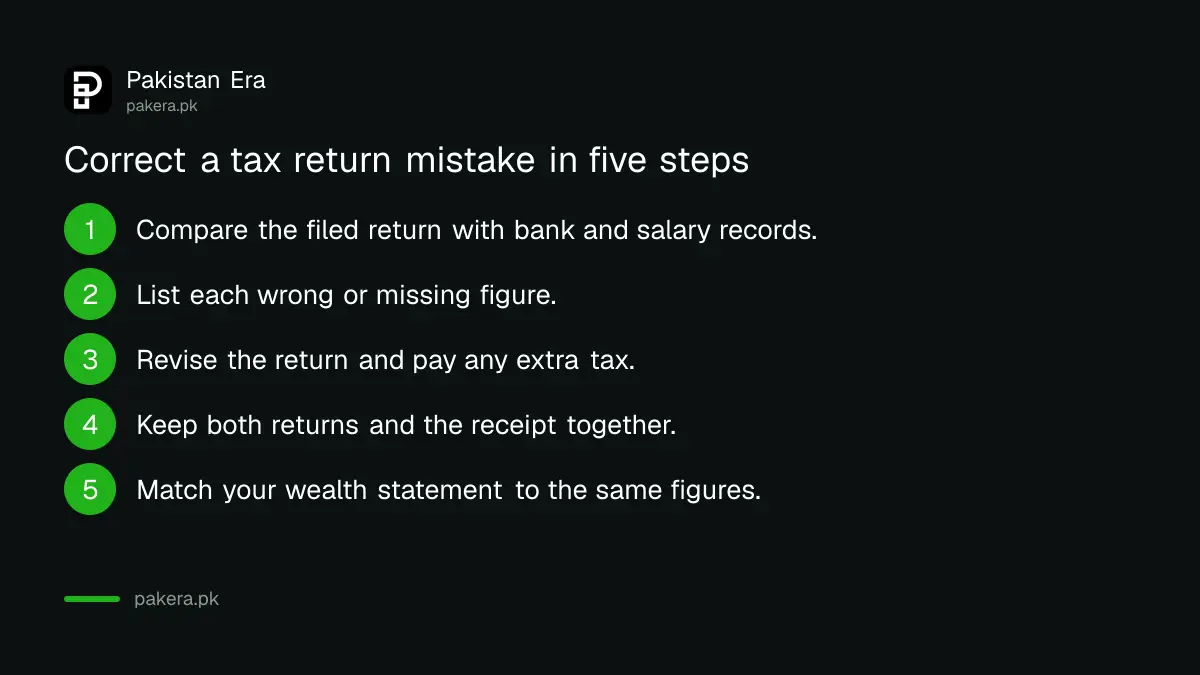
- Open your filed return in IRIS and compare it with your bank statements, salary slips and property papers.
- Write down every figure that is wrong or missing, and the correct amount.
- Revise the return and pay any extra tax at once.
- Keep the old return, the revised return and the payment receipt together.
- Use the same figures in your wealth statement, so the two documents agree.
We have not confirmed how long you have to revise. Check the current rule on FBR's page before you rely on a date.
FBR is checking returns against outside data
FBR has said it is building tools to match returns with data from banks, property records and vehicle registers. A draft rule for this is explained in the page on Rule 38B electronic scrutiny. The wealth statement is a common weak point, and FBR has already described one large case in the guide on the Rs 9.41 billion wealth statement fraud.
This matters for ordinary filers. A mismatch between your return and your bank data is easy for a computer to find. An honest correction costs far less than a penalty.
Common questions
Is a small mistake in my return a false statement?
Not automatically. The penalty is for a false or misleading statement. An honest error that you correct quickly is much easier to defend. Fix it by revising the return.
How much is the penalty for a wrong tax return in Pakistan?
On FBR's penalty table it is Rs 25,000 or 100% of the tax shortfall, whichever is higher. Concealing income in a proceeding is Rs 100,000 or the tax evaded.
Can FBR fine me without telling me?
No. Section 182(2) requires a written order after you are given a chance to be heard. You can also appeal that order.
Does a disallowed deduction mean a penalty?
No. The page says no penalty applies to a disallowed exemption or deduction unless it is proved that you knew the claim was wrong.
Should I revise my return if I find an error?
Yes, and do it early. Correcting before a notice arrives shows good faith. Pay the extra tax when you revise.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on 13 October 2026, Pakistan time. We read FBR's page for section 182 of the Income Tax Ordinance. The copy we read was stamped 23 June 2026, so a change made by the Finance Act 2026 could be missing. The reports of 12 October about FBR action on false returns could not be matched to an FBR notice. We did not read the prosecution provisions, which are separate from these penalties. This page is general information, not legal advice.
About the author
Public Services and Education Journalist
Fajr Riaz is a journalist and content writer at Pakistan Era, based in Lahore. She covers the questions people meet in everyday life in Pakistan: how a public service works, what a change in the rules means, and where to find a reliable answer.