How to Reply to an FBR Section 122 Notice to Amend Your Tax Assessment
A section 122 notice proposes to amend your FBR assessment. See the five year limit, what FBR must have, your right to a hearing and how to reply and appeal.
Short answer: A section 122 notice means the Commissioner is thinking of changing your assessment. The law says FBR cannot amend it without giving you a chance to be heard, only within five years, and only on audit or definite information. After the show cause notice, the order is due within one year, extendable by up to 90 days.
A trader files his return, pays his tax and hears nothing for two years. Then a notice arrives saying his declared sales look low against bank records. He has a date to reply by and no idea what the section means. The notice is not a bill. It is a warning that one may follow, and the reply is where most cases are won or lost.
We read sections 120, 122 and 127 of the Income Tax Ordinance, 2001, as amended up to 30 June 2026, on FBR's own website on 12 October 2026. We did not see any individual notice, so the dates in your own notice are the ones that count. This is a plain reading, not legal advice.
Section 122 lets FBR amend a return it has treated as final
When you file a return, section 120 treats it as an assessment order. Section 122(1) lets the Commissioner amend that order later by making alterations or additions. A notice under this section is the first step. It is called a show cause notice because you must show cause why it should not be changed.
The notice usually states why FBR thinks income was missed or tax was too low. Read that part three times. Your reply must answer the reason given, not a general worry. If the notice names a bank deposit, bring the deposit slip and the source. If it names a sales figure, bring the invoices.
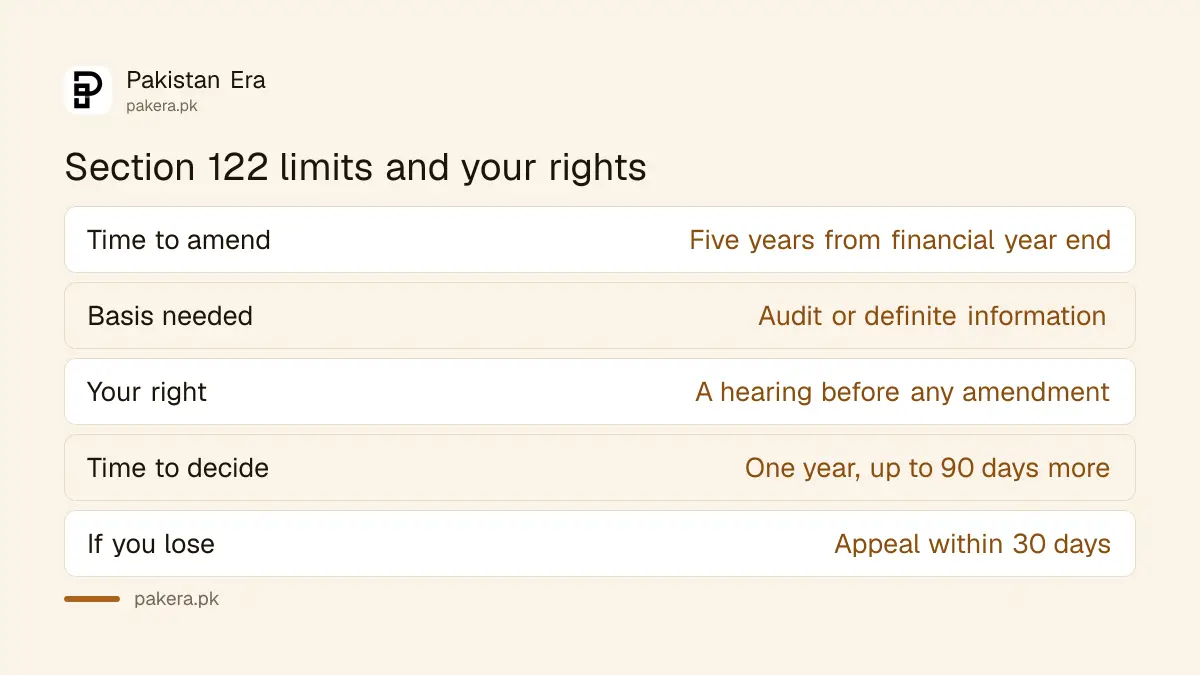
| Item | What section 122 says |
|---|---|
| Time limit to amend | Five years from the end of the financial year of the assessment order |
| Basis needed | Audit or definite information, under section 122(5) |
| Your right | An opportunity of being heard, under section 122(9) |
| Time to decide | One year from the show cause notice, extendable by up to 90 days |
| Next step if you lose | Appeal within 30 days under section 127 |
FBR needs audit or definite information to amend
Section 122(5) says an assessment can be amended only where, on the basis of audit or definite information, the Commissioner is satisfied that income escaped assessment, total income was under-assessed or taxed at too low a rate, relief or refund was excessive, or an amount was wrongly classified.
Section 122(8) explains "definite information". It includes information on your sales or purchases, your receipts from services, and your acquisition or sale of money, assets or investments, and your spending. In practice this is bank data, third party data and withholding data. That is why a match between your return and what others reported matters.
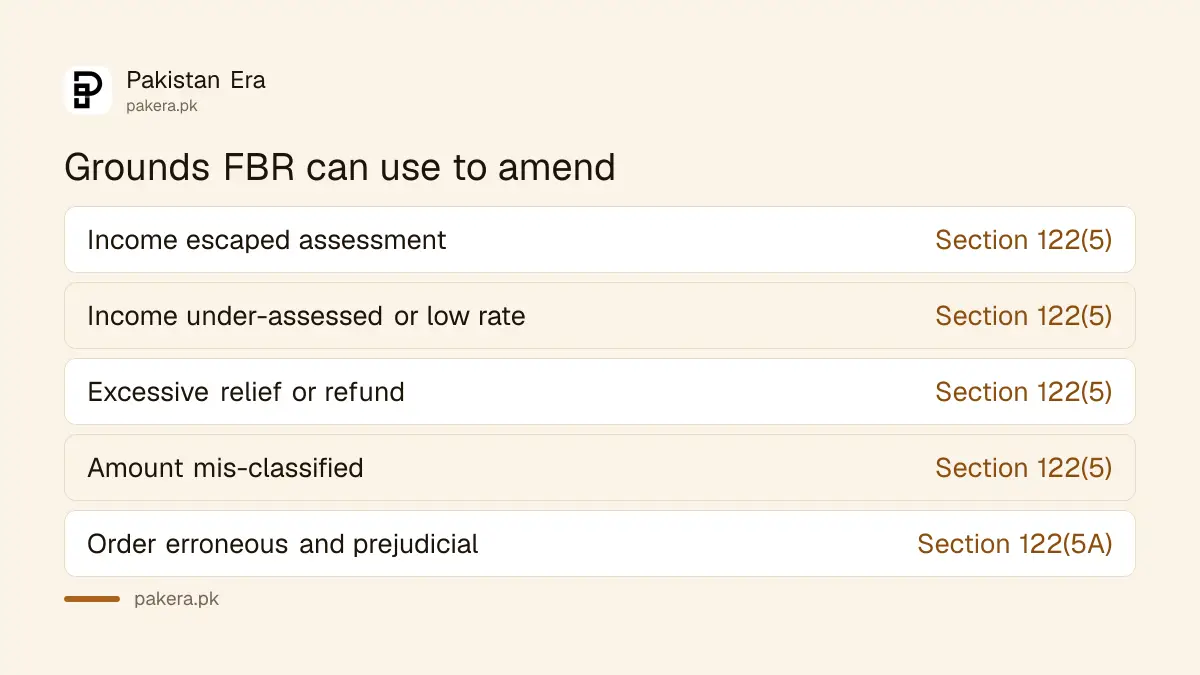
Section 122(5A) is a separate power. The Commissioner can amend an order he considers erroneous and prejudicial to the interest of revenue. That is a narrower ground, and the same hearing and time limits apply.
The five year clock starts at the end of the financial year
Section 122(2) says an order cannot be amended after five years from the end of the financial year in which the assessment order was issued or treated as issued. A return filed in October 2026 is treated as assessed in the financial year ending 30 June 2027, so the five years run to 30 June 2032.
Section 122(4) adds a rule for repeat amendments. If an order has already been amended, FBR may amend it again within the later of five years from the original order or one year from the amended order. So the first amendment does not always end the clock.
If a notice arrives well outside these limits, say so in your reply and attach the dates. That is a legal point, and a strong one. Do not rely on it alone, and answer the facts as well.
How to reply to the notice
Reply by the date in the notice, in writing, point by point, with documents. Keep a copy and the proof of delivery. Do not ignore it. If no one answers, the Commissioner can still decide on the information FBR already holds.
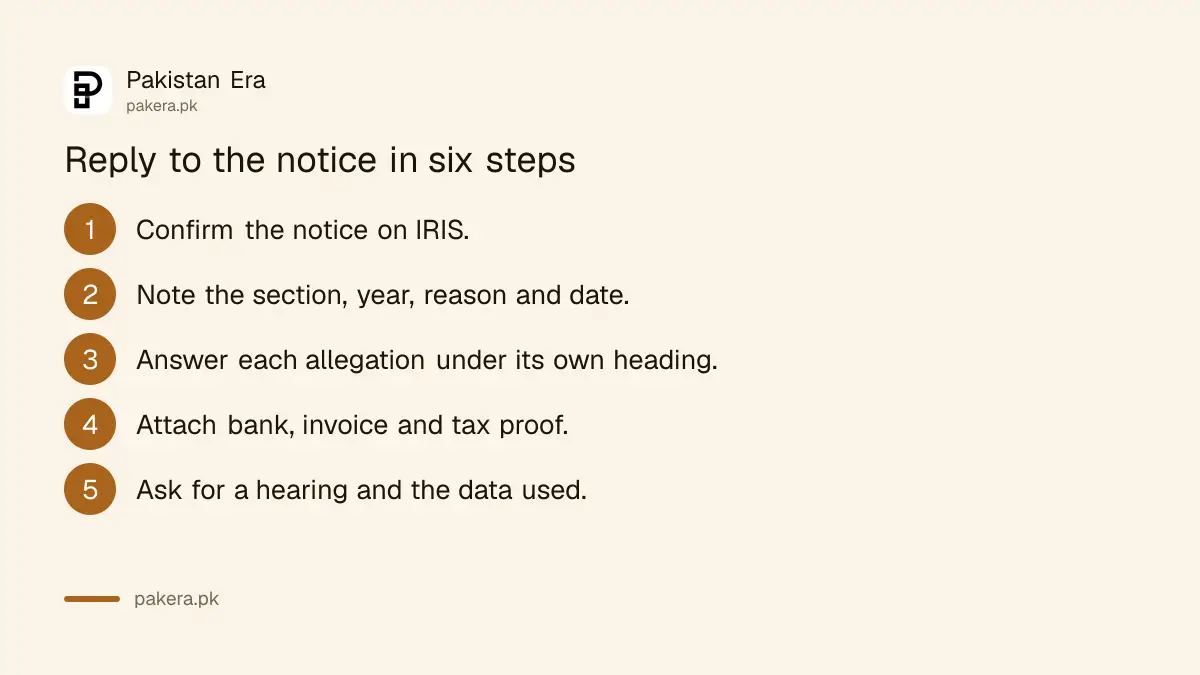
- Confirm the notice is real by logging in to IRIS rather than clicking a link or number inside it.
- Note the section, the tax year, the reason given and the reply date.
- Write each allegation as a heading and answer it under that heading.
- Attach the proof: bank statements, invoices, sale deeds, withholding certificates, wealth statement.
- Ask for a hearing date in writing and ask for the data FBR relied on.
- Send the reply early, by IRIS or by a method that gives a dated receipt, and keep the proof.
Check the notice before you act. Our guide on checking that an FBR notice or email is real shows what to look for. If your own mistake is the problem, a revised return under section 114(6) may be the cleaner path, but only if the law still allows one for that year.
What the amended order must contain and what follows
Section 122(6) says the amended assessment order must state the amended taxable income, the amended tax due, the tax already paid, and the time, place and manner of appealing. Section 122(9) says it must not be made without a hearing, and the proviso sets the one year limit.
Some time is left out of the one year count. That includes periods under a stay order, alternative dispute resolution, agreed assessment proceedings, and adjournments taken by the taxpayer, up to 60 days. So an order can lawfully arrive more than a year after the notice if you asked for time.
If the order goes against you, the appeal route is under section 127. We explain the 30 day limit, the fee and the condition on prior payment in how to appeal an FBR income tax order. If the order has a plain arithmetic error, you can also ask FBR to rectify the mistake before or alongside an appeal.
Common questions
Is a section 122 notice a demand for tax?
No. It is a show cause notice that proposes a change. The tax becomes payable only after an amended assessment order is issued and a notice of demand is served.
How far back can FBR go?
Five years from the end of the financial year in which the original assessment order was issued or treated as issued, under section 122(2). Repeat amendments follow the rule in section 122(4).
Does FBR have to hear me?
Yes. Section 122(9) says no assessment shall be amended unless the taxpayer has been given an opportunity of being heard. Ask for the hearing date in writing.
How long does FBR have to decide?
One year from the show cause notice, which can be extended for recorded reasons by no more than 90 days. Stays, ADR and some adjournments are excluded from that count.
What if I ignore the notice?
The Commissioner can decide on the information held. An order made without your reply is harder to undo, so always reply, even if only to ask for documents or for more time.
Can I appeal an amended assessment?
Yes, under section 127(1), within 30 days of service of the notice of demand. You must also have paid the tax due under section 137(1) first.
How we verified this
What we checked, where we read it, and what we could not confirm.
We read sections 120, 122, 127 and 137 of the Income Tax Ordinance, 2001, as amended up to 30 June 2026, at fbr.gov.pk on 12 October 2026. We did not read any individual notice or the Income Tax Rules. The proviso to section 122(9) was substituted by the Finance Act 2025, and later changes may apply, so check the latest text.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.