How to Reply to an FBR Section 111 Notice on Unexplained Income or Assets in Pakistan
An FBR section 111 notice taxes any bank credit, asset or spending you cannot explain. See the Rs 5 million remittance rule and how to reply through IRIS.
A section 111 notice asks you to explain the nature and source of a bank credit, an investment, an asset or spending. Reply through IRIS by the date on the notice with documents that trace the money to a declared source; anything you cannot explain is added to your income as "Income from Other Sources" and taxed. Foreign remittance up to Rs 5 million a tax year through a bank is outside the section, and agricultural income is accepted to the extent of the provincial agricultural tax you paid.
Since 15 October 2026 these proceedings run through the National Faceless Centre, so the notice carries a DIN and the reply goes through your IRIS account. We read section 111 of the Income Tax Ordinance, 2001 and rule 236 of the Income Tax Rules on the FBR website on 19 October 2026.
Section 111 covers four things: credits, investments, spending and suppressed sales
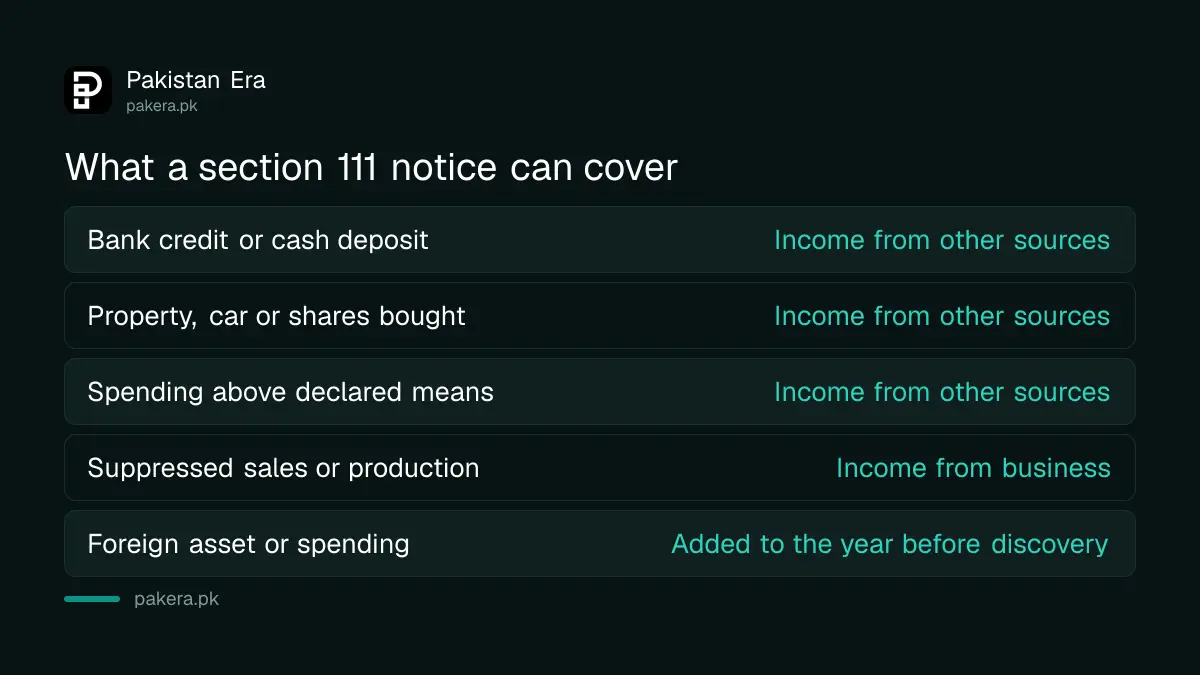
Sub-section (1) lists what the Commissioner can question: an amount credited in your books, an investment or ownership of money or a valuable article, expenditure you incurred, and concealed income or suppressed production, sales or receipts. If you offer no explanation of the nature and source, or the explanation is not satisfactory in the Commissioner's opinion, the unexplained part is included in your income.
Credits, investments, articles and spending go under "Income from Other Sources". Suppressed production, sales or receipts go under "Income from Business". Either way the addition is taxed at your normal rates, and penalty and default surcharge can follow.
| What the notice points to | Where the addition lands | Typical evidence |
|---|---|---|
| Bank credit or cash deposit | Income from Other Sources | Sale deed, salary slips, gift deed, loan agreement, earlier wealth statement |
| Property, car or shares bought | Income from Other Sources | Payment trail from a declared bank account, 236K or 231B challans |
| Spending above declared means | Income from Other Sources | Household expense working, spouse or family contributions already declared |
| Sales or production understated | Income from Business | Sales tax returns, stock records, utility bills matching output |
| Foreign asset or spending | Year before discovery | Section 116A statement, remittance certificates, foreign bank statements |
Remittance up to Rs 5 million and agricultural income have fixed protection
Sub-section (4) says sub-section (1) does not apply to foreign exchange remitted from outside Pakistan through normal banking channels, up to Rs 5 million in a tax year, encashed into rupees by a scheduled bank, where you produce the bank's certificate. An explanation added in 2022 counts money through exchange companies and money transfer operators as banking channel remittance. Above Rs 5 million the source abroad can be questioned, as explained in the guide to the Rs 5 million remittance limit.
A proviso to sub-section (1) protects farmers: where you explain a credit or asset from agricultural income, the explanation "shall be accepted" to the extent of agricultural income worked back from the agricultural income tax paid under provincial law. Without a provincial tax receipt that protection does not operate.
Gifts from relatives are not a listed exemption. They are explained by showing the donor's capacity and a banking transfer, which is the test set out in our guide on whether a gift is taxable.
The addition goes into a specific tax year, and that year matters for your reply
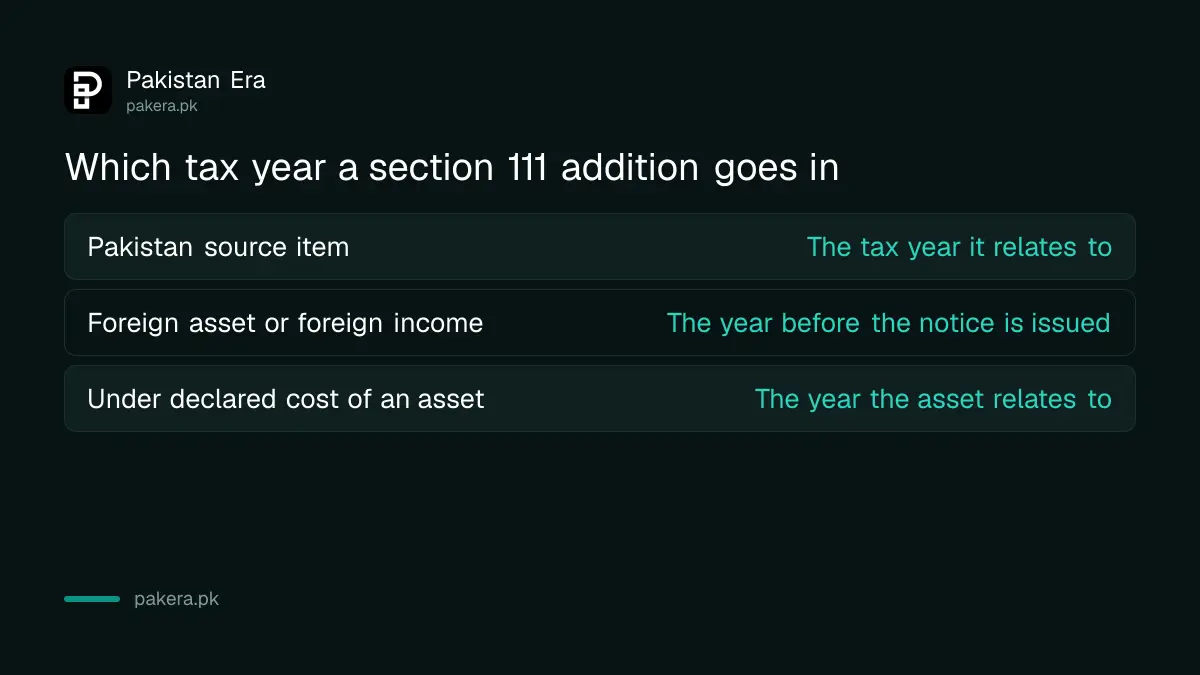
Sub-section (2) fixes the year. A Pakistan-source item is added to the tax year it relates to. A foreign asset, foreign spending or foreign-source concealed income is added to the tax year immediately before the year in which the Commissioner discovers it, and sub-section (2A) says the year of discovery is the year the notice is issued.
The explanation in sub-section (2) also protects you: if a foreign asset was bought in an earlier year and you explain it from sources of that earlier year, the explanation cannot be rejected only because the source does not match the year of inclusion. Sub-section (3) separately lets the Commissioner add the difference where the declared cost of an asset or amount of spending is below the reasonable cost.
Since 15 October 2026 the notice comes from the faceless centre with a DIN
Rule 236(1)(b) of Chapter XX of the Income Tax Rules puts "proceedings and orders under section 111" through the National Faceless Centre, and S.R.O. 1828(I)/2026 brought that chapter into force for every person or case from 15 October 2026. Rule 240(5) says the audit unit officer issues the section 111 notice, takes your response, and records findings for the assessment unit.
So the notice must carry a Digital Identification Number under rule 238, your reply must go through your IRIS account under rule 239, and any hearing is an e-hearing. A notice that arrives by WhatsApp or asks you to visit an officer does not match the rules; check it the way our guide to real and fake FBR notices describes.
How to put the reply together
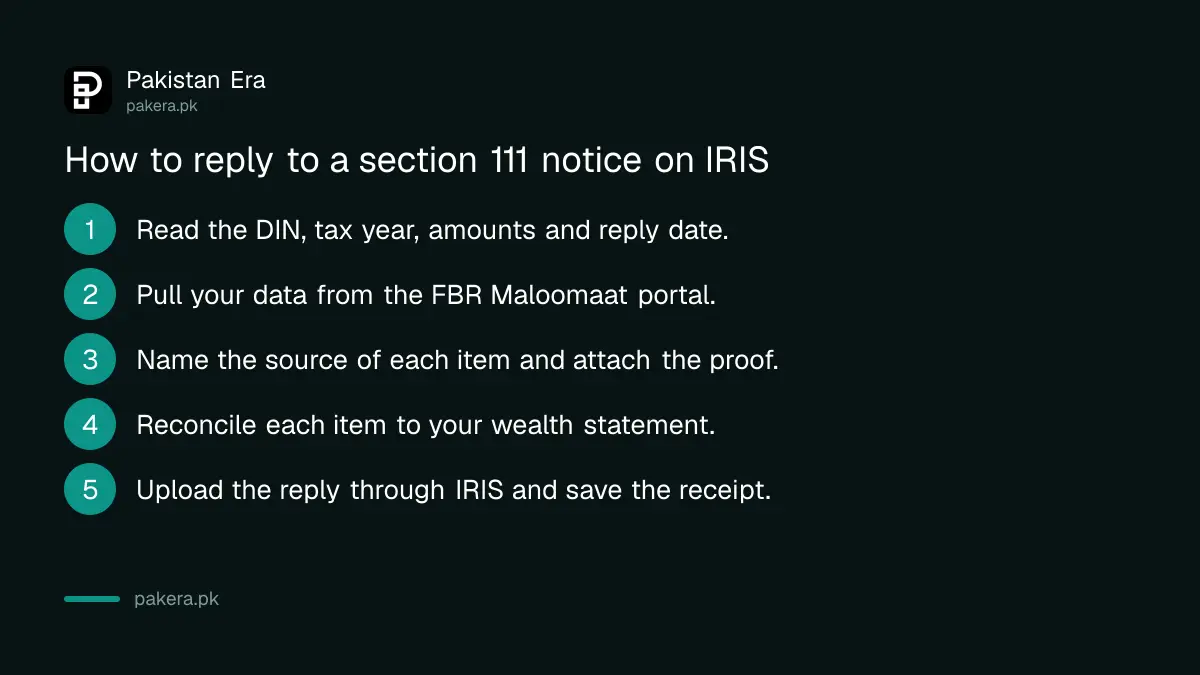
The reply has one job: to connect each questioned amount to a source that is already declared or already taxed. A reply that argues law without a paper trail usually fails at the Commissioner's opinion stage.
- Read the notice for the DIN, the tax year, the exact amounts and the reply date. Note each item separately.
- Pull the data FBR already holds on you from the Maloomaat portal; the notice is usually built from it.
- For each item, write one paragraph naming the source and attach the proof: bank statement lines, sale deed, inheritance papers, loan agreement, provincial agricultural tax receipt, remittance certificate.
- Reconcile the item to your wealth statement for that year. If the asset was declared and the reconciliation balanced, say so and quote the line.
- Where the amount was genuinely missed, say which part you accept; an unexplained balance is taxed only "to the extent it is not adequately explained".
- Upload the reply and attachments as searchable PDFs through IRIS before the date, and save the acknowledgement.
If an amended assessment follows, the next notice is usually under section 122, which has its own reply route in our guide to a section 122 show cause notice.
Common questions
What happens if I ignore a section 111 notice?
The questioned amount is treated as unexplained and added to your income for the relevant year, taxed at normal rates, with penalty and default surcharge possible. Silence is read as no explanation.
Is foreign remittance covered by section 111?
Not up to Rs 5 million a tax year through normal banking channels, encashed by a scheduled bank with a certificate. Above that the source can be questioned.
Can agricultural income explain a bank deposit?
Yes, to the extent of agricultural income worked back from the provincial agricultural income tax you paid. Without that tax receipt the proviso does not help.
Which year is the addition made in?
The year the amount relates to for Pakistan-source items; the year before discovery, meaning before the notice, for foreign assets or foreign-source income.
Do I reply on IRIS or at the tax office?
On IRIS. Since 15 October 2026 section 111 proceedings go through the National Faceless Centre, and rule 239 requires replies through your designated IRIS account.
Does a gift from my father need proof?
Yes. A gift is explained by the donor's declared capacity and a bank transfer. A cash gift with no trail is hard to sustain.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 19 October 2026. We read section 111 in FBR's consolidated Income Tax Ordinance, 2001 amended up to 30 June 2026, rules 236 to 240 in S.R.O. 1665(I)/2026 and the start notification S.R.O. 1828(I)/2026 on the FBR SRO pages. The table of evidence is our practical guidance, not an FBR list. We could not verify how the faceless centre treats section 111 notices issued before 15 October 2026, because the notification does not say.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.