Roshan Apna Ghar: Home Finance for Overseas Pakistanis, Up to 99% of Value
Roshan Apna Ghar lets overseas Pakistanis with an RDA borrow up to 99% of a home's value for 3 to 25 years. See rates, banks, eligibility and how to apply.
Roshan Apna Ghar is the State Bank of Pakistan's home finance for overseas Pakistanis who hold a Roshan Digital Account. Banks lend up to 99% of the property value if you keep savings under lien, or up to 85% against a mortgage, for 3 to 25 years. The rate is 1 year KIBOR, plus 1.5 points without a lien. The minimum loan is Rs 500,000.
An engineer in Riyadh or a nurse in Manchester can buy a flat in Lahore without flying home. We read the State Bank's own Roshan Apna Ghar page and frequently asked questions on 6 October 2026, then checked what four banks print on their own pages.
Roshan Apna Ghar is still open to RDA holders in 2026
The State Bank's page is live and describes Roshan Apna Ghar as a current product. Any individual with a rupee Roshan Digital Account can apply. That means non-resident Pakistanis with a NICOP and Pakistan Origin Card holders living abroad. Holders of Naya Pakistan Certificates can use them as security too.
If you do not have the account yet, opening a Roshan Digital Account comes first. The State Bank asks banks to finish account checks within 48 hours for individuals. The same account also runs the Roshan Apni Car scheme for buying a car for family in Pakistan.
You can use the finance to buy a finished house or flat, buy a plot and build, build on land you own, or renovate. A property from a bank's pre-approved project list is approved faster.
Lien or mortgage: the two ways to borrow
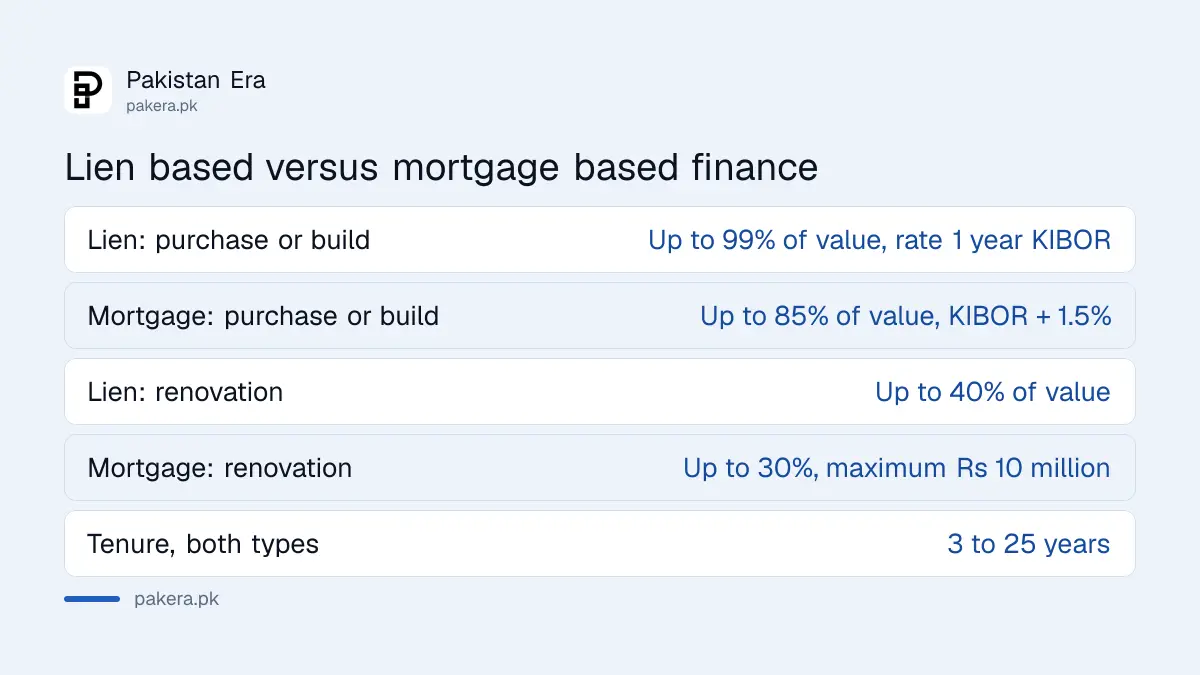
Roshan Apna Ghar has two versions. With a lien, you keep savings in your RDA or in Naya Pakistan Certificates frozen as security, and the bank lends up to 99%. Without a lien, the bank takes a mortgage on the property and lends up to 85%. The lien version is cheaper and fully remote.
| Feature | Lien based | Non-lien (mortgage) |
|---|---|---|
| Security | RDA deposits or Naya Pakistan Certificates frozen | Mortgage on the property |
| Purchase or construction | Up to 99% of value | Up to 85% of value |
| Renovation | Up to 40% of value | Up to 30%, maximum Rs 10 million |
| Variable rate | 1 year KIBOR | 1 year KIBOR + 1.5% |
| Fixed rate for 5 years | 5 year PKRV (PIB) | 5 year PKRV (PIB) + 1.5% |
| Income limit | No debt burden cap | Instalments up to 50% of income |
| Visit Pakistan? | No, a nominee completes the transfer | No, but a power of attorney is needed |
Banks can set tighter limits than the State Bank's ceilings. Bank Alfalah's Islamic Roshan Apna Ghar page lists non-lien finance at up to 80%, not 85%. UBL's page says up to 100% against property value. Read your own bank's page before you plan the down payment.
What the lien really means
A lien is not a down payment. HBL's page says the lien is kept "against their net financing amount". In plain words, you need savings in Pakistan roughly equal to the loan, and they stay frozen while you repay. If your savings in Pakistan are small, the mortgage version is the realistic one.
Rates are KIBOR based, not a fixed subsidy
Standard Roshan Apna Ghar finance is priced off market benchmarks. KIBOR is the rate Pakistani banks charge each other. PKRV for the 5 year government bond sets the fixed rate. A fixed rate holds for five years; after that you choose to stay fixed or move to variable. Variable rates reset once a year.
KIBOR follows the State Bank's policy rate closely, which was held at 11.5% on 14 September 2026. The way that flows into an instalment is set out in how the policy rate changes your loan EMI. We have not printed today's KIBOR because the State Bank's page did not show it to us.
The 1.5 point gap matters. On a Rs 17 million loan, 1.5 points is about Rs 255,000 of extra mark-up in the first year. That is our own arithmetic.
The subsidy tiers are no longer taking new cases
The State Bank's page still lists a government subsidy option from 3%. That subsidy is the Mera Pakistan Mera Ghar scheme, reported paused for new loans from 1 July 2022. We found no State Bank notice restarting it, so ask your bank first.
Who can apply and what banks ask for
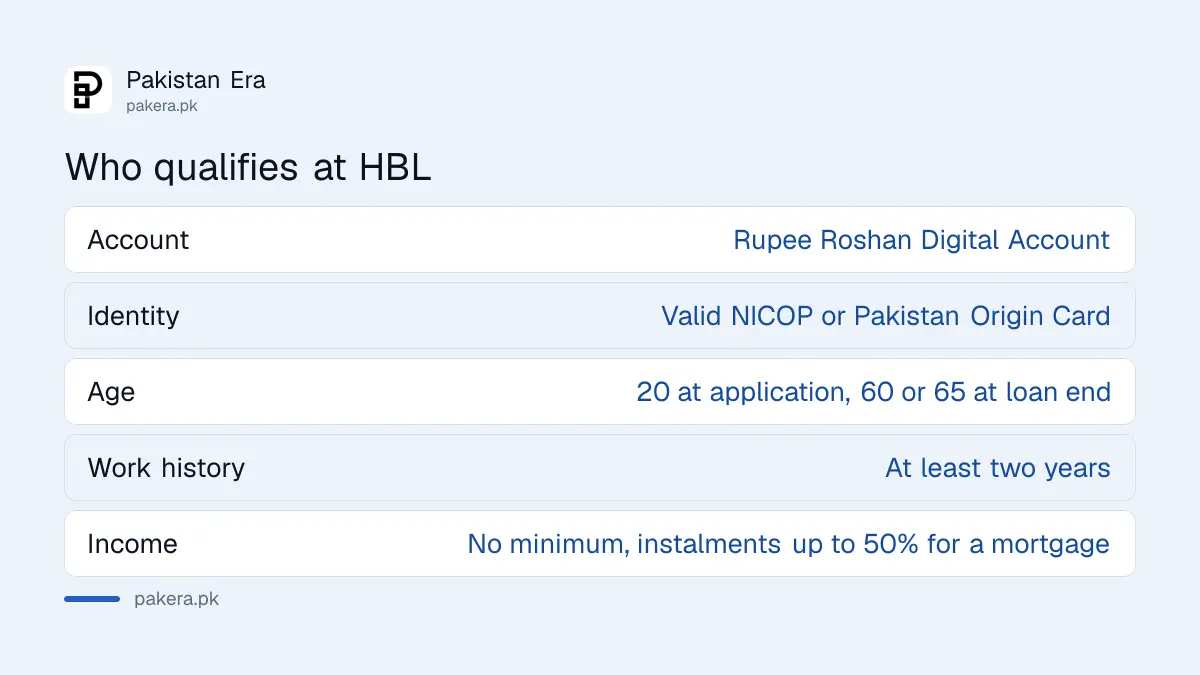
You must be a non-resident with a rupee RDA. The State Bank sets no minimum income. Bank rules add age and job history. HBL asks applicants to be at least 20, and no older than 60 at the end of the loan for salaried people or 65 for business people. It also wants two years of work history.
You can add another overseas Pakistani, such as a spouse, as co-borrower to club income. HBL and UBL count 100% of a spouse's income and 75% of another family member's. For the mortgage version, you also need a co-applicant living in Pakistan, usually a close relative, to handle the transfer and mortgage. For lien finance, a nominee in Pakistan, who can be a relative, lawyer or property dealer, does that job.
HBL asks a salaried applicant for NICOP, passport, visa, three months of bank statements and salary slips, an employer's certificate and a credit report from the country you live in. Expect a processing fee: HBL, UBL and Dubai Islamic Bank each list Rs 4,000 plus federal excise duty.
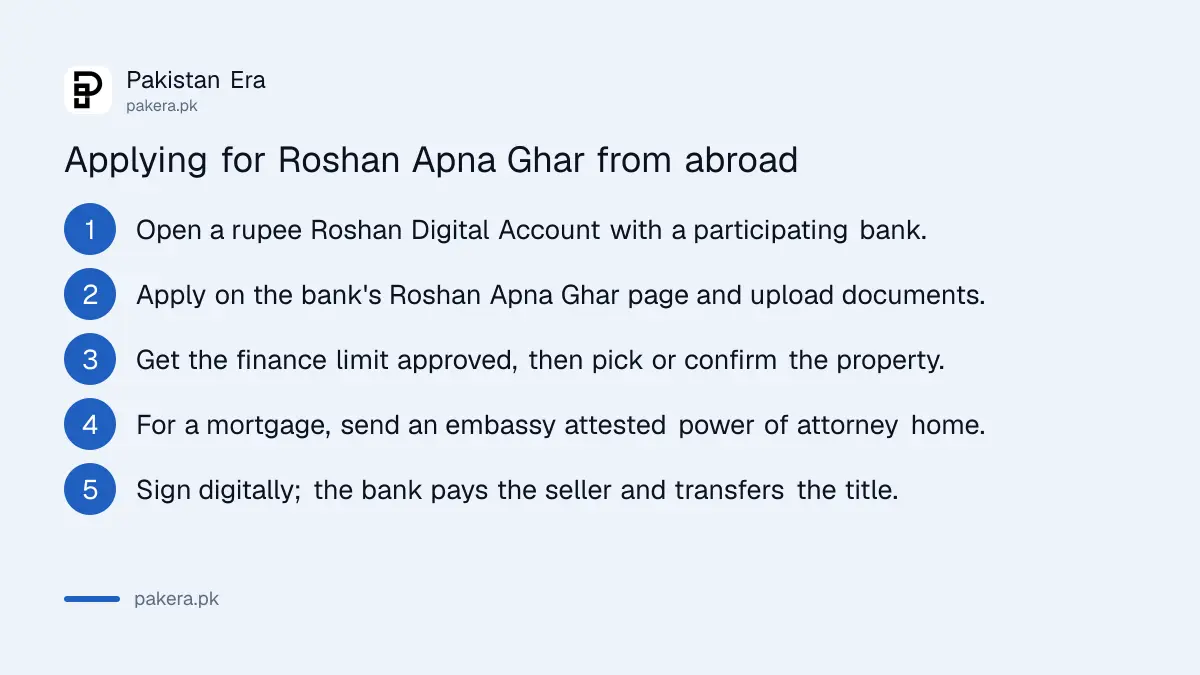
How to apply for Roshan Apna Ghar from abroad
You apply on your RDA bank's website, sign digitally and never need to visit.
- Open a rupee Roshan Digital Account with a participating bank, if you do not have one.
- Go to that bank's Roshan Apna Ghar page and fill in the online application.
- Choose lien or mortgage, fixed or variable, and conventional or Islamic.
- Upload your documents. A relationship manager contacts you.
- Get the finance limit approved, with or without a property chosen.
- The bank values the property and checks the title.
- For a mortgage, sign the special power of attorney the bank sends, get it attested at the Pakistan embassy or consulate, and send it to your attorney.
- Sign the finance documents digitally. The bank pays the seller and the property is transferred to your name.
Pakistan's missions attest these on priority for RDA holders. The general process is in getting a power of attorney from abroad.
Banks offering Roshan Apna Ghar and their terms
The State Bank lists 14 banks offering RDAs. We read four Roshan Apna Ghar pages directly. Each matches the State Bank's rate formula.
| Bank | Mode | What its own page says |
|---|---|---|
| HBL | Islamic | Rs 500,000 to Rs 100 million, 3 to 25 years, free property takaful |
| UBL | Conventional and Islamic | Up to 100% of value, 1% early exit fee in year one only |
| Bank Alfalah Islamic | Islamic | 99% with lien, 80% without, 3 to 25 years |
| Dubai Islamic Bank | Islamic | Musharakah cum ijarah, KIBOR with lien, KIBOR + 1.5% without |
Meezan Bank also offers it, but its page blocked our reader. Early repayment costs 1% of the outstanding amount in the first year under the State Bank's rules, and nothing after that. Property insurance up to the loan amount is free.
Try it on your own numbers: use our Home Loan Calculator to compare local home finance and the Apna Ghar scheme on your own figures.
Common questions
Can I get Roshan Apna Ghar without a Roshan Digital Account?
No. You need a rupee RDA. Pakistanis living in Pakistan should look at ordinary bank home loans instead.
What is the minimum and maximum loan?
The minimum is Rs 500,000. The State Bank sets no maximum, though HBL caps purchase finance at Rs 100 million.
Do I have to travel to Pakistan?
No. A nominee or attorney in Pakistan completes the transfer and any mortgage for you.
Can I send the sale money back abroad later?
Yes. Sell three years after the loan is repaid and all proceeds can go abroad. Sooner, the principal goes and any gain waits.
Is there an Islamic version of Roshan Apna Ghar?
Yes. The State Bank offers both, and HBL, Bank Alfalah, Meezan and Dubai Islamic Bank run Shariah compliant versions.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on 6 October 2026. We read the State Bank's Roshan Apna Ghar page and its FAQs, and the State Bank's Roshan Digital Account page for the bank list. We read the Roshan Apna Ghar pages of HBL, UBL, Bank Alfalah and Dubai Islamic Bank. Meezan Bank's page blocked us. The July 2022 pause of the subsidy scheme is from reports at the time, not a State Bank page we could open.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.