Wedding and Function Tax in Pakistan: 10% for Filers, and It Is Adjustable
Halls and marquees collect 10% advance tax on a function bill from filers and 20% from non-filers under 236CB. It is adjustable. How to claim it.
A marriage hall, marquee, hotel or restaurant in Pakistan must collect advance tax of 10 per cent of the total function bill from a filer, and 20 per cent from a person not on the Active Taxpayers' List. The law says this tax is adjustable, so a filer can set it against their income tax for the year.
Almost nobody does. The amount sits on the marquee bill, gets paid, and is never claimed. On a Rs 1,500,000 wedding bill, that is Rs 150,000 for a filer and Rs 300,000 for a non-filer.
Where the tax is collected
The section is wider than most people expect, both in the places it covers and the events it counts.
| Point | What the section says |
|---|---|
| Collected on | The total amount of the bill |
| Collected from | The person arranging or holding the function |
| Collected by | The owner, lease-holder, operator or manager of the venue |
| Venues covered | Marriage hall, marquee, hotel, restaurant, commercial lawn, club, community place |
| Nature of the tax | Adjustable |
The phrase "or any other place used for such purpose" appears too, so the list of venues is illustrative rather than closed.
A separate caterer does not avoid it
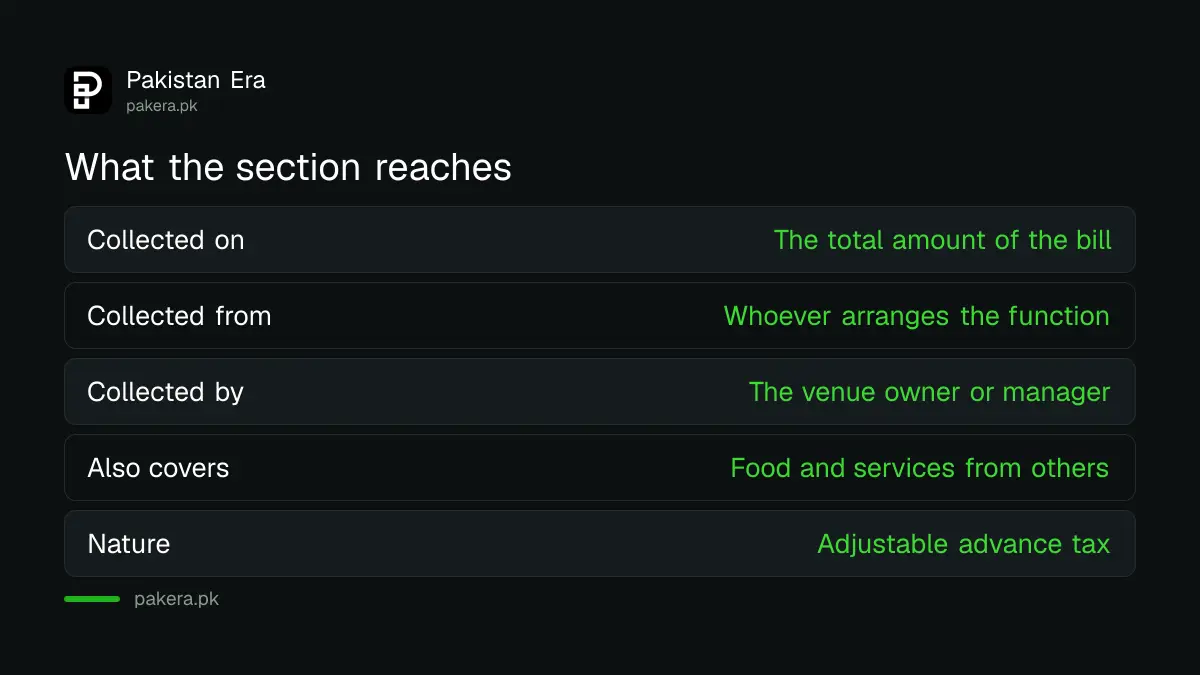
Subsection 2 closes the obvious gap. Where the food, service or any other facility is provided by somebody other than the venue, the prescribed person shall also collect advance tax on the payment for that food, service or facility, from the person arranging the function.
So booking the hall from one party and the catering from another does not split the bill out of the net. Budget for the tax on both.
It is not only weddings
The definition in subsection 4 is broad, and this catches businesses and organisers off guard.
A "function" includes any wedding related event, a seminar, a workshop, a session, an exhibition, a concert, a show, a party or any other gathering held for such purpose.
If you run training sessions, hold an annual exhibition, or organise a conference in a hotel, you are inside this section. The tax on those is adjustable in exactly the same way, and for a business it belongs in the same file as every other advance tax you claim.
How to actually claim it
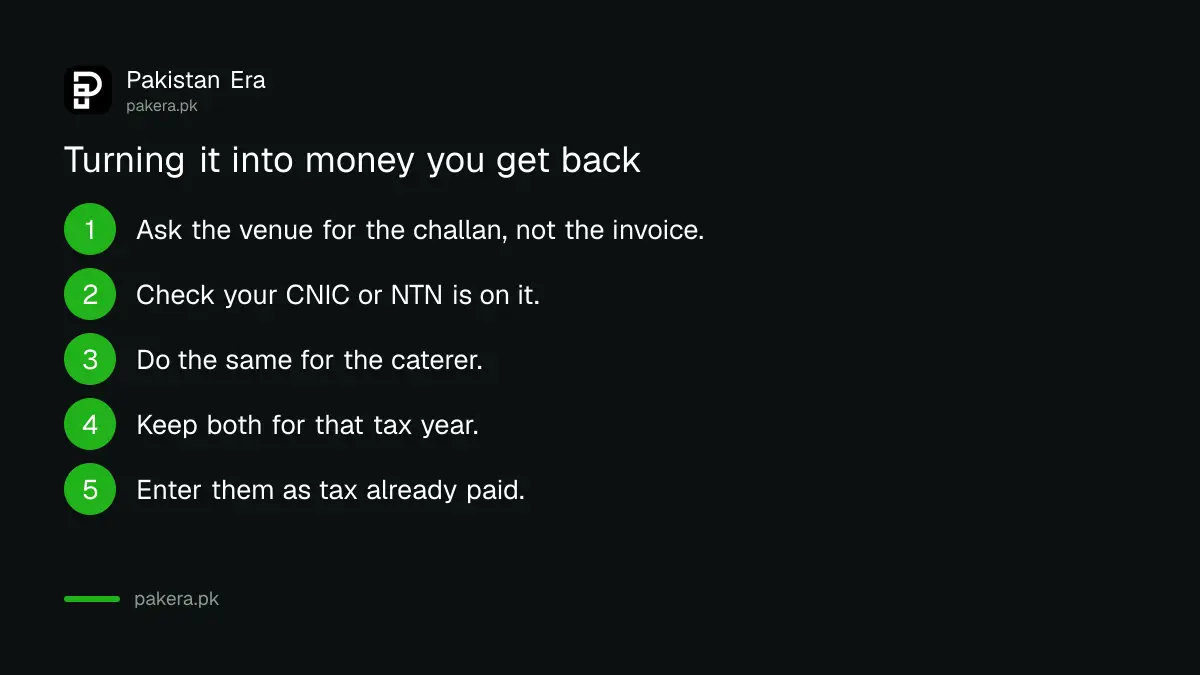
Subsection 3 states that the advance tax collected under subsections 1 and 2 shall be adjustable. Turning that into money depends entirely on paperwork.
- Ask the venue for the tax challan or a certificate, not just the invoice.
- Check your CNIC or NTN appears on it correctly.
- Do the same for the caterer or any separate service provider.
- Keep them with your records for that tax year.
- Enter the amounts as tax already paid when you file.
The failure is always the same one. If the venue deposits the tax without your identifier, the credit does not attach to you and nobody will chase it on your behalf. Ask at the time of payment, when you still have leverage, rather than months later.
Why filing decides whether you see it
Adjustable tax is only useful to somebody who files a return. If you never file, the tax on your wedding is simply a cost.
Being off the Active Taxpayer List makes it worse twice. You pay 20 per cent instead of 10, and refunds are not issued while a person is off the list. Our guide to the Rs 25,000 ATL surcharge for late filers sets out what getting back on costs.
For a family spending heavily on a wedding, the arithmetic is worth doing once. The tax collected across a hall, catering and services on a large function is not a small number, and it is recoverable.
The rate is 10 per cent, or 20 for a non-filer
Section 236CB points to Division XI of Part IV of the First Schedule for the rate. FBR's withholding rate card for 2026-27 sets it out plainly.
| Who arranges the function | Advance tax on the total bill |
|---|---|
| A person on the Active Taxpayers' List | 10% |
| A person not on the list | 20% |
The tax is on the total amount of the bill, and on the separate caterer's or decorator's bill too. Check your filer status before you pay the advance, because the rate depends on whether you are on the list. Our guide to checking your filer status takes a minute.
The section also allows conditions or limitations to be prescribed, so ask the venue what rate it is applying and on what amount, and keep its answer in writing.
The other taxes around a wedding
This is one of several. Provincial governments apply their own charges on marriage halls and catering in some cases, and those are separate from this federal advance tax.
In Punjab, provincial rules on how late a function may run and how many dishes it may serve are a separate matter, covered in our guide to Punjab's wedding hall rules.
Other places where adjustable advance tax is collected and rarely claimed include our guides to advance tax on auction purchases, the tax on a foreign domestic worker visa, the 15 per cent tax on mobile and internet bills and how salary tax is deducted.
Common questions
Can I get the wedding tax back?
Subsection 3 says the tax collected is adjustable, so it counts against your income tax for the year when you file.
Which venues does it cover?
Marriage halls, marquees, hotels, restaurants, commercial lawns, clubs, community places and any other place used for the purpose.
What if I hire my own caterer?
The section requires advance tax to be collected on the payment for food, service or facility provided by another person as well.
Does it apply to a seminar or a concert?
Yes. The definition of function includes seminars, workshops, sessions, exhibitions, concerts, shows and parties.
What is the tax rate on a wedding function in Pakistan?
10 per cent of the total bill for a person on the Active Taxpayers' List, and 20 per cent for a person not on it, according to FBR's 2026-27 rate card.
What do I need to claim it?
The challan or certificate showing the tax deposited against your CNIC or NTN.
How we verified this
What we checked and where we read it.
We read section 236CB of the Income Tax Ordinance, 2001, in the version amended up to 30 June 2026, and FBR's withholding rate card for 2026-27 on 8 November 2026, both on FBR's own download site.
Last checked 8 November 2026. We read section 236CB, covering collection on the total bill from the person arranging a function in a marriage hall, marquee, hotel, restaurant, commercial lawn, club, community place or other place used for the purpose, collection on food, service or facilities provided by another person in subsection 2, the statement in subsection 3 that the tax is adjustable, and the definitions of function and prescribed person in subsection 4, in the Income Tax Ordinance, 2001 amended up to 30 June 2026. The 10 and 20 per cent rates come from FBR's withholding tax rate card for tax year 2027. The Rs 25,000 surcharge for an individual is in the proviso to section 182A of the same Ordinance. The worked example is our arithmetic. Nothing here is tax advice.
About the author
Public Services and Education Journalist
Fajr Riaz is a journalist and content writer at Pakistan Era, based in Lahore. She covers the questions people meet in everyday life in Pakistan: how a public service works, what a change in the rules means, and where to find a reliable answer.