Daraz PayLater Cost in Pakistan: 16% for One Month, 30% for Three, APR up to 192%
Daraz PayLater is an Easypaisa loan costing 16% for one month or 30% over three, an APR of 192% or 120%, with a 5% late fee capped at Rs 800. See the real cost.
Daraz PayLater, the instalment option inside the Daraz app that is lent by Easypaisa Bank, costs 16 per cent of the price for a one month plan and 30 per cent for a three month plan, according to Easypaisa's own schedule of charges for October to December 2026. The same sheet states the annual percentage rate as 192 per cent for one month and 120 per cent for three months, and a late fee of 5 per cent per instalment, capped at Rs 800.
We read the charge in Easypaisa Bank's branchless banking schedule, downloaded from easypaisa.com.pk on 19 October 2026. The bank lists "Daraz Paylater via Daraz App" under its digital loans, next to Easycash and Buy Now Pay Later, so it is an Easypaisa loan even though you only see it at the Daraz checkout. That is the important point: a PayLater tick box at checkout is a bank loan at a stated APR, not a Daraz discount.
Daraz PayLater costs 16 per cent for one month and 30 per cent for three
The schedule gives two tenures. One month carries a total interest rate of 16 per cent, which is the whole charge on a single instalment. Three months carries 30 per cent in total, 10 per cent per instalment. Both rates are on the amount financed, and the sheet lists the APR as 192 and 120 per cent.
APR, or annual percentage rate, is what the charge would be if it ran for a full year. The one month plan's 192 per cent is simply 16 per cent times 12. The three month plan's 120 per cent is 30 per cent over a quarter, times 4. Easypaisa printed both on its own sheet, which is unusual among wallet lenders in Pakistan and makes comparison easy.
The markup is worked out per day of use. If you settle early, the sheet says markup already received for the unused period is charged as an early repayment fee. So early settlement stops the clock on future days but does not refund what has been taken.
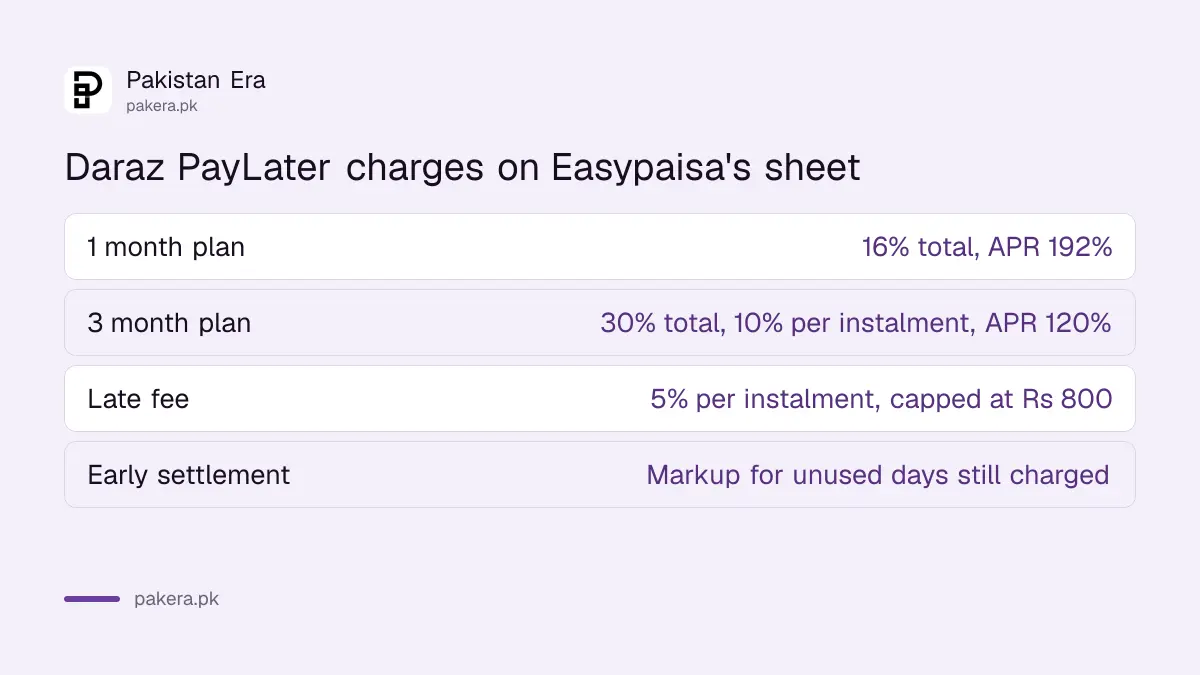
| Daraz PayLater plan | Total charge | Per instalment | APR on Easypaisa's sheet |
|---|---|---|---|
| 1 month | 16% | 16% | 192% |
| 3 months | 30% | 10% | 120% |
| Late fee | 5% of outstanding principal per instalment, capped at Rs 800 | ||
| Early settlement | Markup received for unused days is charged as an early repayment fee | ||
A Rs 20,000 phone costs Rs 23,200 in one month or Rs 26,000 over three
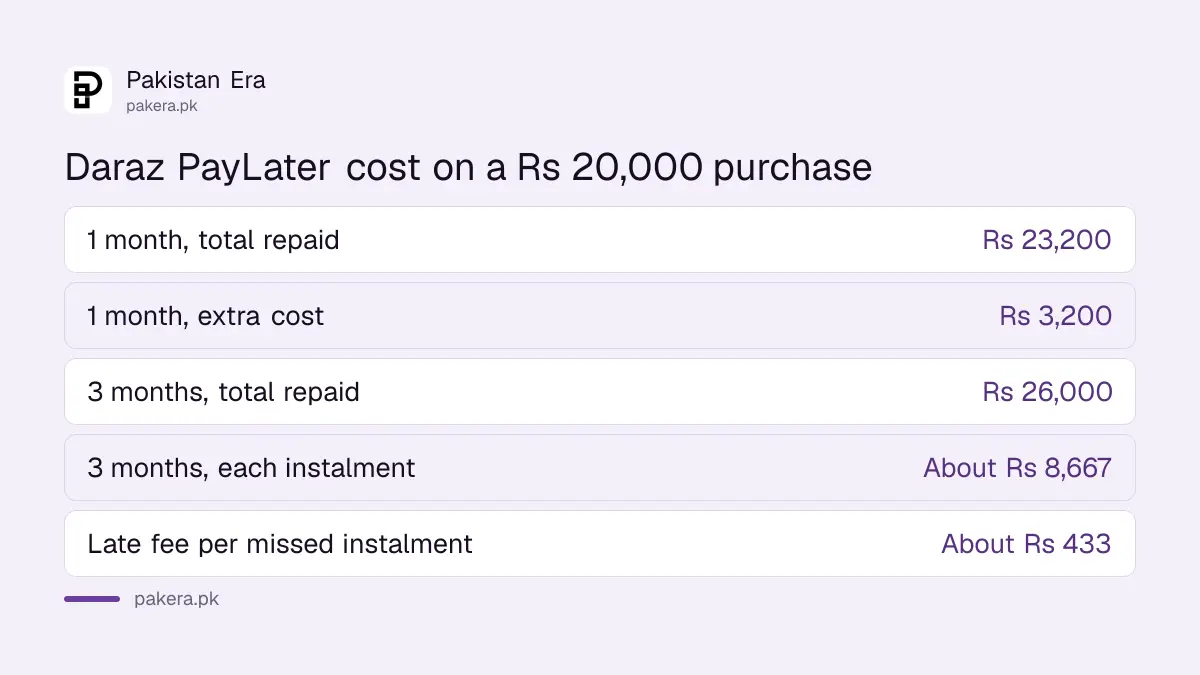
On the sheet's rates, a Rs 20,000 purchase costs Rs 3,200 extra on the one month plan, repaid as one instalment of Rs 23,200. The three month plan costs Rs 6,000 extra, repaid as three instalments of about Rs 8,667. Miss an instalment and up to Rs 433 is added each time.
These are our calculations from the percentages, since Easypaisa's sheet does not print rupee examples. The late fee on a Rs 8,667 instalment is 5 per cent, about Rs 433, well under the Rs 800 cap. The cap only matters on instalments above Rs 16,000, which means a financed amount above Rs 48,000 on the three month plan or Rs 16,000 on the one month plan.
Put another way, the three month plan costs almost twice the one month plan in rupees for the same phone, even though its APR is lower. The reason is time: you hold the bank's money for three times as long. If you can pay within a month, the one month plan is cheaper in cash. If you cannot, consider whether the phone can wait, because the true cost of buy now pay later in Pakistan rarely beats saving for four weeks.
Easypaisa's other instalment products cost less for short tenors
The same schedule prices Easypaisa's own Buy Now Pay Later at 10 per cent for 14 days and 20 per cent for 30 days, but only for QR payments, bills, packages and easyload. JazzCash's Yeylo charges 15 per cent across three instalments. Daraz PayLater's 16 per cent for a single month sits between them.
The products are not interchangeable. Easypaisa's in-app BNPL does not cover a Daraz order, and Yeylo lives in the JazzCash app. For a Daraz purchase specifically, the choice is PayLater, a bank credit card instalment plan, or paying in full. The guide to JazzCash Yeylo covers the rival wallet's limits, and the comparison of credit card instalment plans at nine banks shows that a card plan over 3 months is usually far cheaper than 30 per cent, if you hold a card.
| Product | Charge | Where it works |
|---|---|---|
| Daraz PayLater (Easypaisa) | 16% for 1 month, 30% for 3 months | Daraz app checkout |
| Easypaisa Buy Now Pay Later | 10% for 14 days, 20% for 30 days | QR payments, bills, packages, easyload in the Easypaisa app |
| JazzCash Yeylo | 15% over 3 instalments | JazzCash app |
What to check before you tick PayLater at the Daraz checkout
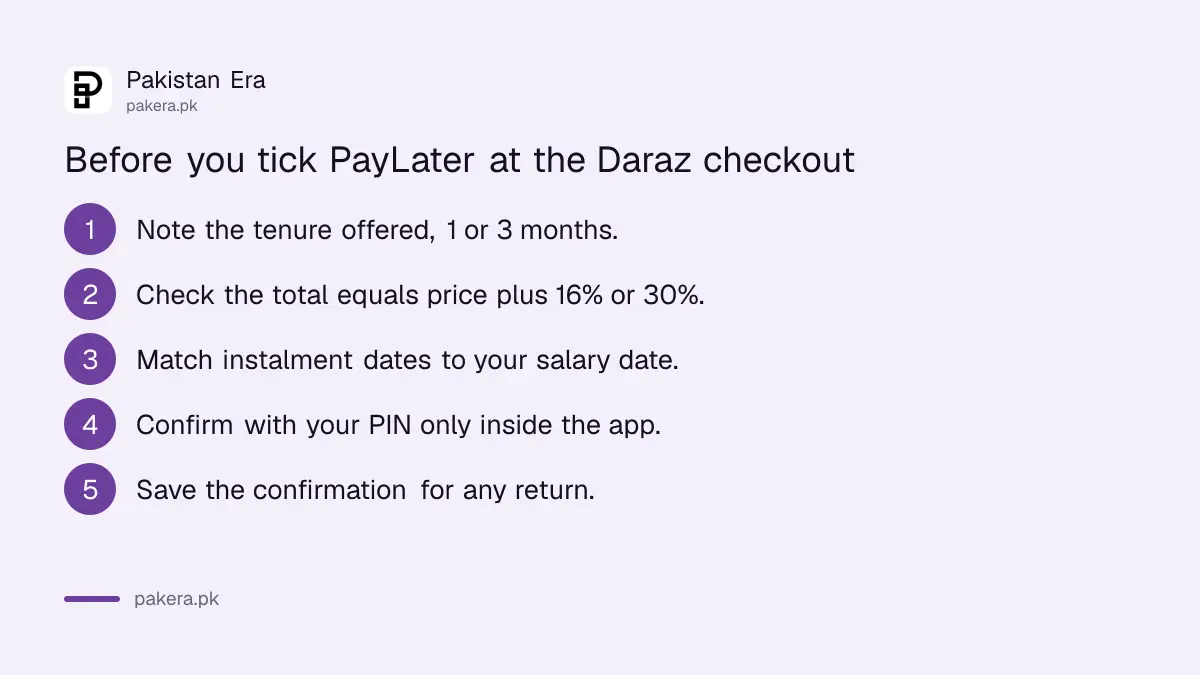
Read the total repayable amount and the due dates on the checkout screen, check that the charge matches 16 or 30 per cent, and make sure the instalment date falls after your salary date. Keep the order and loan confirmation, because a return or refund does not cancel the loan by itself.
- At checkout, select PayLater and note the tenure offered, one month or three.
- Compare the total shown with the price plus 16 or 30 per cent. Stop if it is higher than the schedule.
- Check the instalment dates against the day your money arrives.
- Confirm with your Easypaisa PIN only on the Daraz app or the Easypaisa app, never on a link sent by message.
- Save the confirmation. If you return the item, ask Daraz how the refund reaches the loan.
We could not read Daraz's own PayLater page, which loads only in a browser, so eligibility, the credit limit and how a returned order is settled against the loan are not confirmed here. Daraz's refund timelines for a returned item are in its return and refund rules. If an instalment is deducted that does not match the schedule, call Easypaisa on 042 111 003737 first, then use SBP's Sunwai portal, because a microfinance bank's customers do not go to the Banking Mohtasib.
Common questions about Daraz PayLater
Who is the lender behind Daraz PayLater?
Easypaisa Bank. Its schedule of charges for October to December 2026 lists "Daraz Paylater via Daraz App" among its digital loans.
What is the Daraz PayLater interest rate?
16 per cent of the financed amount for one month, or 30 per cent for three months, which Easypaisa states as an APR of 192 and 120 per cent.
What happens if I pay an instalment late?
A late fee of 5 per cent of the outstanding principal is added per instalment, capped at Rs 800.
Do I get the interest back if I repay early?
No. Easypaisa's sheet says markup received for unused days is charged as an early repayment fee. Early settlement only stops future days.
Is PayLater cheaper than Easypaisa's own Buy Now Pay Later?
No. Easypaisa's in-app BNPL costs 10 per cent for 14 days or 20 per cent for 30 days, but it does not cover Daraz orders.
How much can I finance on PayLater?
Easypaisa's schedule does not state a limit and we could not read Daraz's page, so the limit is not confirmed. The amount offered appears at checkout.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 19 October 2026. The 16 and 30 per cent rates, the APRs, the late fee cap and the early repayment rule come from Easypaisa Bank's schedule of bank charges for branchless banking, October to December 2026, read on 19 October 2026. The Easypaisa BNPL rates come from the same sheet. The rupee examples are our own arithmetic. We could not read Daraz's PayLater page at daraz.pk/paylater, which showed only its login screen, so eligibility, credit limits and refund handling are not verified, and we did not take a PayLater loan ourselves.
About the author
Technology Journalist & Multimedia Producer
Ahmad Ali is a technology journalist and multimedia producer at Pakistan Era, joining the team in October 2026. He covers consumer technology and digital life for Pakistani readers, combining research with hands-on product testing.