FBR's Algorithmic Settlement Offer in Pakistan: How the 10 Day Window on IRIS Works
Section 134B lets FBR send a computer settlement offer on IRIS. You have ten days to accept, pay and revise your return, with no separate penalty. What to know.
Short answer: Under the Finance Act 2026, FBR can send a taxpayer a computer-made settlement offer on IRIS. You then have ten days to accept it, pay the amount and revise your return. If you accept, the issue in the notice ends and no separate penalty or default surcharge is charged. We found no sign that FBR has switched the system on yet.
This is the "algorithmic settlement mechanism" in the new section 134B of the Income Tax Ordinance, 2001. It is meant for taxpayers who got an audit or discrepancy notice and would rather settle than argue.
We read FBR's own explanation, Circular No. 02 of 2026-27 dated 8 September 2026, on the FBR website on 13 October 2026. The circular describes the law. We found no notification on the FBR site that sets up the mechanism, so this page tells you what to expect, not what to click today.
An algorithm makes the offer, not an officer
Section 134B lets FBR run a digital system that works out a settlement offer. The circular says the offer is based on factors such as the stage of the proceedings, the taxpayer's history and the character of the discrepancy, plus any other basis the Board thinks relevant.
The mechanism can be used at any stage before an assessment or an amended assessment under sections 121, 122 or 122E. It works through a revised return under section 114(6), so the settlement shows up as a corrected return.
It sits beside the new faceless audit regime. Our note on FBR's National Faceless Centre explains how notices are issued, and how replies go through the IRIS account.
You have ten days to accept on IRIS
Within ten days of the offer, the taxpayer may accept it on IRIS, deposit the settlement amount with the revised return, and revise the relevant return of income. The circular does not say that an extension is possible. Treat ten days as a hard limit.
| Step | What the circular says |
|---|---|
| Offer | The mechanism calculates and presents a settlement offer |
| Time to accept | Ten days |
| Where | On IRIS |
| Payment | Deposit the settlement amount with the revised return |
| Effect | The issues in the notice stand abated |
| Penalty | No separate penalty or default surcharge |
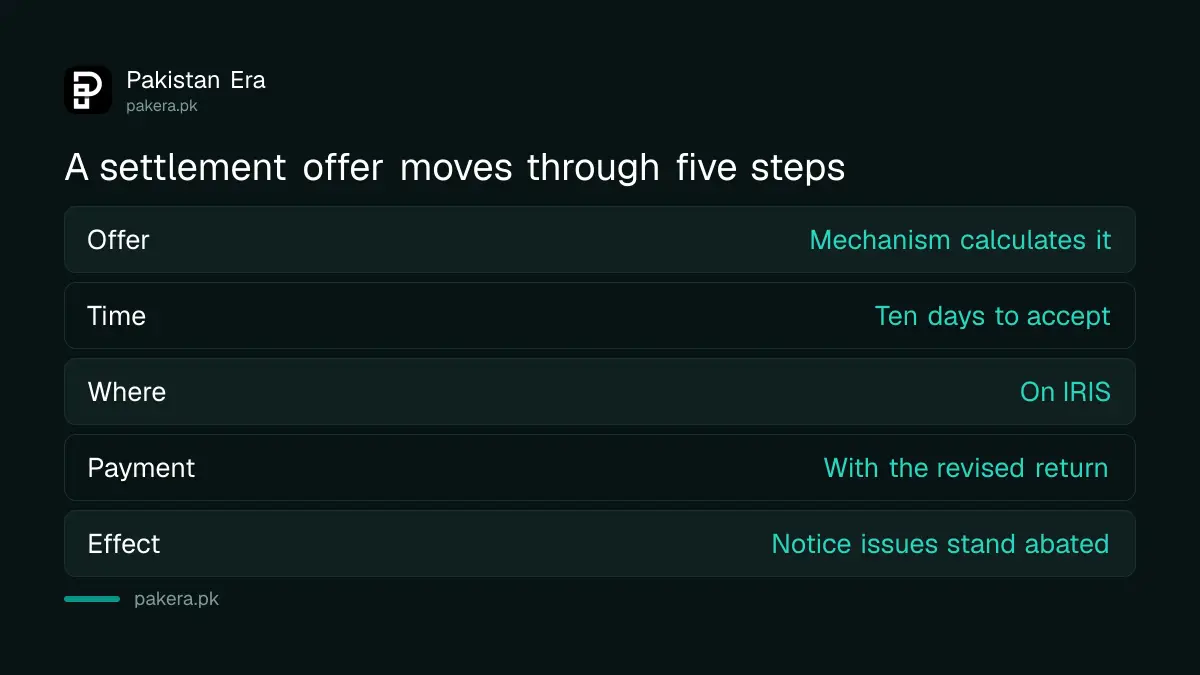
A deposit made in time is not enough on its own. The circular ties acceptance to revising the return, so a payment without the revised return does not settle the issue.
What settling does and does not end
On acceptance, the issues in the notice of selection for audit, a notice under section 111, an audit report under section 177(6) or a notice under section 122(9) stand abated. That means they are closed.
The circular is clear on a limit: acceptance does not stop proceedings on any other issue or any other tax year. A settlement for 2025 does not settle 2026.
The new sub-section (6B) of section 114 adds that the Commissioner's approval is not required for such a revised return, and no separate penalty or default surcharge is payable. Compare this with a normal revision, explained in our guide to revising an income tax return.
Why a taxpayer might accept, and why not
Accepting ends the dispute quickly. You avoid a long audit, and there is no separate penalty. That suits a taxpayer who knows the discrepancy is real and the amount is fair.
Not accepting keeps your right to explain. If your records show the discrepancy is wrong, the offer may charge you more than you owe. Compare the amount with your own working first, and reply to the notice with evidence if the numbers do not match. The circular does not say that declining an offer counts against you.
How to prepare before an offer arrives
You cannot apply for an offer. FBR's system produces it. You can make sure you are ready to answer it inside ten days.
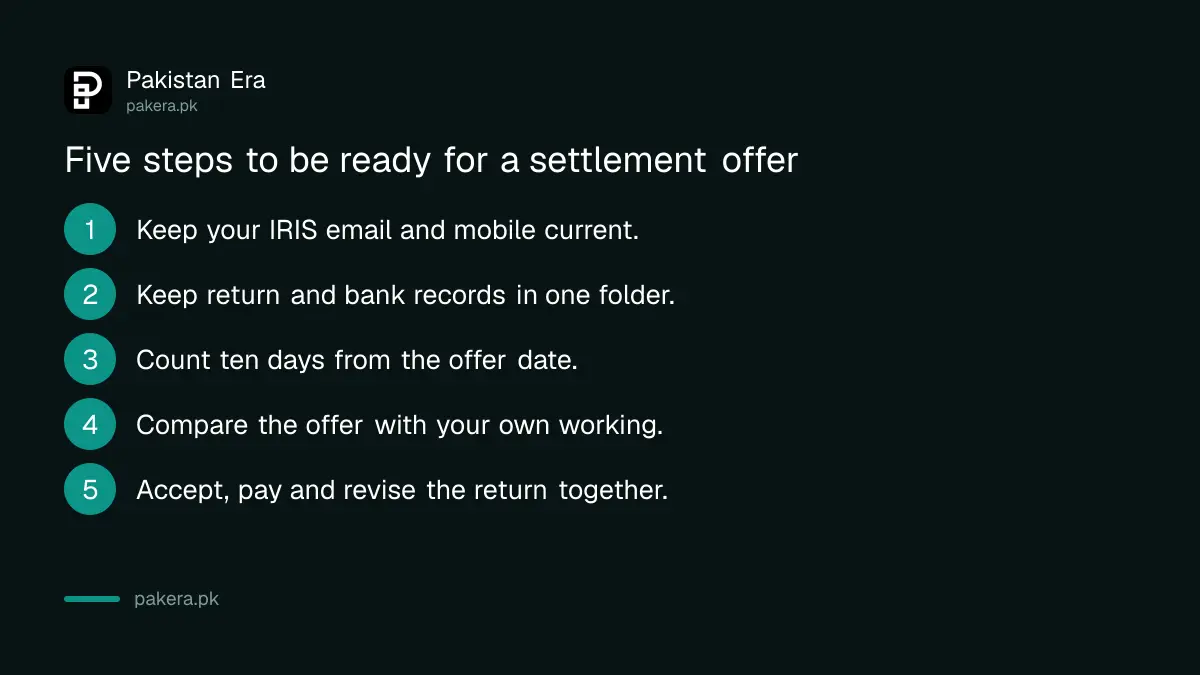
- Make sure your email and mobile number on IRIS are current, so you see the notice.
- Keep your return, wealth statement and bank records together in one folder.
- When an offer arrives, note the date and count ten days from it.
- Compare the offer with your own working of the discrepancy before you pay.
- Accept on IRIS, pay through the PSID and file the revised return the same day.
For payment, see the guide to paying income tax with a PSID. If you disagree with the offer, a reply to an assessment notice has its own steps in the guide to replying to a section 122 notice.
Common questions
Is the algorithmic settlement system running now?
We found no notification that sets it up. The law allows the Board to establish it, and we have not seen FBR announce a start.
Do I have to accept the offer?
No. The circular says the taxpayer may accept. If you do not, the normal proceedings go on, and you can reply to the notice.
How long do I have to accept?
Ten days from the offer, according to the circular. Accept on IRIS and pay with the revised return.
Will I be charged a penalty if I accept?
Not a separate one. The circular says no separate penalty or default surcharge is payable on such a revised return.
Does acceptance close all my tax issues?
No. It closes only the issues in the notice. Other issues and other tax years can still be taken up.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on 13 October 2026, Pakistan time. We read FBR's Circular No. 02 of 2026-27 on the Finance Act 2026, item 2. Parts of the scanned circular text were unclear, so the list of factors behind the offer is read from context. We did not read the Finance Act itself, and we found no set-up notification or live offer screen.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.