Teachers and Researchers Lose the 25% Tax Reduction From Tax Year 2026 in Pakistan
The 25% tax reduction for full time teachers and researchers ended after tax year 2025, so the return due 31 October 2026 has no rebate line. See the cost.
The 25% tax reduction for full-time teachers and researchers does not apply to the tax year 2026 return due on 31 October 2026. Clause (3A) of Part III of the Second Schedule to the Income Tax Ordinance, 2001, which gave the reduction, says it "shall cease to have effect after tax year 2025". The Finance Act 2026 did not extend it, and FBR's circular on that Act does not mention it.
Thousands of university, college and school teachers claimed this each year, and a teacher who filed last year with the reduction will find the line gone this year. We read the Second Schedule in FBR's consolidated Ordinance, amended up to 30 June 2026, on 19 October 2026.
Clause (3A) gave 25% off the tax on salary and ended with tax year 2025
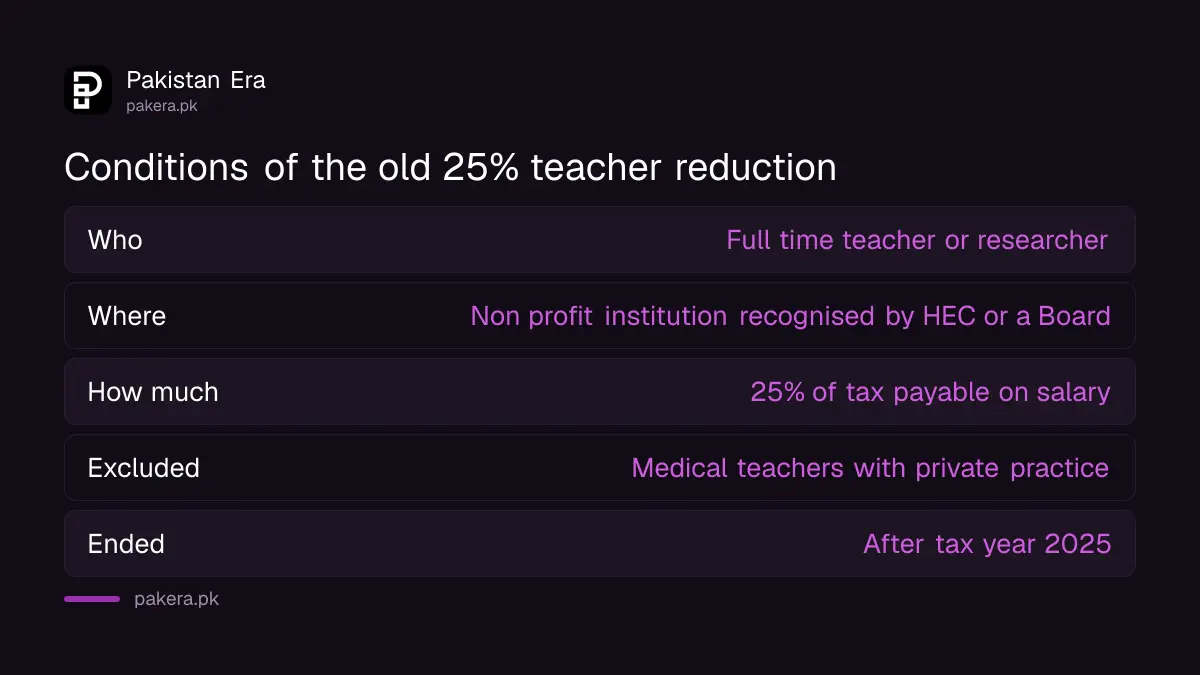
The clause read: the tax payable by a full-time teacher or a researcher, employed in a non-profit education or research institution duly recognised by the Higher Education Commission, a Board of Education or a university recognised by the HEC, including a government research institution, "shall be reduced by an amount equal to 25% of tax payable on his income from salary".
Two provisos limited it. It did not apply to teachers of the medical profession who derive income from private practice or receive a share of fees from patients. And it was deemed to have been in force from 1 July 2022 and to cease after tax year 2025.
The reduction was withdrawn in 2022 and restored for three years in 2025
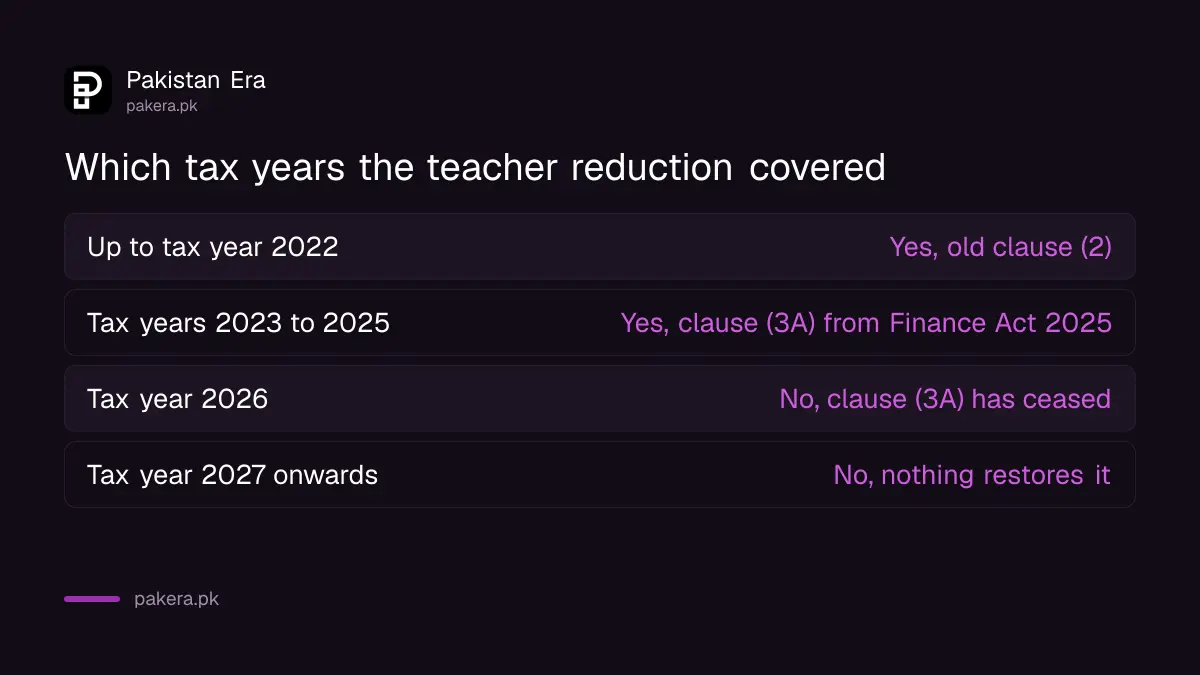
The clause has a stop-start history, which is why many teachers are unsure whether it exists. Clause (2) of Part III carried the reduction for years; the Finance Act 2022 omitted it. The Finance Act 2025 then inserted clause (3A) with retrospective effect from 1 July 2022, so that tax years 2023, 2024 and 2025 were covered, but with the sunset date built in.
| Tax year | Salary period | 25% teacher reduction | Basis |
|---|---|---|---|
| 2022 and earlier | to 30 June 2022 | Yes | Clause (2), Part III, Second Schedule |
| 2023, 2024, 2025 | 1 July 2022 to 30 June 2025 | Yes | Clause (3A), inserted by Finance Act 2025 with retrospective effect |
| 2026 | 1 July 2025 to 30 June 2026 | No | Clause (3A) ceased after tax year 2025 |
| 2027 onwards | from 1 July 2026 | No | Nothing in the Finance Act 2026 restores it |
Whoever filed a return for tax year 2024 or 2025 without the reduction could, in principle, have revised to claim it once clause (3A) was inserted, because the clause reached back to July 2022. That window turns on the time limit for revising an income tax return, which is five years from the original filing, with the Commissioner's approval after 60 days.
What the loss means in rupees for a typical teacher
The reduction was 25% of the tax on salary, so the cost of losing it is a quarter of whatever tax your salary attracts. A lecturer whose salary tax for the year comes to Rs 120,000 paid Rs 90,000 with the reduction and pays Rs 120,000 without it, Rs 30,000 more. A professor at Rs 400,000 of salary tax loses Rs 100,000.
Those are our worked examples on the 25% rule, not FBR figures. Your own number is on the tax computation page of your return, where IRIS shows tax chargeable on salary before any reduction. The salary tax slabs set that figure, and an employer should already have deducted the full amount each month under section 149 during tax year 2026.
Employers should have stopped applying it from July 2025
Section 149 requires the employer to deduct tax on salary at the rates in force, after any reduction the employee is entitled to. For salary paid from 1 July 2025 there was no entitlement, so a correct payroll deducted 25% more than in 2024-25. A teacher whose employer kept applying the reduction will see the shortfall as tax payable when the return is filed, and should pay it with the return rather than wait for a notice.
The opposite can also happen. A university that stopped the reduction a year early, for salary paid between July 2024 and June 2025, over-deducted, and the employee's remedy was to claim the reduction in the tax year 2025 return and take the excess as a refund under the rules for an income tax refund claim.
How to file the tax year 2026 return as a teacher
The return itself is the ordinary salaried return. What changes is that the reduction line is no longer available, and anyone who copies last year's figures across will be wrong.
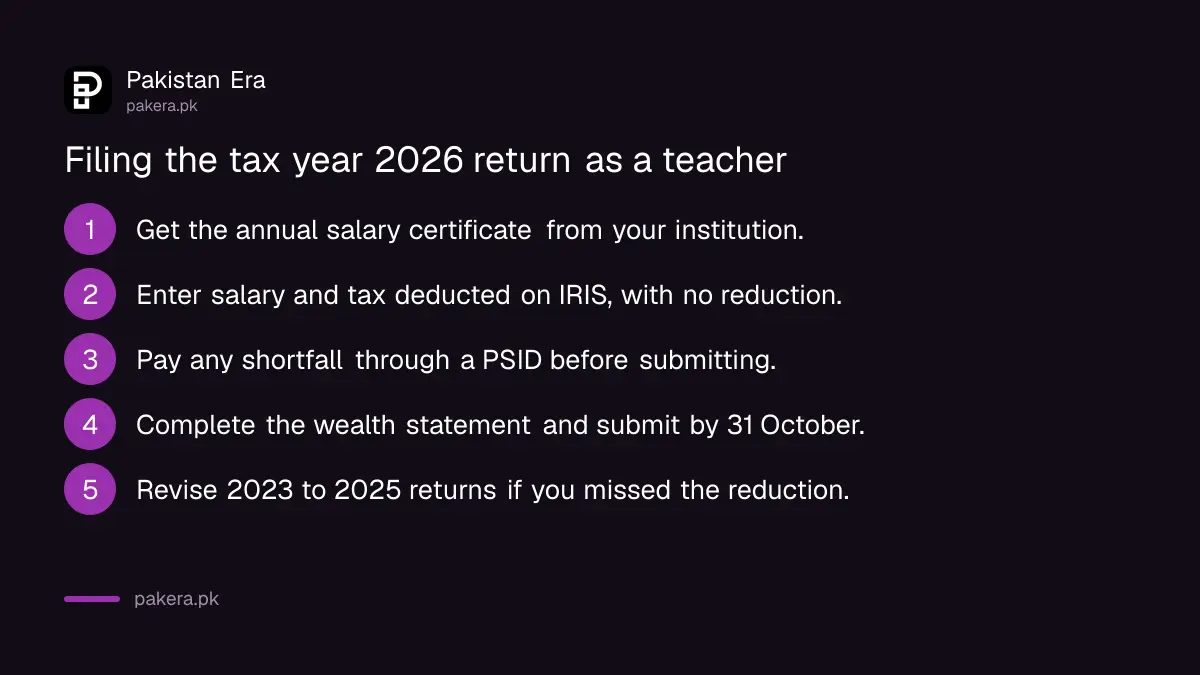
- Get the annual salary certificate from your institution showing gross salary and tax deducted under section 149 for 1 July 2025 to 30 June 2026.
- Enter salary and the tax deducted in the salary section of the IRIS return; do not enter any reduction under Part III of the Second Schedule.
- Compare the tax computed by IRIS with the tax deducted; pay any difference through a PSID before submitting.
- Complete the wealth statement and reconciliation as usual and submit by 31 October 2026.
- If your institution still applied the reduction in payroll, keep the salary slips, because the shortfall is yours to pay, not the employer's.
Teachers who missed the reduction for 2023 to 2025 and want to revise those returns should do so before the five-year window closes on each year.
Common questions
Can teachers claim the 25% tax rebate for tax year 2026?
No. Clause (3A) of Part III of the Second Schedule ceased to have effect after tax year 2025, and the Finance Act 2026 did not restore it.
Which years did the reduction cover?
Tax years up to 2022 under the old clause (2), and tax years 2023, 2024 and 2025 under clause (3A), which the Finance Act 2025 inserted with effect from 1 July 2022.
Who qualified?
A full-time teacher or researcher employed in a non-profit education or research institution recognised by the HEC or a Board of Education, or a university recognised by the HEC, including government research institutions. Medical teachers with private practice were excluded.
Can I still revise an earlier return to claim it?
Yes, for tax years 2023 to 2025, within the five-year revision window and subject to the Commissioner's approval after the first 60 days.
Did the Finance Act 2026 say anything about teachers?
No. FBR's Circular No. 02 of 2026-27, which explains the Finance Act 2026 income tax changes, does not mention the teacher or researcher reduction.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 19 October 2026. We read clause (3A) and the footnotes on the omitted clause (2) in Part III of the Second Schedule in FBR's consolidated Income Tax Ordinance, 2001 amended up to 30 June 2026, and FBR's Circular No. 02 of 2026-27 of 8 September 2026, on the FBR website. The rupee examples are our arithmetic. We could not verify whether the tax year 2026 return form on IRIS still shows a reduction field, because we did not open a live return.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.