Bank Asks for Income Proof? When a Self-Declaration Is Enough Under SBP Rules in Pakistan
SBP lets banks accept a signed self-declaration instead of income proof for low-risk, low-turnover customers such as students, farmers and housewives.
Short answer: Yes, in many cases. The State Bank of Pakistan (SBP) lets a bank accept a signed self-declaration instead of income papers when you are low risk, expect low turnover, and work in a job where papers are hard to get, such as daily wage labour, farming or studying. The bank cannot simply ask for more documents without a recorded reason.
A housewife opens an account to receive money from her son. A student wants a wallet for his scholarship. A farmer has no payslip, no tax return and no shop licence. The teller says, "Bring proof of income." Many people go home and give up. SBP's rules say the bank should look at a simpler option first.
We read SBP's updated Consolidated Customer Onboarding Framework and the March 2026 circular that amended it. This guide covers only what those pages say. We did not test any bank's counter, so we cannot say how every branch behaves.
SBP allows a self-declaration as proof of profession and income
The framework says a self-declaration "may be sufficient" as proof of profession and source of income for some customers. It applies to banks, microfinance banks, digital banks and wallet providers, so the rule covers a mobile wallet as well as a branch account.
The word "may" matters. The bank still decides, but it must use the framework's own tests. It cannot make a blanket rule that every customer must show a salary slip or a tax return.
All three conditions must be true together
The self-declaration route works only when the customer meets three conditions at once. The bank rates you as low risk, your expected turnover is low, and your work is of a kind where formal paper evidence is often not available.
- You fall in the "low risk" category under the bank's own customer risk profile model.
- Your expected account turnover is low, as the bank's due diligence assessment shows.
- Your profession is one where a formal document may not exist.
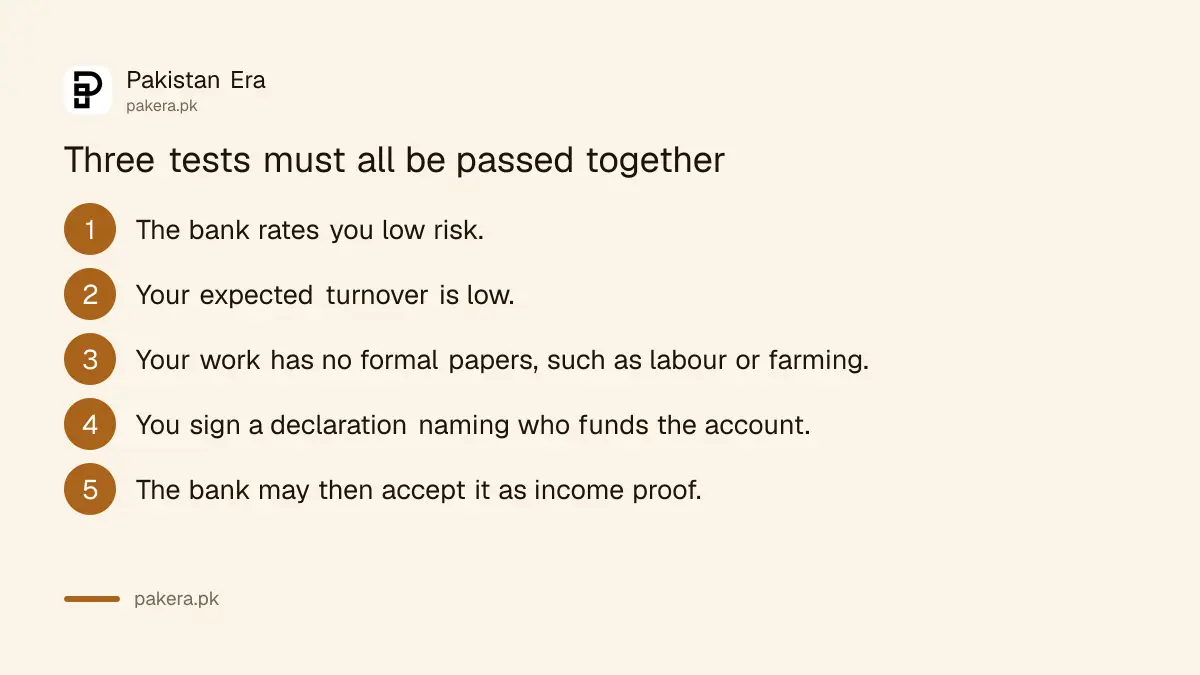
If you fail one test, for example a very large expected turnover, the bank may ask for documents. That is allowed. What is not allowed is skipping the three tests.
Who the framework names as possible self-declaration customers
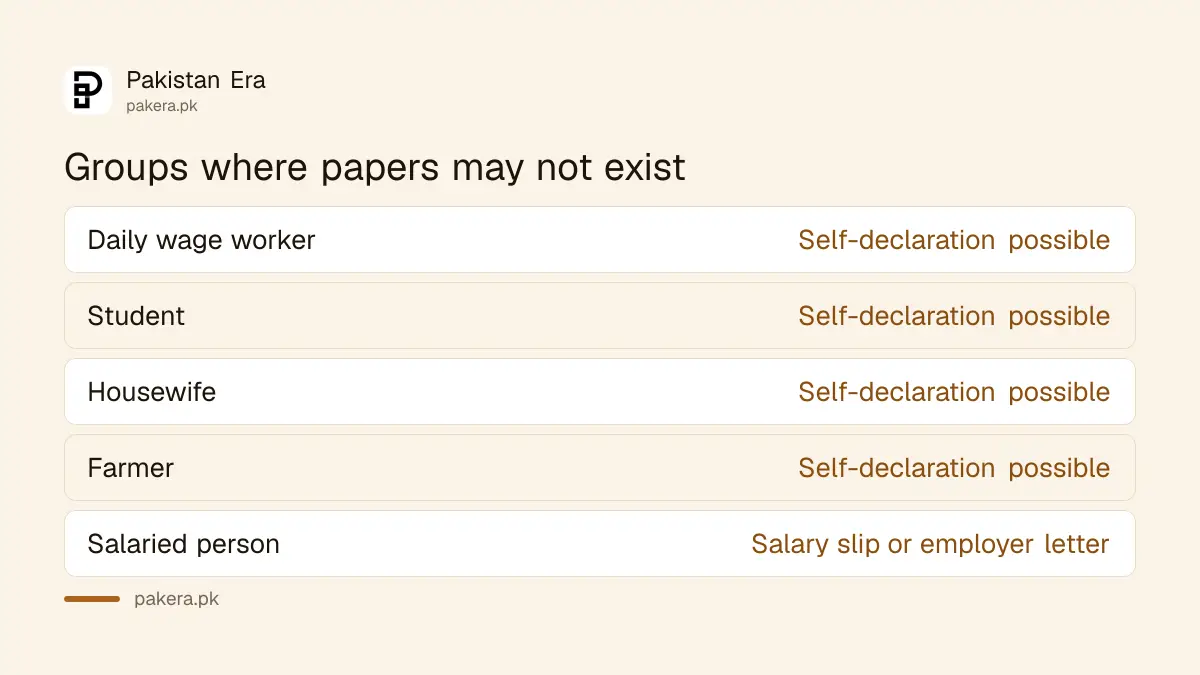
The framework gives a list of professions where papers may not exist. It says "such as", so the list is an example and not a closed list. The table below shows the named groups and what documents the bank may ask for from everyone else.
| Customer group | Self-declaration possible | Other papers the framework lists |
|---|---|---|
| Labour or daily wage worker | Yes, if low risk and low turnover | Any proof of work, receipt of payment |
| Student | Yes, if low risk and low turnover | Student ID card or institute letter |
| Housewife | Yes, if low risk and low turnover | Details of the person who provides funds |
| Farmer or agriculturist | Yes, if low risk and low turnover | Any document showing agriculture income |
| Unemployed | Yes, if low risk and low turnover | Details of the fund provider, stipend or social benefit |
| Self-employed, not a designated business | Yes, if low risk and low turnover | Business letterhead, receipts, account statement |
| Salaried person | Not named in the rule | Salary slip, employer letter, job card |
What the declaration must say
The framework says the declaration should include the name, ID document number and relationship of the person who provides the funds. If your son sends you money, his name, CNIC number and the words "son" belong on it.
A single document can cover both your profession and your source of income. The bank should not ask for two papers where one already shows both.
The bank also sets thresholds, such as expected monthly income or turnover. If your account goes past that level, it can ask for more evidence. So a declaration is a starting point, not a permanent exemption. Tell the bank the real figure. A figure that is too low may trigger questions later.
What to do when the bank still asks for papers
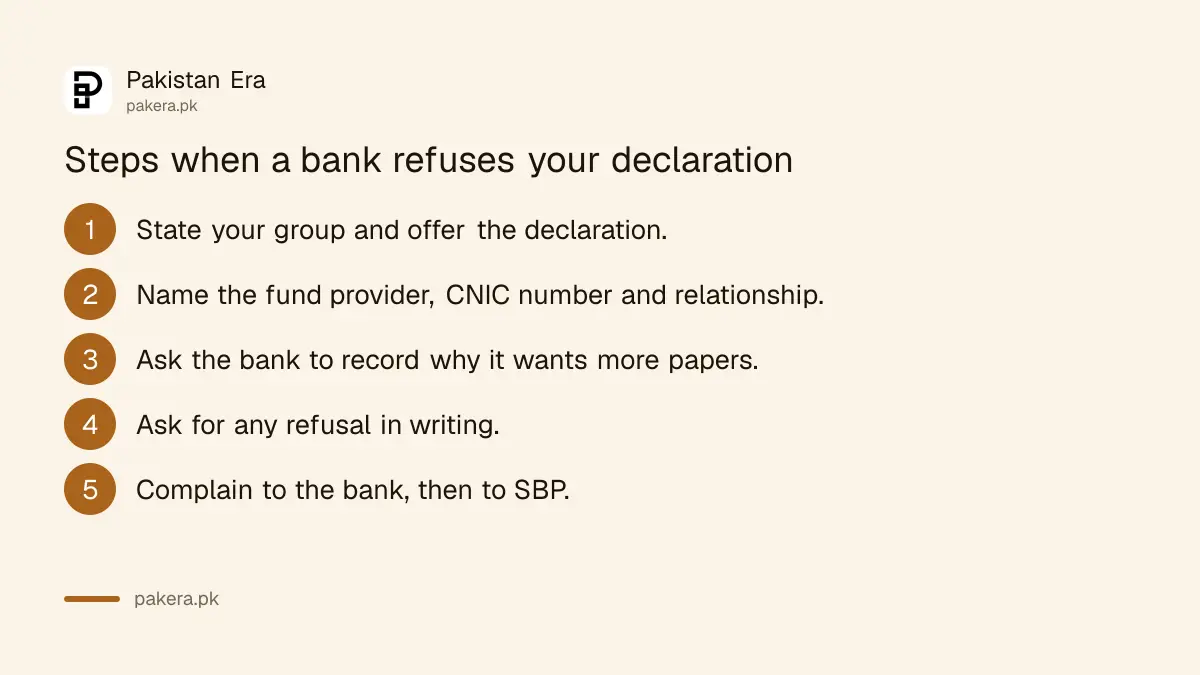
Ask politely for the reason and mention the framework. A bank that asks for more than the standard form must write down why. If it still does not accept your declaration, use the steps below.
- Say which group you belong to, for example "I am a student with a scholarship."
- Offer the self-declaration with the fund provider's name, CNIC number and relationship.
- Ask the officer to record the reason if the bank wants more documents.
- If it refuses to open the account, ask for the reason in writing.
- Take the written reason to the bank's complaint unit, then to SBP.
The complaint route is the same one used for other banking problems. Our guides on the SBP Sunwai complaint portal and the Banking Mohtasib complaint process show how to file.
Where this rule meets other account types
Several account types already use a self-declaration. The framework requires one for source of income on a branchless banking account, and for residency, source of funds and beneficial ownership on an Asaan account. Our guides to the Asaan digital account and the Asaan mobile account cover those two.
The bank must also finish its decision within two working days for an individual, as we explained in what to do when account opening is pending. If you need the basic steps first, start with how to open a bank account in Pakistan.
Common questions
Can a bank refuse my account because I have no salary slip?
Not on that ground alone if you qualify for the self-declaration route. The bank must first test your risk level, turnover and profession. If it refuses, ask for the reason in writing.
Does a self-declaration work at a mobile wallet company too?
Yes, the framework covers wallet providers as well as banks. The wallet account type still has its own limits, so the declaration only settles the income proof question.
Is a housewife allowed to open an account without a job?
Yes. The framework names housewives among the groups where a formal document may not exist. The declaration should name the person who gives her the funds.
What happens if my turnover grows later?
The bank can ask for documents once your turnover crosses its threshold. Keep receipts and statements so you can answer quickly.
Does this rule remove the CNIC fingerprint check?
No. Identity verification is a separate step. The self-declaration only replaces the paper proof of profession and income.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked on 13 October 2026, Pakistan time. We read SBP's Consolidated Customer Onboarding Framework and its BPRD Circular Letter No. 09 of 2026, dated 24 March 2026. We did not visit a branch, so we cannot say how any bank applies the rule in practice.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.