Before You Guarantee a Bank Loan in Pakistan: What SBP Says the Bank Must Tell You
SBP says a bank must tell a loan guarantor they owe the full debt with mark-up, give copies of the papers and let them withdraw before payout. Read your rights.
Short answer: Before you sign as a guarantor for a bank loan in Pakistan, SBP says the bank must tell you that you are liable for the whole debt if the borrower defaults, including mark-up and charges. It must give you copies of the loan papers, and you may withdraw in writing before the loan is paid out.
A cousin asks you to "just sign here" so his shop loan can go through. It feels like a favour that costs nothing. The State Bank of Pakistan (SBP) treats it as a serious promise, and it has set out what a bank must do before it takes your signature.
We read SBP's Business Conduct and Fair Treatment of Consumers Regulatory Framework on 12 October 2026. It comes with BPRD Circular No. 04 of 2025, dated 17 October 2025. This guide uses sections 3.2.3.1 and 3.2.3.3. We have not seen any bank's guarantee form, so we cannot say what a particular bank asks you to sign.
A guarantor is liable for the full debt, with mark-up and charges
SBP says the bank must tell a guarantor explicitly that, if the borrower defaults, the guarantor is liable for the outstanding debt, including mark-up and associated charges. It must also tell you that you may seek independent legal or professional advice before you sign.
In plain words, you are not a witness. If the borrower stops paying, the bank can come to you for the whole amount. That includes the profit or interest and the fees that have built up.
The framework puts the burden on the bank to explain this. A signature collected at the counter with no explanation does not meet the rule.
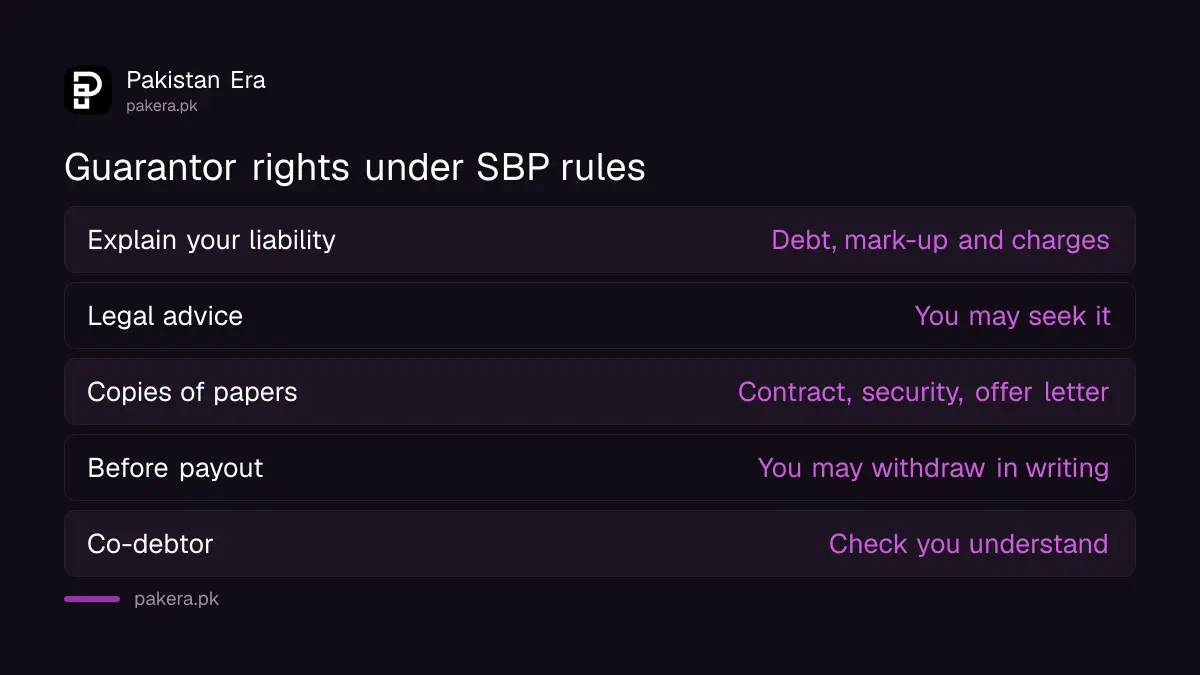
| Your position | What the bank must do |
|---|---|
| Guarantor | Explain that you owe the debt, with mark-up and charges, if the borrower defaults |
| Guarantor | Tell you that you may take independent legal or professional advice |
| Guarantor | Give you a copy of the credit contract, the security contracts and the final offer letter with terms |
| Guarantor, before the loan is paid out | Accept your written or email notice that you withdraw |
| Co-debtor | Verify your identity and relation to the borrower, and check you understand your liability for the full debt |
You must receive copies of the loan papers before you decide
The bank must give a guarantor a copy of the credit contract, the related security contracts, the final offer letter and any terms and conditions that apply. These papers show the amount, the rate, the tenor and the collateral, so you can judge the risk.
Ask for the full set, not only the page with your signature line. Check the loan amount, the repayment period, what the borrower has pledged and any clause on late payment charges. Our guide on loan rate and early repayment rights lists the clauses that should not be there.
If the papers are not ready, do not sign. The framework wants you to decide with the final documents in hand.
You can withdraw before the loan is paid out
A guarantor keeps the right to withdraw before credit is provided, by sending the bank an acknowledged written notice or email. After the money is paid out, withdrawing is no longer so simple, so decide before that point.
Keep proof that the bank received your notice, such as a stamped copy or the sent email. If you change your mind, do it in writing and do it quickly, because a loan can be released within days of approval.
A joint debtor has a related right. Where a person is jointly and severally liable under a facility, the framework lets him end his liability for renewals and future advances by written notice. This works only where the bank itself can stop giving further credit to the other debtors under the same facility.
A guarantor or referee must not be harassed
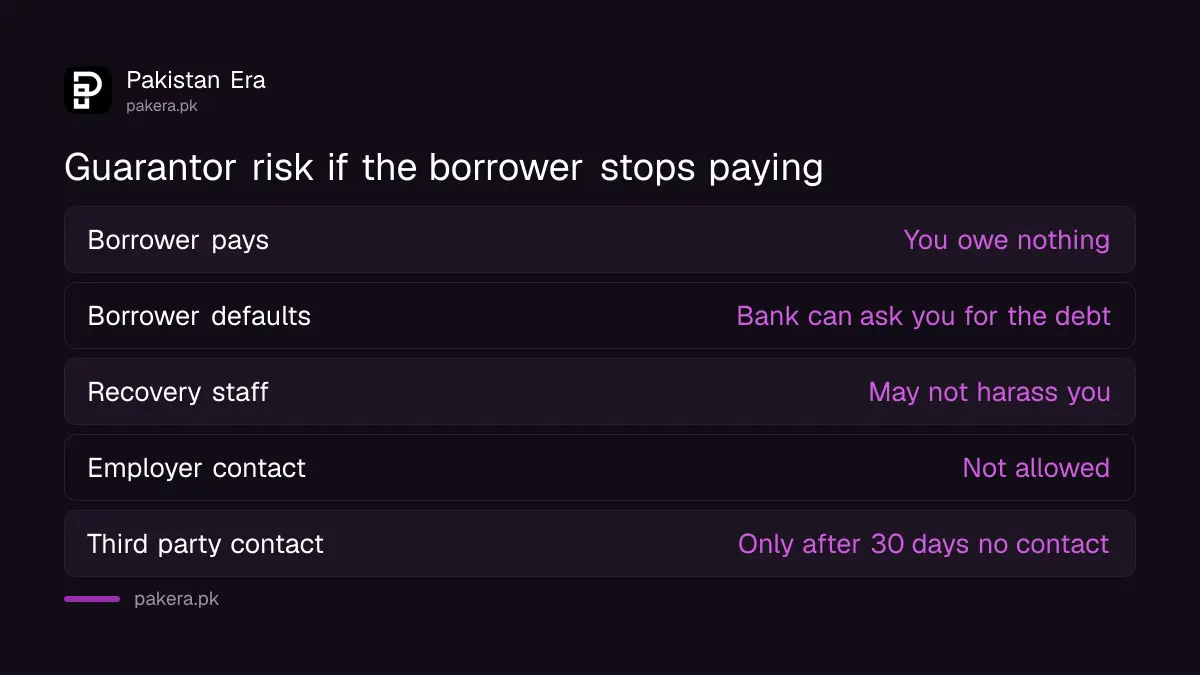
If the borrower stops paying, recovery staff may not harass or humiliate family members, referees or friends, and they may not contact the borrower's employer. They may take information from third parties only when the borrower has been out of contact for 30 days after the first missed payment.
That is not the same as saying you cannot be asked to pay. A guarantor can be asked to pay lawfully. What the bank may not do is shame you, threaten you or call your workplace.
Our guide on stopping recovery agent harassment sets out the 14 day notice rule and where to complain. To see how a bank records a loan, read our guide on checking your credit report.
Questions to ask before you guarantee a loan
Ask for the loan amount, tenor, rate and collateral in writing, and ask how much you would owe if the borrower missed three payments. Decide whether you could pay that sum from your own money.
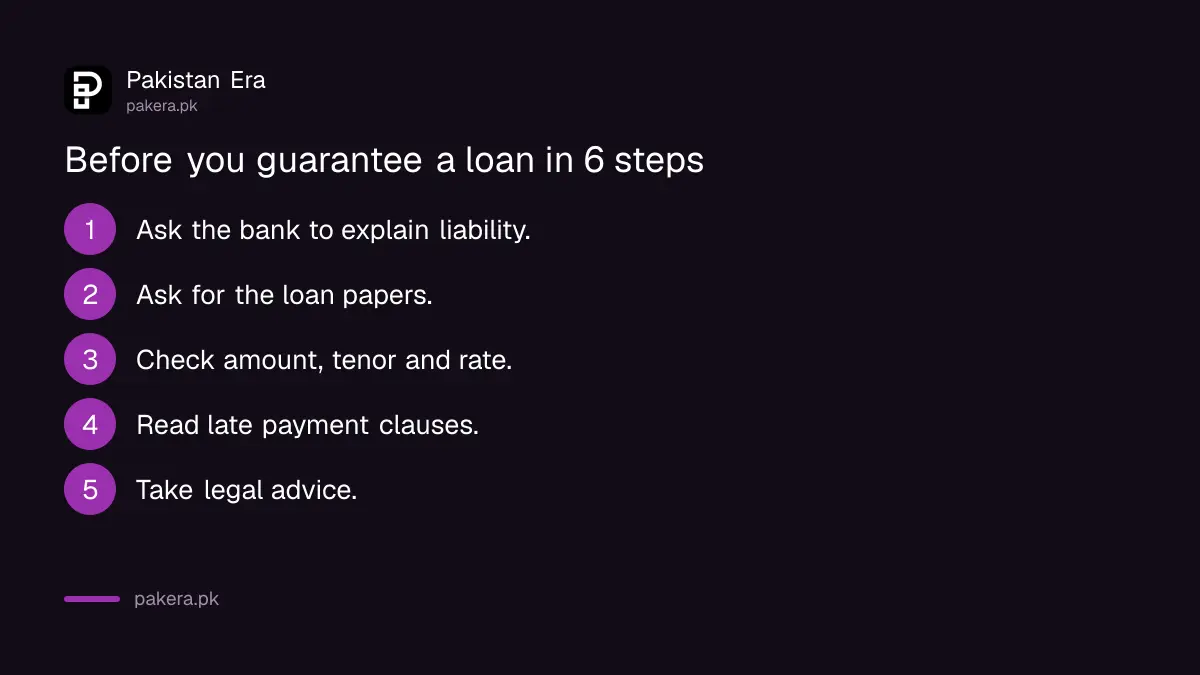
- Ask the bank to explain your liability in plain words, and ask it to write it down.
- Ask for copies of the credit contract, the security contracts and the final offer letter.
- Check the loan amount, the repayment period, the rate and what is pledged.
- Read the late payment clause and the early repayment clause.
- Take the papers to a lawyer or a trusted professional before you sign.
- If you decide against it, send a written or email withdrawal and keep proof of receipt.
Business loans often ask for a guarantor. Our guide to an SME loan in Pakistan shows the limits that banks apply without collateral, and our personal loan comparison shows what banks ask for.
Common questions
Am I responsible for the loan if I sign as a guarantor in Pakistan?
Yes, if the borrower defaults. SBP says the bank must tell you that you are liable for the outstanding debt, including mark-up and associated charges.
Can I get a copy of the loan papers as a guarantor?
Yes. The bank must give you the credit contract, the related security contracts, the final offer letter and any terms and conditions.
Can I withdraw after I have signed?
You can withdraw before the credit is provided, by acknowledged written notice or email to the bank. After disbursement, take legal advice, because the loan is already in force.
Must the bank let me talk to a lawyer first?
It must tell you that you may seek independent legal or professional advice. Take the papers home and use that time.
Can recovery staff phone my workplace if I am a guarantor?
The ban on contacting the borrower's employer is written for the borrower. Staff may not harass or humiliate referees and friends, and a guarantor can complain if they do.
Where do I complain if the bank gave me nothing to read?
Write to the bank's complaint unit, then take it to the Banking Mohtasib or the SBP Sunwai portal.
How we verified this
What we checked, where we read it, and what we could not confirm.
We read BPRD Circular No. 04 of 2025 and the framework on 12 October 2026, sections 3.2.3.1, 3.2.3.2 and 3.2.3.3. We are not lawyers, and this is not legal advice. We did not read any bank's guarantee form, and the framework can be amended.
About the author
Technology Journalist & Multimedia Producer
Ahmad Ali is a technology journalist and multimedia producer at Pakistan Era, joining the team in October 2026. He covers consumer technology and digital life for Pakistani readers, combining research with hands-on product testing.