Solar Loan in Pakistan: Bank Terms, Rates and Down Payments Compared
Compare solar loans from Alfalah, JS Bank, Meezan, MCB Islamic, Bank AL Habib and Askari: limits, tenors, down payments and a worked Rs 1.2 million instalment.
A bank solar loan in Pakistan runs 3 to 10 years and you pay 15% to 30% of the system price up front. Bank Alfalah prices home solar at 1-year KIBOR plus 3% for salaried borrowers, about 15.68% today. On a Rs 1.2 million loan over 5 years, that is about Rs 28,978 a month.
Banks now finance panels, inverters and batteries, and they pay the installer directly. The catch is that every bank has its own cap, tenor and down payment, and most do not print a rate at all.
On 7 October 2026 we opened each bank's own solar finance page and read what it says. KIBOR, the interbank rate that banks price from, was 12.68% for 1 year on the State Bank of Pakistan (SBP) home page on 5 October 2026.
Banks that publish solar loan terms
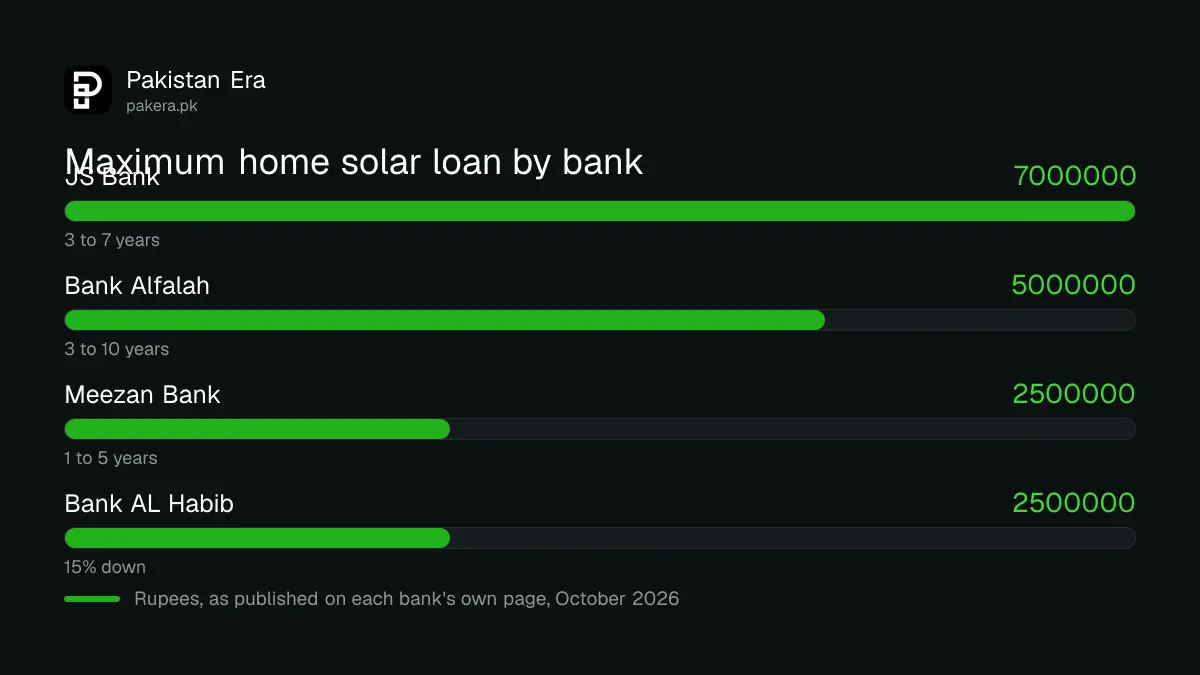
Six banks publish residential or small business solar terms on their own pages: Bank Alfalah, JS Bank, Meezan Bank, MCB Islamic Bank, Bank AL Habib and Askari Bank. Loan caps run from Rs 2.5 million to Rs 20 million. Tenors run from 1 to 10 years.
| Bank and product | Amount and tenor | Down payment | Rate on the page |
|---|---|---|---|
| Bank Alfalah Home Solar Finance | Up to Rs 5 million, 3 to 10 years | Not stated on the page | 1Y KIBOR + 3% (salaried), + 4% (self-employed) |
| Alfalah Islamic Green Finance | 3 KW to 100 KW, 3 to 10 years | Finances up to 80%, so 20% down | Not published |
| JS GharApna Solar Finance | Rs 300,000 to Rs 7 million, 3 to 7 years | 20% up to Rs 6 million, 30% up to Rs 7 million | Not published |
| Meezan Solar Panel Financing | Rs 100,000 to Rs 2.5 million, 12 to 60 months | 15% to 50% on grid, 30% to 50% off grid | Not published |
| MCB Islamic Solar Energy Solution Finance | Up to Rs 20 million, up to 10 years | 20% minimum | "Competitive", no figure |
| Bank AL Habib Renewable Energy Solutions | Up to Rs 2.5 million, equal monthly instalments | 15% minimum | Not published |
Only Alfalah prints its pricing. For the others, ask for the Key Fact Statement, which shows the full rate and every charge.
Alfalah is the only bank that prints a solar rate
Bank Alfalah prices home solar finance at 1-year KIBOR plus 3% for salaried borrowers and plus 4% for the self-employed. A hybrid option fixes your instalment for a set period, then floats.
With 1-year KIBOR at 12.68%, that is 15.68% for a salaried borrower and 16.68% for a self-employed one. The rate floats with KIBOR. Our explainer on the SBP policy rate and your loan instalment shows how that works.
Alfalah wants a net monthly income of Rs 50,000 for salaried applicants and Rs 100,000 for the self-employed. The house must be residential and owned by you, your spouse or a blood relative, with their consent in writing.
A Rs 1.2 million solar loan costs Rs 28,978 a month over 5 years
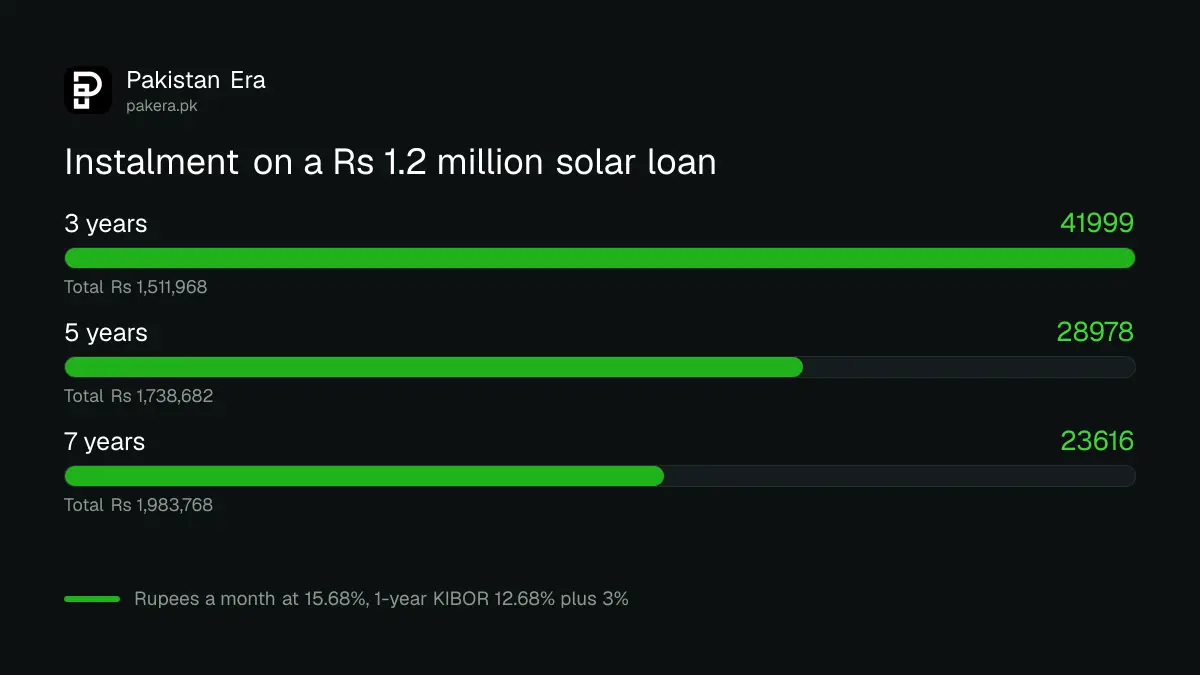
Take a Rs 1.5 million solar system and 20% down. You pay Rs 300,000 and borrow Rs 1.2 million. At Alfalah's salaried rate of 15.68%, the instalment is Rs 28,978 over 5 years. A longer term lowers the instalment but raises the total cost.
The working, so you can repeat it:
- Monthly rate: 15.68% divided by 12 is 0.013067.
- Instalments: 5 years times 12 is 60.
- Instalment = loan x monthly rate, divided by (1 minus (1 + monthly rate) to the power of minus 60).
- That is 15,680 divided by 0.54108, which is Rs 28,978 a month.
| Term | Monthly instalment | Total repaid | Cost of borrowing |
|---|---|---|---|
| 3 years | Rs 41,999 | Rs 1,511,968 | Rs 311,968 |
| 5 years | Rs 28,978 | Rs 1,738,682 | Rs 538,682 |
| 7 years | Rs 23,616 | Rs 1,983,768 | Rs 783,768 |
This is our own arithmetic. It assumes KIBOR stays flat and leaves out the processing fee and insurance premium, which are real costs.
Put your electricity bill into the solar payback calculator to see if the loan pays for itself.
Islamic banks use shared ownership, not interest
Meezan finances solar on Musawamah, a sale at an agreed price paid in instalments. MCB Islamic and Alfalah Islamic use Diminishing Musharakah, where the bank co-owns the system and you buy its share over time. You still pay a profit rate, but it is not called interest.
Meezan lists a processing charge of Rs 6,000 plus FED and a minimum income of Rs 100,000 a month for salaried applicants. MCB Islamic offers its product in Karachi, Lahore, Faisalabad, Islamabad and Rawalpindi only.
JS Bank also lends under a climate fund programme
JS Bank runs two solar products. GharApna finances homes. The Pakistan Distributed Solar Project, backed by the Green Climate Fund, prices at KIBOR plus the bank's spread, runs 3 to 7 years and needs no additional collateral.
GharApna wants hypothecation of the system, a personal guarantee and post-dated cheques. The borrower must be an active tax filer with an NTN, aged 27 or more, earning Rs 75,000 a month if permanent.
Small business solar loans come with different caps
Askari Ujala Finance lends to small businesses for 10 to 200 KW systems, up to Rs 15 million, and to medium ones for 30 to 500 KW, up to Rs 25 million. It asks for 20% equity, runs 5 years including a 3-month grace period, and accepts only Tier 1 inverters.
Alfalah's Green Energy product covers 4 KW to 1,000 KW with net metering, for up to 5 years. For a home, it caps financing at Rs 2.5 million on rented premises and Rs 4 million on owned ones. Check what net metering pays today before you size the system.
What the State Bank requires and what we could not confirm
SBP's housing finance rules, Circular 04 of 18 August 2026, set a 10 year tenor for renewable energy finance. HBL's page lists an SBP refinance scheme for renewable energy at 6% "or as per latest SBP directives". We could not confirm it is open to new borrowers, so ask HBL in a branch.
- Faysal Bank: its Islami solar page sat behind a security check and would not open for us. A search summary reports Rs 100,000 to Rs 10 million over 1 to 7 years. Treat that as unconfirmed.
- UBL and Standard Chartered: we found no current solar loan page, so we left them out.
The Punjab free solar scheme needs no loan at all. If you plan to add batteries, read how battery storage changes the cost.
How to apply for a solar loan
Get a quotation from your bank's approved installer first, because the bank pays the vendor directly. Then take your CNIC, salary slips or tax returns and 6 to 12 months of bank statements to the branch or portal.
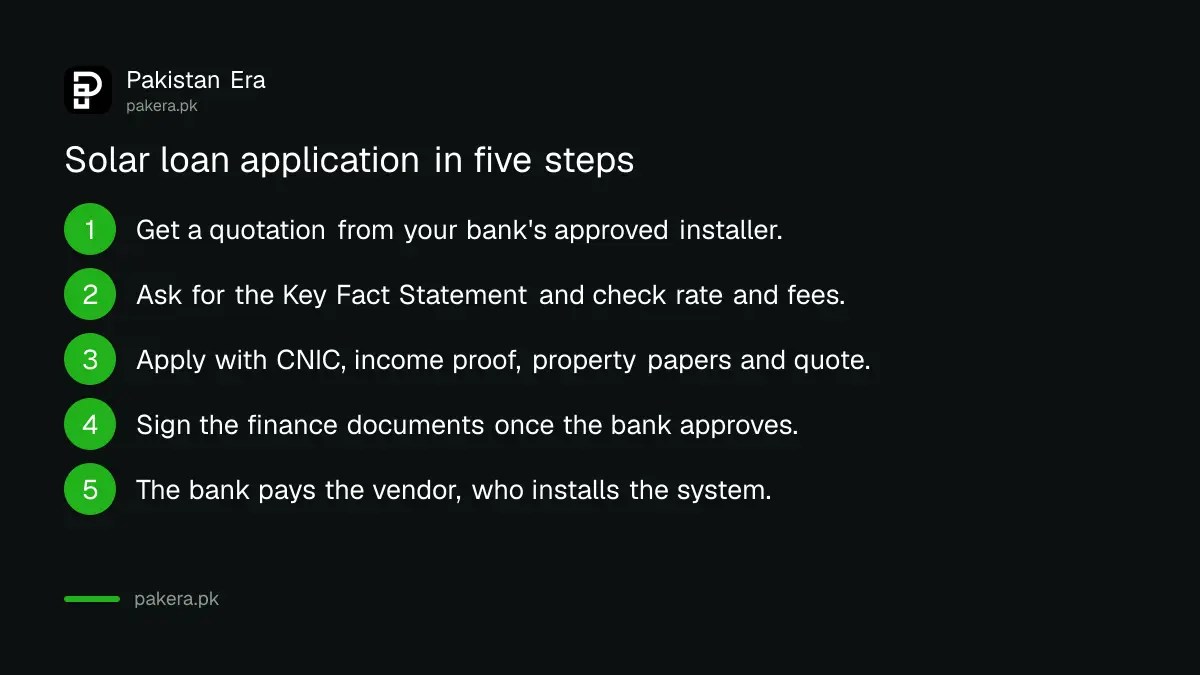
- Ask your bank for its approved vendor list and get a quotation.
- Ask for the Key Fact Statement and check the rate, fee and insurance cost.
- Submit the application with CNIC, income proof, property papers and the quotation.
- Sign the finance documents after approval.
- The bank pays the vendor, who installs the system.
If your income is borderline, add a spouse or blood relative as co-borrower. Alfalah allows up to two. The personal loan comparison shows how banks apply the debt limit.
Common questions
Which bank gives the cheapest solar loan in Pakistan?
We cannot say, because only Bank Alfalah prints a rate: 1-year KIBOR plus 3% for salaried borrowers. The other banks did not publish one, so compare the Key Fact Statements.
How much down payment does a solar loan need?
Between 15% and 50%. Bank AL Habib asks 15% and JS Bank and MCB Islamic ask 20%. Meezan asks 15% to 50% on grid, depending on your credit history.
Can I get a solar loan without an NTN?
Not at JS Bank, whose GharApna needs an active tax filer. The other pages we read did not list it, but banks can still ask for tax returns.
Do banks finance batteries and inverters too?
Yes, the loan covers the complete system on the approved vendor's quotation. Check that the quote lists the batteries.
What happens if KIBOR rises during the loan?
On a variable rate loan such as Alfalah's, your instalment rises with it. Ask for the hybrid option if you want a fixed instalment for the first period.
How we verified this
What we checked, where we read it, and what we could not confirm.
Last checked 7 October 2026 on each bank's own page: Bank Alfalah Home Solar Finance, Alfalah Islamic Green Finance and Green Energy, JS Bank GharApna and its Pakistan Distributed Solar Project page, Meezan Solar, MCB Islamic Solar Financing, Bank AL Habib's individual financing page, Askari Ujala Finance and HBL's SBP refinance schemes page. KIBOR is from the State Bank of Pakistan home page (5 October 2026). Instalments are our own arithmetic. Rates change, so confirm in the Key Fact Statement before signing. This is not financial advice.
About the author
Senior Writer, Public Services and Technology
Shahid joined us in 2024 as an author. He is a senior contributor to Pakistan's leading technology websites. He writes detailed articles, mostly covering his expertise in the latest tech, mobiles, apps, gadgets, and step-by-step guides. His ideology is to help people understand the latest trends and explain complex methods through very easy-to-understand guides.